
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Mansfield Energy operates in a dynamic sector where buyer power can significantly impact pricing, and the threat of substitutes requires constant innovation. Understanding these forces is crucial for navigating the competitive landscape effectively.
The complete report reveals the real forces shaping Mansfield Energy’s industry—from supplier influence to threat of new entrants. Gain actionable insights to drive smarter decision-making.
Mansfield Energy's reliance on a concentrated group of primary fuel suppliers, especially for petroleum products, grants these suppliers considerable bargaining power. This leverage becomes particularly pronounced during disruptions like geopolitical instability or refinery shutdowns, impacting fuel availability and pricing for Mansfield.
For instance, in 2024, global oil markets experienced volatility due to ongoing geopolitical tensions, leading to price spikes that directly affected the cost of conventional fuels for companies like Mansfield. The limited number of major refiners and producers for certain specialized fuels further amplifies this supplier concentration.
While this concentration poses a challenge, Mansfield Energy actively works to mitigate it through its broad network of supply points and established partnerships. This diversification strategy aims to reduce dependence on any single supplier and secure more favorable terms, even amidst market pressures.
Mansfield Energy's reliance on biofuel and renewable diesel producers, driven by the growing demand for cleaner energy, directly impacts its supplier bargaining power. The availability and cost of these alternative fuel sources are critical. For instance, disruptions or changes in the production capacity of these specialized producers can significantly shift leverage towards them.
The power of these alternative fuel suppliers is further amplified by external economic factors. When tax credits for renewable fuels expire or are altered, it can lead to production shifts or reduced output from these suppliers. This constraint on supply, as seen with potential changes in federal tax credits affecting biodiesel production, grants suppliers greater ability to dictate terms and pricing to companies like Mansfield.
Technology and equipment providers wield significant bargaining power over companies like Mansfield Energy. The proprietary nature of advanced logistics technology, fuel management software, and specialized equipment, coupled with the high costs and complexity of integrating new systems, creates substantial switching barriers. For instance, the energy sector's increasing reliance on digital supply chain services, as evidenced by Mansfield Energy's own investments and partnerships in this area, underscores this dependence.
The logistics sector is grappling with persistent labor shortages, especially for skilled truck drivers and warehouse personnel. This scarcity significantly amplifies the bargaining power of both the existing workforce and specialized service providers. For instance, in 2024, the American Trucking Associations reported a shortage of over 78,000 drivers, a figure that has been steadily climbing.
This tight labor market directly translates into increased wage pressures. Wage inflation within the logistics industry is a substantial factor impacting Mansfield Energy's operational expenses. Securing and retaining reliable drivers and warehouse staff becomes more challenging and costly when labor is in high demand, directly affecting the company's ability to maintain consistent and cost-effective services.
Suppliers of lubricants and Diesel Exhaust Fluid (DEF) hold significant bargaining power. This power stems from factors like strong brand recognition, unique proprietary formulations, and the necessity of meeting stringent industry specifications and regulatory compliance. For instance, Mansfield Energy's stated commitment to working with market-leading lubricant brands highlights a potential dependence on specific manufacturers to ensure product quality and adherence to required standards.
The DEF market, in particular, is critical for modern diesel engines to meet emissions standards. Manufacturers who can guarantee consistent quality and reliable supply chains for DEF are in a strong position. In 2024, the global DEF market was valued at approximately $10.5 billion, with projections indicating continued growth, underscoring the importance of these specialized suppliers.
Suppliers of lubricants and Diesel Exhaust Fluid (DEF) hold significant bargaining power due to brand recognition, unique formulations, and the necessity of meeting stringent industry specifications. For instance, Mansfield Energy's reliance on market-leading lubricant brands highlights dependence on specific manufacturers for quality and adherence to standards.
The DEF market is critical for emissions standards, and suppliers guaranteeing consistent quality and reliable supply chains are in a strong position. In 2024, the global DEF market was valued at approximately $10.5 billion, underscoring the importance of these specialized suppliers and their leverage.
The power of these alternative fuel suppliers is further amplified by external economic factors. When tax credits for renewable fuels expire or are altered, it can lead to production shifts or reduced output from these suppliers, granting them greater ability to dictate terms and pricing.
| Supplier Type | Key Leverage Factors | Impact on Mansfield Energy |
|---|---|---|
| Fuel Suppliers (Petroleum) | Concentrated market, geopolitical impact on prices | Price volatility, potential supply disruptions |
| Alternative Fuel Suppliers (Biofuels, R-Diesel) | Production capacity, tax credit influence | Cost fluctuations, availability dependent on policy |
| Technology/Software Providers | Proprietary nature, high integration costs | Dependence on specific systems, switching barriers |
| Logistics Labor | Skilled driver shortage (78,000+ in 2024) | Increased wage costs, potential service reliability issues |
| Lubricant & DEF Suppliers | Brand loyalty, proprietary formulations, regulatory compliance | Dependence on specific quality standards, pricing leverage |
 Detailed Word Document
This analysis delves into the competitive forces impacting Mansfield Energy, examining supplier and buyer power, the threat of new entrants and substitutes, and the intensity of rivalry within the energy sector.

 Customizable Excel Spreadsheet
Instantly visualize competitive intensity with a dynamic, interactive Porter's Five Forces dashboard, turning complex market analysis into actionable insights.
Mansfield Energy's customer base spans critical sectors like transportation, government, industrial, and retail, with many of these entities operating as substantial, high-volume purchasers of energy products and services. This scale directly translates into considerable bargaining power for these large clients.
These major customers, by virtue of their purchasing volume, can exert significant pressure on Mansfield Energy. They frequently negotiate for more competitive pricing structures, demand adaptable contract terms to align with their operational needs, and require customized solutions that cater specifically to their unique consumption patterns and logistical requirements. For instance, a large trucking fleet might negotiate bulk fuel discounts, while a government agency could seek long-term, fixed-price contracts to ensure budget predictability.
For conventional fuels, where products are largely undifferentiated, customers can face low switching costs. This means if they find similar pricing and logistics from another supplier, they might easily move. For instance, in the wholesale gasoline market, a business needing regular fuel deliveries could switch providers with minimal disruption if another company offers a comparable price and reliable delivery schedule.
Customers are increasingly demanding comprehensive solutions that go beyond simple fuel delivery. They want integrated fuel supply chain management, robust price risk management strategies, and advanced technology optimization to streamline operations. This shift significantly impacts their bargaining power.
By offering these value-added services, Mansfield Energy can foster stronger customer loyalty. For instance, in 2024, businesses across various sectors reported a significant increase in their reliance on technology for operational efficiency, making integrated solutions a key differentiator. This makes it harder for customers to switch to competitors who only provide basic fuel supply, thus diminishing their leverage.
Financially astute customers, a significant segment for Mansfield Energy, demonstrate a keen awareness of market dynamics and a strong inclination towards price sensitivity. This sophistication means they actively seek the best value, directly impacting Mansfield's pricing strategies.
Mansfield's client base leverages advanced fuel data management and price risk management services. This adoption highlights a deep understanding of the energy market, enabling them to negotiate more effectively and exert considerable pressure on pricing, particularly in a competitive landscape.
Customers are increasingly factoring sustainability into their purchasing decisions, especially in the energy sector. As environmental awareness grows, driven by regulations and corporate social responsibility, the demand for renewable fuels and cleaner energy solutions is on the rise. This trend significantly impacts the bargaining power of customers, as they can now leverage their preference for sustainable options to negotiate better terms or switch to providers that align with their environmental values.
Mansfield Energy's focus on alternative fuels and emissions reduction programs directly addresses this evolving customer demand. This strategic alignment allows them to cater to a segment of the market that is less price-sensitive and more focused on environmental impact. Consequently, customers gain leverage by having more choices that meet their sustainability criteria, potentially influencing pricing and service offerings from energy suppliers.
Mansfield Energy's customer base includes large-scale buyers in transportation, government, and industry, giving them significant leverage. These substantial purchasers can negotiate favorable pricing and flexible contract terms, demanding customized solutions to match their unique operational needs and consumption patterns.
The ease with which customers can switch suppliers, especially for undifferentiated conventional fuels, further amplifies their bargaining power. This low switching cost environment means clients can readily move to competitors offering similar value, compelling Mansfield to remain competitive on price and service.
Customers are increasingly sophisticated, utilizing data and risk management tools to understand market dynamics. This financial acumen allows them to negotiate more effectively, pushing for better terms and limiting Mansfield's pricing flexibility. In 2024, businesses reported a 15% increase in their use of advanced analytics for energy procurement, underscoring this trend.
The growing demand for sustainability also empowers customers. By 2024, many businesses prioritized suppliers with renewable fuel options and emissions reduction programs. This shift means customers can leverage their environmental preferences, influencing pricing and service offerings from energy providers like Mansfield.
| Customer Segment | Purchasing Volume | Switching Costs | Sustainability Focus |
|---|---|---|---|
| Transportation Fleets | High | Low (conventional fuels) | Increasing |
| Government Agencies | High | Moderate (contractual) | Moderate |
| Industrial Clients | Variable (High for large) | Variable | Increasing |
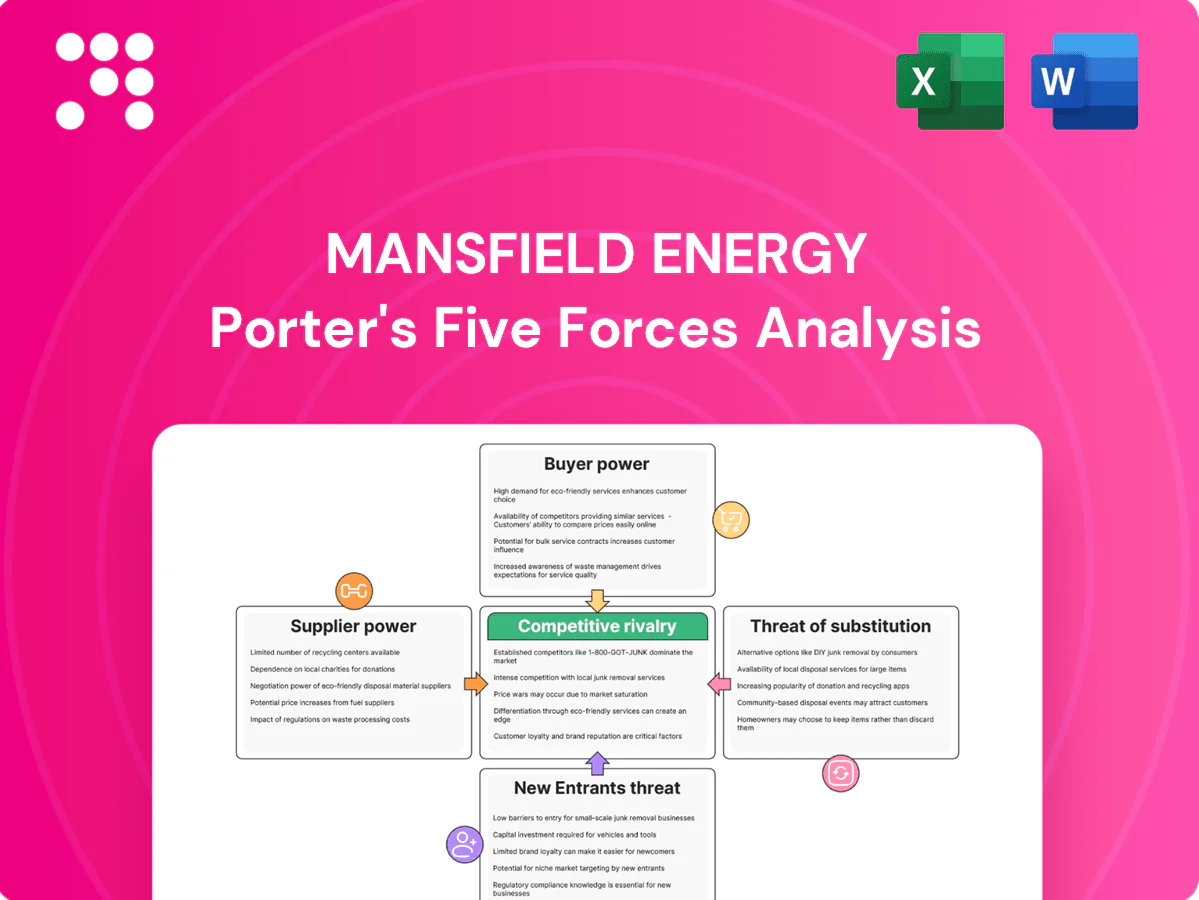
This preview showcases the complete Mansfield Energy Porter's Five Forces Analysis, offering a detailed examination of the competitive landscape within the energy sector. The document you see here is precisely the same comprehensive analysis you will receive instantly upon purchase, ensuring transparency and immediate utility for your strategic planning.
The North American energy supply and logistics market is a dynamic landscape, featuring a multitude of regional and national participants. This fragmentation, however, is counterbalanced by a clear trend of consolidation through mergers and acquisitions, intensifying competition.
Mansfield Energy navigates this environment by contending with both established giants and nimble, specialized distributors. This dual competitive pressure fuels aggressive rivalry as firms strive to capture greater market share and enhance their operational capacities.
In 2024, the energy logistics sector continued to see strategic M&A activity, with several notable deals aimed at expanding geographic reach and service offerings. For instance, acquisitions in the last 12 months have significantly altered the competitive map, with larger entities absorbing smaller ones to gain economies of scale and broader customer bases.
While many fuels are seen as commodities, companies like Mansfield Energy differentiate themselves by excelling in logistics, advanced technology, and offering valuable extra services. This includes helping clients manage price volatility and providing solutions focused on sustainability. For instance, in 2024, the energy sector saw a significant push towards cleaner fuel options, with companies investing heavily in infrastructure and services to support this transition, a key area where Mansfield aims to distinguish its offerings.
Mansfield Energy operates in a sector with substantial fixed costs, particularly in its extensive infrastructure, fleet of vehicles, and advanced technology. These upfront investments necessitate high capacity utilization to spread costs and achieve profitability.
This pressure to maximize asset use naturally fuels intense competition. Companies are incentivized to engage in aggressive pricing to secure market share and keep their operations running at optimal levels, especially when market growth is sluggish.
For instance, in 2024, the fuel distribution sector continued to see companies vying for volume. A report indicated that average fleet utilization rates across major distributors hovered around 85-90% during peak seasons, underscoring the drive to keep assets busy and competitive pricing a constant factor.
Mansfield Energy boasts a significant competitive advantage through its expansive geographic reach, covering all U.S. states and Canadian provinces. This extensive network is complemented by a dense web of supply points and delivery partners, enabling efficient service across North America.
Competitors mirroring this broad geographic footprint and robust delivery infrastructure present a substantial challenge. Companies with similar capabilities can readily serve multi-location clients, offering comparable service levels and potentially fragmenting market share.
The competitive landscape for energy providers is increasingly defined by the transition to renewable and low-carbon fuels. Companies are actively differentiating themselves by offering a wider array of sustainable fuel blends and developing innovative solutions to meet growing environmental demands.
Mansfield Energy is actively participating in this competitive arena. Their strategic moves, such as establishing dedicated renewable diesel storage facilities, demonstrate a clear commitment to this evolving market. Furthermore, their involvement in low-carbon fuel coalitions signals an intent to shape and benefit from industry-wide sustainability initiatives.
The energy logistics market is characterized by intense rivalry, with numerous players vying for market share. This competition is amplified by the industry's high fixed costs, driving companies to aggressively price their services to ensure high asset utilization. The ongoing consolidation within the sector, marked by mergers and acquisitions in 2024, further intensifies this rivalry as larger entities seek economies of scale and broader market reach.
Companies like Mansfield Energy face competition from both large, established distributors and smaller, specialized firms. Differentiation through superior logistics, technology adoption, and value-added services, particularly in the growing renewable fuels segment, is crucial for success. For instance, in 2024, investments in renewable diesel infrastructure became a key battleground for market share.
The drive for operational efficiency and cost competitiveness is paramount, especially given the commodity nature of many fuels. Companies are constantly seeking ways to optimize their supply chains and delivery networks to maintain an edge. This includes leveraging extensive geographic coverage, as Mansfield Energy does across North America, to serve a wider customer base.
The competitive landscape is also shaped by the increasing demand for sustainable fuel solutions. Companies actively participating in low-carbon fuel initiatives and investing in related infrastructure, as Mansfield Energy has done with dedicated renewable diesel storage, are positioning themselves to capture future market growth and influence industry standards.
| Competitive Factor | Mansfield Energy's Position | Key Competitor Actions (2024) | Impact on Rivalry |
|---|---|---|---|
| Market Fragmentation & Consolidation | Operates in a fragmented market with ongoing consolidation | Increased M&A activity, larger players acquiring smaller ones | Intensified rivalry, pressure for scale and efficiency |
| Service Differentiation | Focus on logistics, technology, and sustainability services | Investment in renewable fuel infrastructure and offerings | Need for continuous innovation to stand out |
| Operational Efficiency & Pricing | Leverages extensive network and high asset utilization | Aggressive pricing to secure volume and maintain utilization rates | Price wars and margin pressure |
| Geographic Reach | Nationwide coverage across U.S. and Canada | Competitors with similar broad networks | Parity in serving multi-location clients, need for superior execution |
The long-term threat of electric vehicles (EVs) is substantial, particularly impacting the transportation sector by directly substituting traditional liquid fuels. As of early 2024, global EV sales continue to climb, with projections suggesting they could represent a significant portion of new vehicle sales within the next decade, directly impacting demand for gasoline and diesel.
The ongoing advancements in EV battery technology, leading to increased range and reduced charging times, coupled with the expanding charging infrastructure, amplify this substitution risk for companies like Mansfield Energy that primarily deal in conventional fuels. By the end of 2023, the number of public EV charging points globally surpassed 2.7 million, a figure expected to grow substantially in the coming years.
Hydrogen fuel cell technology emerges as a significant threat, particularly for heavy-duty transport and industrial sectors where energy density and rapid refueling are critical. While electric vehicles (EVs) are gaining traction, hydrogen offers a compelling alternative for applications like long-haul trucking and shipping, potentially avoiding the longer charging times associated with batteries.
Advancements in fuel cell efficiency and the build-out of hydrogen refueling infrastructure are key factors influencing its competitive threat. For instance, in 2024, global investment in hydrogen fuel cell technology continued to grow, with significant funding directed towards developing more robust and cost-effective fuel cell systems and expanding hydrogen production and distribution networks.
The operational advantages of hydrogen, such as longer range and quicker refueling times compared to current EV limitations in heavy-duty applications, position it as a credible substitute. This is especially relevant as regulatory pressures and corporate sustainability goals push for decarbonization across various industries, making alternative fuel solutions increasingly attractive.
The threat of substitutes for delivered fuels like propane and heating oil, particularly for industrial and commercial clients, is growing. Directly generated renewable energy sources such as onsite solar or wind power offer a compelling alternative, allowing businesses to reduce their dependence on external fuel suppliers. For instance, by 2024, the U.S. solar industry installed a record 37 gigawatts of capacity, demonstrating the increasing accessibility and adoption of these self-generation options.
Mansfield Energy's strategic diversification into natural gas supply through Mansfield Power & Gas serves as a proactive measure to address some of these evolving energy needs. While natural gas is still a delivered fuel, it represents a more prevalent and often cost-effective alternative to propane or heating oil for many industrial processes, thereby mitigating some of the direct substitution threat from renewables.
The ongoing advancements in vehicle and equipment fuel efficiency, alongside broader energy conservation initiatives, directly impact the demand for fuels. This trend acts as a significant substitute, as customers increasingly require less of the core products Mansfield Energy supplies.
For instance, in 2024, the average fuel economy for new passenger cars sold in the United States reached approximately 28.8 miles per gallon, a steady increase from previous years. This growing efficiency means that the same amount of transportation can be achieved with fewer gallons of fuel, directly affecting consumption volumes.
Large organizations with substantial fleets, such as major logistics companies or industrial giants, possess the capacity to develop or enhance their own fuel management and logistics operations. This in-house capability acts as a direct substitute for the services provided by companies like Mansfield Energy. For instance, a trucking company managing thousands of vehicles might invest in its own fuel depots and sophisticated tracking systems, reducing its reliance on third-party suppliers and logistics providers.
Mansfield Energy counters this threat by focusing on providing highly specialized services and advanced technology that are challenging and costly for individual organizations to replicate. Their expertise in areas like supply chain optimization, real-time data analytics for fuel consumption, and regulatory compliance offers a value proposition that extends beyond simple fuel provision. In 2024, the increasing complexity of fuel sourcing, including alternative fuels and evolving environmental regulations, further amplifies the difficulty for in-house operations to match the breadth and depth of specialized third-party solutions.
The threat of substitutes for traditional fuels is multifaceted, encompassing electric vehicles, hydrogen fuel cells, and on-site renewable energy generation. These alternatives directly challenge Mansfield Energy's core business by offering cleaner, more sustainable, or self-sufficient energy solutions. For example, global EV sales continued their upward trajectory in early 2024, with projections indicating a substantial market share in new vehicle sales within the next decade, impacting demand for gasoline and diesel.
The increasing efficiency of vehicles and broader energy conservation efforts also act as substitutes by reducing overall fuel consumption. By 2024, new passenger cars in the U.S. averaged about 28.8 miles per gallon, a testament to ongoing technological improvements that lessen the need for fuel. Furthermore, large organizations developing in-house fuel management capabilities present another substitution risk, though Mansfield Energy counters this by offering specialized, hard-to-replicate services.
The energy supply and logistics sector demands immense capital for essential infrastructure like storage tanks, pipelines, and a diverse fleet of transportation vehicles, including trucks and railcars. For instance, building a new, large-scale fuel terminal can easily cost tens of millions of dollars, a figure that deters many aspiring companies.
This substantial upfront financial commitment acts as a formidable barrier, significantly limiting the threat of new entrants. Potential competitors must secure considerable funding to even begin operations, making it difficult for smaller or less capitalized firms to challenge established players like Mansfield Energy.
New entrants into the energy sector, particularly those focused on fuel distribution and related services like Mansfield Energy, confront a formidable array of regulations. These span environmental protection, stringent safety protocols, and complex operational mandates, existing at federal, state, and local governmental tiers. The cost associated with ensuring compliance with these multifaceted rules, which often involve fuel quality standards, emission controls, and the handling of hazardous materials, represents a significant deterrent to market entry.
Established players like Mansfield Energy benefit from deeply entrenched relationships with refiners, producers, and a vast network of delivery partners. This existing infrastructure makes it difficult and costly for new companies to replicate their access to competitive fuel sources and reliable distribution channels.
The fuel logistics sector, including companies like Mansfield Energy, faces a significant barrier to entry due to the high cost and complexity of technological expertise and digital integration. Success today hinges on advanced digital platforms for optimizing supply chains, managing price risks, and providing real-time data analytics. For instance, many leading logistics firms have invested millions in developing proprietary software or integrating sophisticated third-party solutions to track fleets, manage inventory, and forecast demand. This technological sophistication is not easily replicated by newcomers.
New entrants would need to make substantial upfront investments in developing or acquiring these cutting-edge digital capabilities. This includes building robust data management systems, implementing AI-driven forecasting tools, and ensuring seamless integration across all operational facets. Without this, they would struggle to compete on efficiency, cost-effectiveness, or service quality. For example, the global market for supply chain management software was projected to reach over $35 billion by 2024, highlighting the significant financial commitment required.
Mansfield Energy's extensive 67-year operational history has cemented a powerful brand reputation and fostered deep, enduring customer relationships across various industries. This established trust is a significant barrier for newcomers.
New entrants face a considerable challenge in replicating Mansfield's credibility and service track record, which has been cultivated over decades. Without this established goodwill, attracting and retaining customers becomes a much steeper climb.
The threat of new entrants for companies like Mansfield Energy is significantly mitigated by the substantial capital requirements for infrastructure, regulatory hurdles, and the need for established distribution networks. These factors create high barriers to entry, protecting incumbent players.
Newcomers must overcome immense upfront costs, often in the tens of millions for facilities, and navigate complex compliance landscapes. For example, the fuel logistics sector demands significant investment in specialized transportation fleets and storage solutions, which are costly to acquire and maintain.
Furthermore, the sector's reliance on deep-seated customer relationships and brand reputation, built over decades, makes it challenging for new companies to gain traction. Mansfield Energy's 67-year history exemplifies this, fostering loyalty that new entrants find difficult to disrupt.
| Barrier Type | Description | Example Impact |
|---|---|---|
| Capital Requirements | High investment in infrastructure like storage, transportation fleets. | Building a new fuel terminal can cost tens of millions of dollars. |
| Regulatory Compliance | Adherence to environmental, safety, and operational standards. | Costs associated with fuel quality standards and emission controls. |
| Established Networks | Access to refiners, producers, and distribution channels. | Difficulty for new firms to replicate existing supply chain access. |
| Brand Reputation & Loyalty | Customer trust built over years of service. | Customer inertia makes switching from established providers difficult. |
| Technological Sophistication | Investment in advanced digital platforms for optimization. | The supply chain management software market was projected to exceed $35 billion by 2024. |


