
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
Unlock Markel’s strategic playbook with our concise Business Model Canvas—three-sentence clarity on how the company creates, delivers, and captures value. Dive deeper: purchase the full Canvas for a section-by-section breakdown, editable files, and actionable insights for investors and strategists.
Markel leverages wholesale brokers and MGAs to access niche and hard-to-place risks, supporting specialty lines that generated roughly $8.0 billion in gross written premiums in 2024. These partners supply underwriting data and distribution reach, improving placement efficiency and deal flow through long-term relationships. Joint marketing and product co-development with broker/MGA networks accelerated specialty growth, contributing materially to Markel’s underwriting pipeline.
Global reinsurers help Markel optimize capital and manage peak exposures through quota-share and excess-of-loss treaties that reduce volatility and free regulatory capital. Structured reinsurance and retrocession programs stabilize earnings and protect the balance sheet by converting large, infrequent losses into predictable net claims. Partner selection prioritizes financial strength and claims-paying reliability, with multi-year arrangements supporting pricing consistency and efficient risk transfer.
Investment managers and co-investors expand Markel Corporation (NYSE: MKL) opportunity sets beyond internal capabilities, adding sector expertise, deal origination, and specialized strategies. Co-investment structures improve alignment and fee efficiency and were increasingly used across Markel Ventures' 2024 deal flow. These partnerships support both the insurance portfolio and Markel Ventures’ acquisitions.
Strong relationships with regulators and rating agencies underpin Markel’s license continuity and access to capital; transparent reporting and conservative reserving support favorable ratings and solvency metrics across product lines. Ongoing engagement ensures compliance in multiple jurisdictions while stable ratings lower cost of capital and strengthen customer and broker confidence.
Technology and claims service providers, including marquee vendors, data feeds, and TPAs, boost Markel underwriting, pricing, and claims accuracy; in 2024 these partnerships accelerated adjudication and enhanced fraud detection across lines. External loss-control and catastrophe-modeling partners sharpen risk selection. Ecosystem connectivity scales operations across Markel’s diversified businesses.
Markel leverages brokers/MGAs to access niche risks, supporting roughly $8.0 billion specialty GWP in 2024. Global reinsurers and structured treaties optimize capital and stabilize earnings. Investment partners and tech/TPA vendors expand deal flow, underwriting analytics and claims efficiency across the portfolio.
| Partner | Role | 2024 impact |
|---|---|---|
| Brokers/MGAs | Distribution, data | $8.0B specialty GWP |
| Reinsurers | Risk transfer | Capital stability |
| Investors/Tech | Co-invest, analytics | Improved claims & growth |
 Detailed Word Document
A comprehensive Business Model Canvas tailored to Markel’s insurance and specialty finance strategy, detailing customer segments, channels, value propositions, revenue streams and key resources with SWOT-linked insights for investor presentations and strategic planning.

 Customizable Excel Spreadsheet
High-level, editable Business Model Canvas for Markel that condenses strategy into a one-page snapshot, saving hours of structuring and enabling quick comparisons across companies or scenarios.
Markel selects, prices and structures coverage for niche and complex risks, leveraging sector specialists to underwrite exposures that standard markets avoid. Underwriters tailor terms and endorsements to sector specifics, driving differentiated margins. Portfolio steering balances growth with risk-adjusted returns, targeting selective expansion (premium growth ~6% in 2024) while maintaining discipline to outperform cycles (combined ratio ~90.9% in 2024).
Timely, fair claims handling is central to customer trust and expense control at Markel, anchoring retention and profitability.
Data-driven reserving and targeted litigation management reduce volatility and inform capital allocation.
Specialized adjusters manage complex casualty and property losses, preserving loss ratios and client relationships.
Closed-loop feedback from claims drives underwriting refinements and product adjustments to lower future loss frequency.
Markel deploys float and permanent capital across public and private assets, managing an invested portfolio of over $30 billion (2024) while balancing liquidity, duration, and risk to compound book value. The team continuously rebalances allocations to align with underwriting cycles and macro conditions. Markel Ventures focuses on durable, cash‑generative businesses (roughly 80–100 operating companies), providing stable earnings and long‑term capital appreciation.
Reinsurance structuring protects Markel against tail risks and earnings volatility through annually optimized quota share, excess of loss, and aggregate covers, tailored to portfolio exposures. Counterparty diversification limits concentration risk across reinsurers and retrocessionaires. Advanced analytics determine attachment points and limit adequacy, feeding renewal negotiations and capital planning.
Markel targets and acquires quality companies outside insurance through Markel Ventures, which by 2024 comprised over 80 operating businesses focused on durable cash flows and strong cultures.
Diligence prioritizes culture fit, cash-flow durability and downside protection; integration preserves autonomy while adding governance, capital support and centralized playbooks to drive scale.
Markel underwrites niche complex risks with sector specialists, targeting selective premium growth (~6% in 2024) and disciplined profitability (combined ratio 90.9% in 2024). Claims, reserving and litigation management reduce volatility; reinsurance and capital allocation protect against tail risk. Markel Ventures holds 80+ operating businesses and an invested portfolio >$30B (2024).
| Metric | 2024 |
|---|---|
| Premium growth | ~6% |
| Combined ratio | 90.9% |
| Invested assets | >$30B |
| Ventures | 80+ companies |
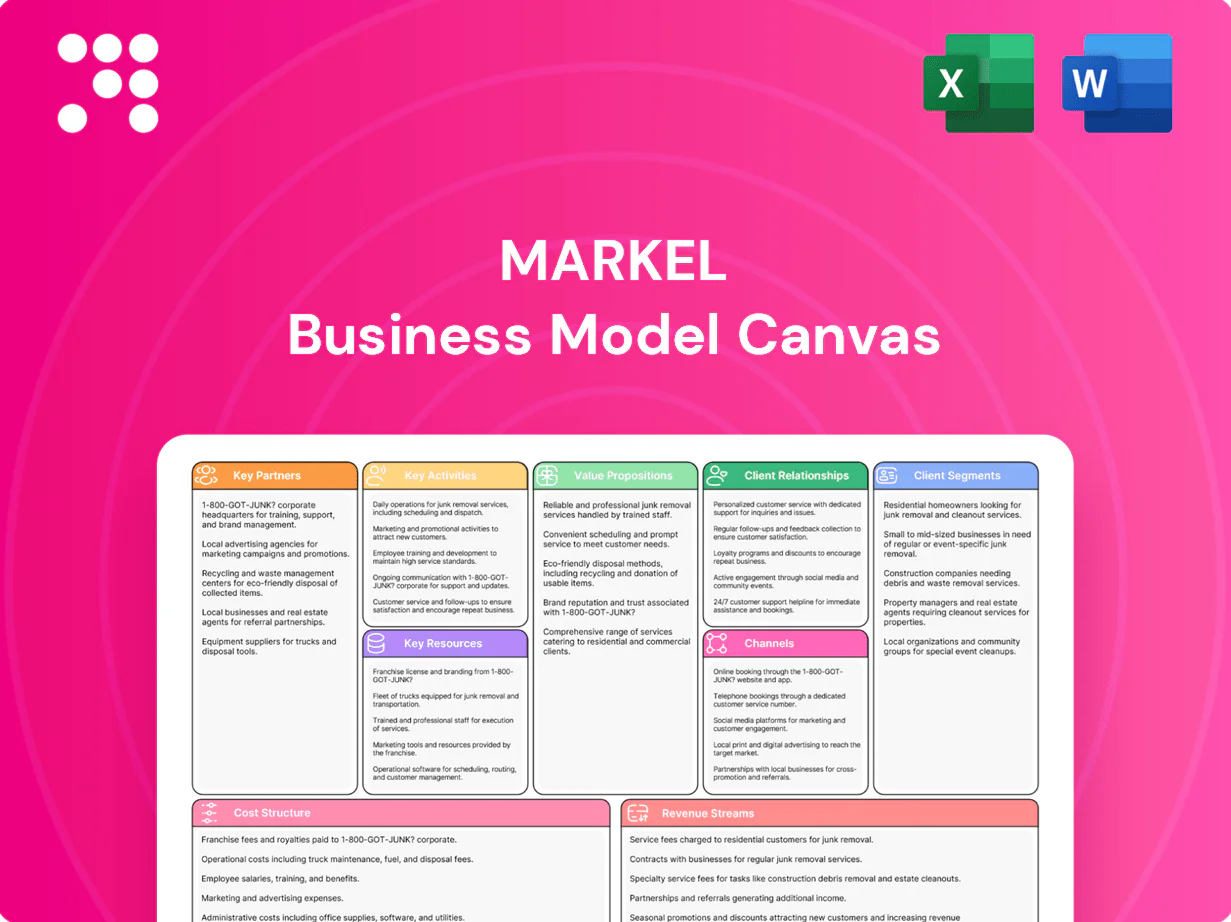
The document you're previewing is the actual Markel Business Model Canvas you will receive after purchase. It’s not a mockup—what you see is a direct extract from the final editable file. Upon buying, you'll download this same complete canvas, formatted and ready for editing, presenting, and sharing.
Markel’s robust balance sheet—shareholders’ equity about $9.8 billion and insurance float roughly $13.5 billion in 2024—supports long-term investing and portfolio flexibility. Liquidity and capital buffers underpin underwriting confidence, while conservative leverage (debt/equity ~0.2) preserves resilience in stress. Financial strength sustains S&P A+ ratings and counterparties’ trust.
Experienced underwriting and claims teams with deep sector expertise drive Markel’s selection advantage, enabling targeted risk acceptance and profitable growth across niche lines. Technical pricing and wording skills differentiate products and support margin resilience in shifting markets. Claims professionals focus on complex recoveries and subrogation to limit net loss and preserve capital. Institutional knowledge compounds through cycles, improving hit-ratio and loss control over time.
Markel, founded in 1930, leverages a long-established reputation in specialty markets and an A.M. Best A+ (Superior) rating to attract higher-quality submissions. Long-standing broker ties give access to profitable niches and support elevated renewal retention. Trust-based relationships help maintain rate adequacy, lowering acquisition friction and enhancing capital resilience.
Data, analytics, and models combine Markel proprietary exposure sets with third-party models (RMS, AIR) to inform pricing and aggregation; 2024 model updates refined hurricane and convective loss projections. Catastrophe, casualty severity, and frequency analytics set portfolio limits and reinsurance triggers. Tools enable scenario testing and stress analysis while data governance ensures reliability and compliance.
Markel Ventures, with over 60 operating subsidiaries as of 2024, supplies stable cash flows and real-economy insights that dampen insurance-cycle volatility; its businesses enable cross-selling and sourcing synergies while autonomy with centralized oversight preserves entrepreneurial drive.
Markel’s capital base (shareholders’ equity $9.8B; insurance float $13.5B in 2024) and conservative leverage (debt/equity ~0.2) enable long-term investing and underwriting flexibility. Deep underwriting/claims expertise and proprietary + RMS/AIR analytics drive disciplined pricing and loss control. Markel Ventures (60+ subsidiaries in 2024) supplies diversified, stable cash flows reducing cycle sensitivity.
| Metric | 2024 |
|---|---|
| Shareholders equity | $9.8B |
| Insurance float | $13.5B |
| Debt/Equity | ~0.2 |
| Ventures | 60+ subsidiaries |
Tailored specialty coverage addresses unique exposures overlooked by standard markets, with Markel emphasizing bespoke solutions in 2024 to serve niche risks. Flexible terms speed bind and reduce friction, enabling faster placement and client retention. Expert underwriting delivers right-sized limits and deductibles, aligning protection to operational realities and improving loss control. Clients gain bespoke protection matched to real-world exposures.
Markel's strong capitalization and A.M. Best A+ rating, supported by an investment portfolio of roughly $30 billion in 2024, underpins confidence that valid claims will be paid. Prudent reserving practices and extensive reinsurance programs materially stabilize underwriting outcomes. A long-term, patient capital approach sustains consistency through cycles. Customers and partners gain predictable, reliable risk-bearing capacity.
Specialist adjusters deliver fair, timely resolutions, reducing settlement times and preserving customer relationships in 2024. Clear communication minimizes policyholder downtime and uncertainty, improving retention. Litigation and recovery expertise enhance net outcomes by controlling loss costs. Claims insights from 2024 operations feed continuous improvement across underwriting and risk management.
Markel’s diversified earnings model—insurance underwriting, ~$31 billion invested assets in 2024, and operating subsidiaries—creates multiple profit engines that reduce reliance on any single revenue source and damp volatility, supporting steady compounding and cross-cycle resilience that benefits shareholders and counterparties; customers receive continuity of coverage and services even in stressed markets.
Markel’s partnership-driven model emphasizes long-term broker and client relationships that prioritize mutual success, reinforced by over 8,000 employees worldwide in 2024. Co-creation of products addresses emerging risks through tailored solutions, while transparent pricing and service foster trust and retention. Active renewal stewardship supports predictable coverage and improved loss-cost management.
Tailored specialty underwriting, expert claims service and partnership-driven product co-creation deliver bespoke protection and retention. Strong capital (≈$31B invested assets, 2024) and A.M. Best A+ rating provide reliable claims-paying capacity. Diversified earnings and active renewal stewardship stabilize results and support long-term relationships.
| Metric | 2024 |
|---|---|
| Invested assets | ≈$31B |
| Rating | A.M. Best A+ |
| Employees | ≈8,000+ |
Broker-centric engagement at Markel in 2024 features dedicated broker managers to streamline placement efficiency and pipeline health. Service standards and SLAs (targeting same-day acknowledgements and 48–72 hour placement decisions) drive responsiveness. Joint planning with top broker partners aligns appetite with market needs, while quarterly data sharing and performance dashboards improve underwriting and placement outcomes for all parties.
Large clients are assigned dedicated servicing teams that provide bespoke underwriting, claims advocacy and risk engineering; Markel (ticker MKL) reported in 2024 that specialty lines and large-account initiatives drove premium growth across its portfolio. Regular, quarterly reviews analyze loss trends, coverages and pricing to adjust terms proactively and reduce surprise losses. Multiyear strategies, often spanning 3–5 years, stabilize risk financing and improve capital planning. Executive access and board-level engagement reinforce commitment and trust, supporting retention rates above industry norms.
Risk engineering support at Markel centers on loss control services that reduce claim frequency and severity through targeted site surveys and analytics, with 2024 efforts focusing on converting survey insights into actionable improvements. Structured training and dissemination of best practices bolster client safety culture and operational resilience. Over time, sustained lower losses help secure more favorable underwriting terms and pricing for clients.
Digital self-service portals streamline submissions, endorsements and claims updates, and 2024 industry studies show average cycle-time reductions of about 25% and back-office cost savings near 30% from automation. APIs enable faster quoting with partners, often cutting turnaround times by half and increasing partner quote volumes. Document access via portals improves transparency and customer satisfaction while reducing inquiry-driven workload.
Proactive renewal outreach begins around 60 days before expiry to secure retentions and allow underwriting adjustments; NAIC data (2023) shows industry renewal rates near 85%, underscoring the value of early contact. Data-backed narratives justify pricing and terms, while targeted cross-sell uncovers 20–30% coverage gaps; consistent communication can lift retention by mid-single digits.
Broker-centric engagement and dedicated servicing teams drive faster placements and bespoke underwriting, with SLAs targeting same-day acknowledgements and 48–72 hour placement decisions. Digital portals and APIs cut cycle-times ~25% and processing costs ~30% (2024 studies), improving transparency and NPS. Proactive renewal outreach 60 days pre-expiry aligns with NAIC renewal context (~85% in 2023) to boost retention.
| Metric | Value | Source |
|---|---|---|
| Placement SLA | Same-day ack; 48–72h decision | Markel practices (2024) |
| Portal efficiency | -25% cycle-time (2024) | Industry studies 2024 |
| Back-office cost | -30% processing (2024) | Industry studies 2024 |
| Industry renewal rate | ~85% | NAIC 2023 |
Wholesale brokers are the primary route to complex, niche risks across geographies, aggregating demand and curating submissions to underwriters; market days and placement facilities accelerate deal flow. Relationship depth drives preferred access and faster terms; Markel (NYSE:MKL) had a market cap near $17bn in mid‑2024, underscoring scale and broker reliance for specialty placement.
Retail agents give Markel direct access to specialized SMEs and regional accounts, enabling targeted underwriting and local risk expertise in 2024. Training programs and appetite guides improved placement efficiency and policy fit. Co-branded marketing strengthens local presence and visibility. Performance-linked agent incentives align distribution with profitable growth.
Delegated underwriting via MGAs expands Markel’s reach efficiently, tapping niches—MGAs managed roughly $120 billion of global premium in 2024—bringing micro-segment expertise and underwriting speed. Performance dashboards drive governance with real-time KPI tracking, and capacity is flexed up or down based on MGA track record and loss ratios.
Selective direct relationships focus on top 150 enterprise and venture customers, with central teams coordinating cross-line opportunities and executive sponsorship unlocking strategic deals; CRM dashboards track pipeline and SLA performance (48-hour target) and showed a 32% increase in enterprise win rate in 2024.
Digital platforms and APIs enable submission, rating, and policy issuance embedded into partner systems for straight-through processing. API connectivity can shorten quote-to-bind time by about 40%, while richer data exchange (telematics, third-party feeds) improves pricing accuracy. Digital distribution scales quickly with lower fixed overhead, enabling broader partner reach.
Markel leverages wholesale brokers, retail agents, MGAs and direct enterprise relationships plus APIs to scale specialty distribution; MKL market cap ~17bn (mid‑2024). MGAs managed ~$120bn premium (2024); APIs cut quote‑to‑bind ~40%. Top accounts 150, SLA 48h, enterprise win‑rate +32% (2024).
| metric | value |
|---|---|
| MKL mkt cap (mid‑2024) | $17bn |
| MGAs premium (2024) | $120bn |
| quote→bind reduction | ~40% |
| top accounts / SLA / win‑rate | 150 / 48h / +32% |
Specialized small and mid-sized enterprises in marine, entertainment, hospitality and artisan trades require tailored terms and hands-on risk engineering to address unique exposures. These niche SMEs, part of the roughly 90% of global firms that drive local economies, demand reliability and rapid bind times. Markel leverages specialty underwriting to compress turnarounds and reduce loss frequency through focused engineering services.
Middle market and corporate clients demand bespoke programs and higher limits for complex risks, often requiring placements exceeding $10m per risk and involving multinational exposures or captive arrangements in 2024.
They prioritize stability, superior claims expertise and long-term capacity; Markel leverages specialist underwriting and a diversified capital base to serve these accounts.
These risks are frequently placed via top-tier brokers and account for a significant share of specialty commercial premium flows in 2024.
Primary insurers cede peak and specialty exposures to Markel for capacity, structuring insight and counterparty strength, often via multiyear treaties typically lasting 3–5 years; these relationships align incentives and support portfolio stability. Cedents require prompt settlement (commonly within 90 days) and transparent reporting to manage capital and loss recognition.
High-net-worth and specialty personal clients seek bespoke coverage for collections, events, and unique assets, valuing discretion and white-glove service; global HNWI population was about 23.1 million in 2024, underscoring market scale. Claims sensitivity is high, driving tailored endorsements and careful claims handling through select agents and brokers.
Markel Ventures serves manufacturers, service providers, and consumer-facing businesses, emphasizing quality, reliability, and value. Clients prioritize durable solutions and predictable service; cross-selling between ventures and Markel insurance can raise customer lifetime value. Stable industrial and services demand helps diversify revenue and reduce insurance cyclicality; the Ventures portfolio includes over 60 companies (2024).
Markel serves niche SMEs (≈90% of firms) needing tailored terms and fast binds, reducing loss frequency via risk engineering. Middle-market/corporate clients demand bespoke programs and limits often >$10m per risk. Cedents use multiyear treaties (3–5 yrs) for peak capacity and prompt settlement; HNWI market ~23.1M (2024). Ventures: >60 companies (2024), enabling cross-sell and revenue diversification.
| Segment | Key metric | 2024 data |
|---|---|---|
| SMEs | Share of firms | ≈90% |
| Middle market | Typical placement | >$10m |
| Cedents | Treaty length | 3–5 yrs |
| HNWI | Population | 23.1M |
| Ventures | Portfolio size | >60 companies |
Claims payments and loss adjustment expense represent Markel’s largest cost center, with the company stating in its 2024 Form 10-K that underwriting losses and LAE drive primary expense pressure; severity management and reserving accuracy are therefore critical to profitability. Catastrophe events remain the main source of volatility for Markel’s loss experience. Reinsurance reduces net exposure but increases ceded premium and capital cost, affecting margins.
Broker and MGA commissions align distribution incentives, typically accounting for 10–30% of premiums in 2024 industry analyses, directly linking producer payouts to new business volumes. Profit-sharing and sliding-scale arrangements in 2024 shifted underwriting margins by several percentage points depending on loss experience and tenure. Marketing and placement costs—often 2–6% of premium—support deal flow and lead generation. Efficient digital and captive channels reduced unit acquisition costs by up to ~30% in 2024 benchmarks.
Underwriting, claims, finance and compliance drive the bulk of Markel’s operating and administrative expense base, with targeted process automation programs focused on reducing cycle times and unit costs.
Ceded premiums and retrocession reduce Markel’s net earned premium, trading top-line growth for lower volatility; reinsurance spend is evaluated against the expected reduction in underwriting volatility and tail risk. Interest expense on issued debt directly lowers net income and guides capital allocation, so Markel balances borrowing costs with retained capital. Capital efficiency metrics drive structuring choices between reinsurance layers, retrocession, and debt financing.
Claims & LAE are Markel’s largest cost drivers; catastrophe volatility and reserving accuracy dominate profitability. Broker/MGA commissions run ~10–30% of premium; acquisition/marketing ~2–6%. Reinsurance ceded premiums lower net earned premium while raising capital cost; IT/cyber spend (IT $4.7T global, cyber $203B in 2024) supports underwriting edge.
| Metric | 2024 Value |
|---|---|
| Commissions | 10–30% premium |
| Marketing | 2–6% premium |
| Global IT spend | $4.7T |
| Cyber market | $203B |
Earned premiums are Markel’s core revenue, driven by specialty insurance and reinsurance lines; in 2024 Markel reported approximately $8.5 billion in premiums written, reflecting rate adequacy and exposure changes as primary growth levers. Strategic mix management—shifting toward higher-margin specialty products—helps optimize underwriting margins. Strong retention rates support compounding premium growth and long-term profitability.
Underwriting profit arises when the combined ratio is below 100, generating technical income; in 2024 Markel reported a combined ratio near 95% driving underwriting gains. Cycle management and strict selection discipline keep rate adequacy and reduce volatility. Reinsurance structures smooth results across years, and profit emerges only after disciplined loss and expense control are sustained.
Markel earns investment income from fixed income, equities and alternatives that yield on float and capital, with U.S. 10-year Treasury around 4.2% in 2024 and S&P 500 dividend yield near 1.6%. Duration and credit quality drive bond volatility and mark-to-market swings. Dividend and interest streams provide recurring cash flow. Asset allocation is actively shifted to shorter duration and selective credit as macro conditions change.
Markel Ventures generates operating income from its non-insurance subsidiaries, contributing measurable revenue and EBITDA to Markel Corporation in 2024 while providing cash flows that are relatively uncorrelated with underwriting cycles.
Earned premiums (~$8.5B written in 2024) and underwriting profit (combined ratio ~95% in 2024) are core revenues; specialty mix and retention drive margin. Investment income on ~$23B+ invested assets and float (U.S. 10Y ~4.2% in 2024) provides steady cash, while realized/unrealized gains create episodic spikes. Markel Ventures adds diversified operating income and EBITDA contributions.
| Metric | 2024 |
|---|---|
| Premiums written | $8.5B |
| Combined ratio | ~95% |
| Invested assets | $23B+ |
| U.S. 10Y yield | ~4.2% |


