
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
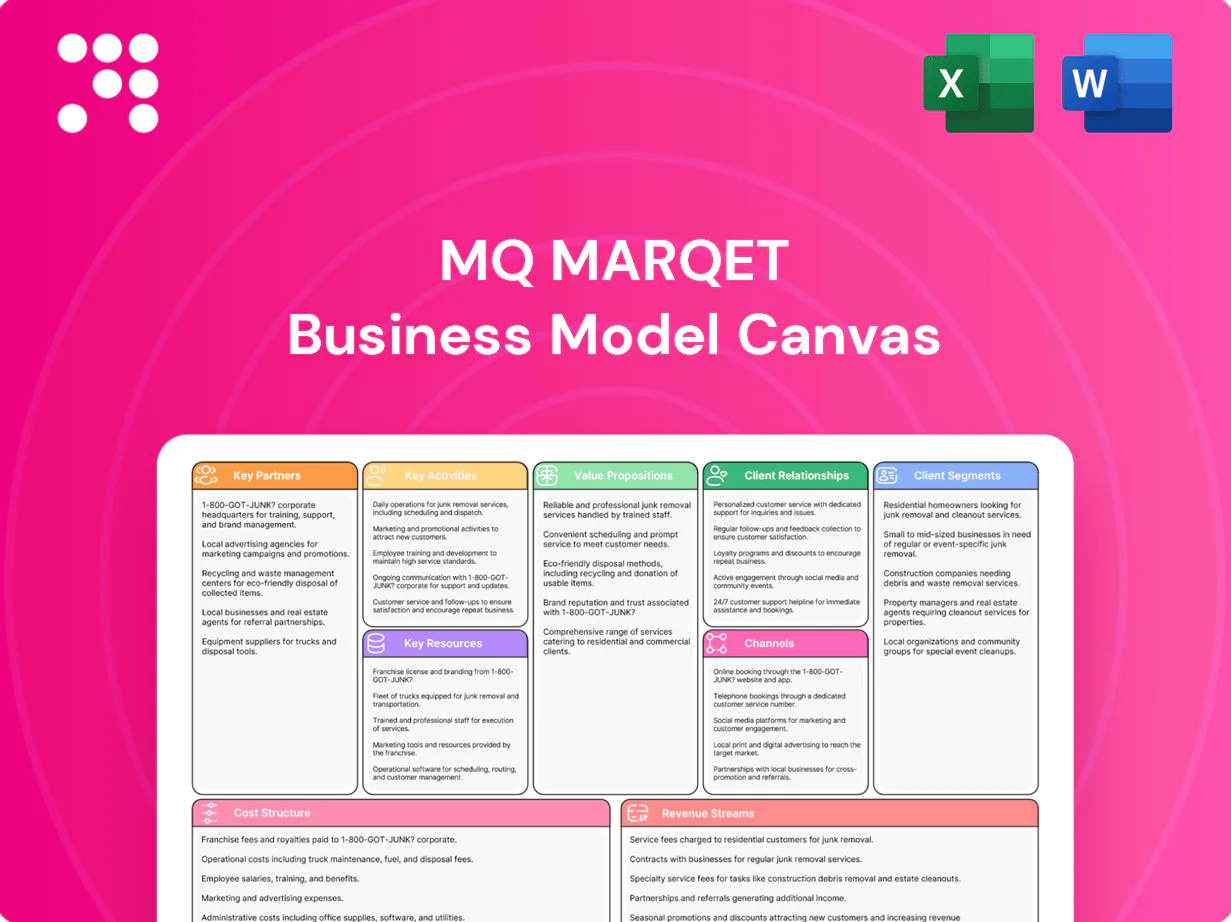
Unlock MQ Marqet’s strategic blueprint with our Business Model Canvas: a concise, actionable map of its value propositions, customer segments, partnerships, and revenue streams. Perfect for investors, founders, and consultants seeking competitive insight. Download the full Word & Excel canvas to benchmark, adapt, and scale proven tactics.
Partner with established Scandinavian and global fashion labels to secure curated assortments, tapping a global apparel market valued at about $1.9 trillion in 2024; prioritize reliable supply, seasonality alignment and exclusivity to protect margins. Negotiate full-price terms, firm delivery windows and collaborative merchandising to reduce stock markdowns and improve sell-through. Co-plan limited capsules and in-store brand corners to drive traffic and lift AOV.
Use national warehousing and last-mile partners for store replenishment and e-commerce fulfillment, targeting 24–48h lead times and streamlined click-and-collect flows; global e-commerce was ~22% of retail sales in 2024 and return rates averaged ~16%, so share demand forecasts to improve slotting and cut stockouts 5–10% and inventory 10–15%; leverage reverse logistics to trim return processing costs up to 30%.
Offer Swedish-preferred payments—Swish (≈8.5M users in 2024), Klarna (≈150M global users in 2024) and major cards (Visa, Mastercard)—with BNPL and frictionless online/in‑store checkout to cut cart abandonment 20–40%. Centralized payment routing, tokenization and risk scoring control fees and fraud, while unified receipts and cross‑channel refunds streamline reconciliation and boost repeat conversion.
Partner with POS, OMS and e-commerce stack vendors to ensure 24/7 reliability, real-time inventory and ship-from-store capabilities that support omnichannel demand; global e-commerce hit ~6.3 trillion USD in 2024, making uptime critical. Integrate personalization, CRM and analytics to boost conversion 10–30% and maintain scalable cloud infrastructure to handle 2–5x traffic spikes in peak seasons.
Collaborate with brands, influencers and shopping-centre teams on co-marketing to amplify reach and conversions; Sweden’s online retail share was about 20% in 2024 (SCB), so omnichannel push is critical. Drive local footfall via branded events and window campaigns timed to Black Friday, Christmas and Midsommar peaks. Leverage mall traffic insights and seasonal promotional data, aligning calendars with biannual Stockholm Fashion Week and retailer sale windows.
Secure curated assortments from Scandinavian/global labels to protect margins and drive exclusivity (global apparel market ~$1.9T in 2024). Use national warehousing, 24–48h last‑mile and reverse logistics to cut stockouts 5–10% and return costs up to 30% (global e‑commerce ~22% in 2024). Integrate Swish (~8.5M users), Klarna (~150M users) and POS/OMS (99.9% uptime, <30s inventory latency) for frictionless omnichannel conversion lifts of 10–30%.
| Metric | 2024 Value |
|---|---|
| Global apparel market | $1.9T |
| Global e‑commerce share | ~22% |
| Swish users | ~8.5M |
| Klarna users | ~150M |
| POS uptime / latency | 99.9% / <30s |
 Detailed Word Document
A concise, pre-built Business Model Canvas for MQ Marqet mapping customer segments, channels, value propositions, revenue streams and key activities with actionable narrative. Designed for presentations and investor discussions, it includes SWOT-linked insights and competitive advantages to support strategic decisions and validation using real-world company data.

 Customizable Excel Spreadsheet
Streamlines your strategy into an editable one-page canvas that quickly identifies core components and saves hours of formatting, making it ideal for boardrooms, teams, or teaching; shareable for fast collaboration and side-by-side comparisons.
Select a balanced mix of classic and contemporary styles across brands, targeting Sweden’s 10.5 million consumers and the 21% 2024 e‑commerce apparel share to capture omnichannel demand. Align buys to Swedish tastes and seasonality, prioritizing outerwear for Nov–Feb and light layers for Apr–Aug. Manage depth, size curves, and colorways to minimize markdowns and maintain <10% sell‑through variance. Continuously refresh newness while protecting core bestsellers.
Design store layouts and windows to showcase full-price stories, using focal displays that drove a measured 10% uplift in full-price conversion in 2024 retail benchmarks. Implement brand zones and outfit builds to lift AOV—outfit merchandising delivered an average AOV increase near 10% in 2024. Refresh displays weekly to sustain novelty and coordinate online imagery so e-commerce product pages mirror in-store narratives for omnichannel consistency.
Operate click-and-collect, reserve-in-store and ship-from-store workflows while syncing inventory across stores and e-commerce to cut stock-outs; omnichannel customers drive ~60% higher average order value (2024 retail benchmarks). Optimize order routing to reduce fulfillment cost by up to 15% and shorten lead times ~25%. Enable seamless cross-channel returns to retain repeat buyers and lower churn.
Deliver high-touch assistance via in-store associates and chat with fit guidance, alterations coordination and outfit advice; McKinsey 2024 notes personalization can lift revenue 15–20%, so capturing preferences for tailored follow-ups targets higher LTV. Train staff on brand narratives and product knowledge to convert engagement into sales, aiming for industry average conversion uplifts of 10–30% from guided service.
Forecast by category, brand and location from daily POS and historical sales; 2024 retail inventory turnover benchmark ~5.2x informs cadence. Adjust in-season with agile reorders and transfers to cut out-of-stock ~40%. Manage safety stock (≈10–20% of demand) and set sell-through targets of 75–85%. Govern end-of-season exits to protect full-price, capping markdown depth to ~25–35% and clearance assortments under 15%.
Curate balanced assortments (outerwear focus Nov–Feb) to Sweden's 10.5M consumers; target sell-through 75–85% and <10% size variance. Operate omnichannel fulfillment (click&collect, ship-from-store) reducing fulfillment cost ~15% and boosting AOV ~60%. Train staff for 15–20% revenue lift.
| Metric | 2024 |
|---|---|
| Population | 10.5M |
| E‑com apparel share | 21% |
The preview you see is the actual MQ Marqet Business Model Canvas—not a mockup—and is the same document you’ll receive after purchase. On completion, you’ll get the full, editable file exactly as shown, ready for presentation, editing, and sharing in Word and Excel formats.
MQ Marqet’s store network in Sweden anchors the brand through prime retail locations that act as showrooms, service hubs and mini‑fulfillment nodes supporting omnichannel fulfilment. Sweden population 10.5 million (2024) concentrates buying power in major metros such as Stockholm metro ~2.5 million. Local teams drive community, repeat visits, and window frontage/layouts boost in‑store discovery and impulse traffic.
Contracts and long-term brand portfolio rights secure access to sought-after labels, critical in a global apparel market valued at about 1.7 trillion USD in 2024 (Statista). Semi-exclusive agreements and limited-run assortments differentiate MQ Marqet, lifting sell‑through and margin potential. Co‑creation of capsule collections and guaranteed allocations lock inventory flow and timing with partners. Supplier trust is reinforced by consistent operational execution and on-time fulfillment metrics.
Omnichannel tech stack combines cloud POS, OMS, e-commerce platform, CRM and analytics to deliver real-time inventory and customer data for hyper-personalization; global e-commerce sales reached $5.7 trillion in 2023 (Statista). Integrations with payments, marketing automation and logistics enable end-to-end order flow and reduce manual reconciliation. Scalable, microservices architecture ensures elastic capacity for seasonal peaks like Black Friday/Cyber Weekend.
Merchandising talent combines buyers and planners skilled in trend spotting and financial rigor to drive performance in a $1.7 trillion global apparel market (2024); teams target full-price sell-through of 70–85% as an industry benchmark. Strong vendor negotiation and calendar management typically deliver 2–5% margin uplift, while a data-driven culture (analytics-led testing) guides SKU and cadence decisions.
Recognition as a curated multi-brand destination drives loyalty: repeat customers typically account for a material share of sales, while profiles capturing preferences and purchase history enable segmentation and targeted outreach that can boost conversion rates by double digits; trust is maintained through consistent service and quality, reflected in steady NPS and repeat-purchase metrics in 2024.
MQ Marqet’s Swedish store network (population 10.5M, Stockholm metro ~2.5M) plus omnichannel tech (real-time OMS/CRM) and supplier contracts secure inventory and margins; buyers target 70–85% sell-through and 2–5% vendor margin gains; loyalty and data lift conversion 10–30% with steady NPS in 2024.
| Resource | Metric | 2024 |
|---|---|---|
| Market | Apparel market | 1.7T USD |
| Population | Sweden | 10.5M |
| Sell-through | Target | 70–85% |
| Vendor gains | Margin uplift | 2–5% |
| Conversion | Lift | 10–30% |
Handpicked mix combining timeless staples and on-trend pieces, featuring over 50 curated labels to ensure consistent quality and fit. Saves customers hours versus browsing fragmented marketplaces, improving conversion and lowering search costs. Weekly refreshes keep the assortment exciting and drive higher repeat visits.
Full-price retail experience emphasizes premium presentation, high-touch service, and product integrity, avoiding over-discounting that erodes brand equity. Bain 2024 reports global personal luxury goods near €380bn, with many brands preserving margins through disciplined pricing. Customers access new-season launches at launch price, and consistent pricing builds trust and repeat purchase behavior.
Expert styling support offers personal assistance for outfits, occasions and capsule wardrobes, reducing purchase risk—industry online apparel return rates remain around 20–30% in 2024—by providing better fit guidance. Personalization and styling lift average order value; McKinsey estimates personalization can increase revenues by up to 10–15%. Elevated confidence boosts satisfaction and repeat purchases, encouraging higher basket sizes.
Seamless omnichannel journey: shop in-store or online with a unified cart and service; click-and-collect and easy returns boost convenience and conversion. Real-time stock visibility reduces friction and supports BOPIS operations. Consistent service across touchpoints drives loyalty; 2024 Salesforce reports 84% of customers expect seamless cross-channel experiences.
Curated 50+ labels boost conversion and protect margins in a €380bn luxury market
Handpicked mix of 50+ curated labels ensures quality and fit, saving hours vs fragmented marketplaces and boosting conversion. Full-price premium presentation preserves margins in a €380bn personal luxury market (Bain 2024). Styling personalization lifts revenue 10–15% and cuts fit returns (online apparel 20–30% in 2024). Omnichannel convenience drives loyalty; 84% expect seamless cross-channel experiences (Salesforce 2024).
| Metric | Value | Source |
|---|---|---|
| Labels | 50+ | MQ Marqet |
| Luxury market | €380bn | Bain 2024 |
| Personalization lift | 10–15% | McKinsey 2024 |
| Online returns | 20–30% | Industry 2024 |
| Cross-channel expectation | 84% | Salesforce 2024 |
Use CRM data to tailor recommendations and outreach, leveraging 2024 Salesforce data that 84% of customers expect personalized experiences. Remember sizes, brands, and style preferences in profiles to increase conversion and loyalty. Send proactive alerts for new drops and limited releases. Prioritize regular, high-touch engagement to build long-term rapport with key clients.
MQ Marqet's loyalty program uses tiered benefits, early-access drops, and exclusive event invites to drive repeat purchases without heavy discounting; a 2024 industry report found 72% of consumers belong to at least one loyalty program. Points and perks redeemable both online and in-store increase omnichannel spend, while tracking engagement and A/B testing offers refines conversion—small retention lifts can disproportionately boost profitability.
Responsive handling of returns, exchanges, and alterations reduces friction—industry online apparel return rates averaged about 20% in 2024, so streamlined processes cut cost and volume. Care advice (stitching, washing, storage) extends garment life and lowers repeat returns. Fast resolutions increase repurchase intent and build trust; feedback loops from service interactions inform assortment improvements and SKU rationalization.
Host product launches, styling sessions and brand pop-ups in-mall and with influencer partnerships to drive footfall and experiential engagement; capture leads with sign-ups and SMS opt-ins during events. In 2024 influencer marketing spend exceeded 20 billion USD, boosting event reach and conversion.
Leverage CRM to personalize outreach (84% expect personalization in 2024), remember sizes/brands to boost conversion, and send product-drop alerts. Tiered loyalty (72% join programs in 2024) and omnichannel redemptions drive repeat spend. Streamline returns (apparel ~20% return rate 2024) and fast service (CSAT target 85%, NPS 40) to build trust and reduce churn.
| Metric | 2024 Value/Target |
|---|---|
| Personalization expectation | 84% |
| Loyalty membership | 72% |
| Apparel return rate | 20% |
| Influencer spend | >20B USD |
| CSAT / NPS targets | 85% / 40 |
Physical retail stores are the primary channel for discovery, try-on, and service, with in-store purchases still representing about 77% of global retail sales in 2024. High-impact visual merchandising boosts conversion (in-store conversion ~10–20% vs online ~2–3%) and supports click-and-collect and returns, with BOPIS raising AOV by roughly 20% in 2024. Local marketing and ads influence an estimated ~40% of store visits, driving footfall.
E-commerce website: a 24/7 catalog with real-time stock serves as the central hub, supporting omnichannel campaigns and driving sales in a market that reached about $6.3 trillion in global online sales in 2024; rich content and fit tools boost conversion (average global ecommerce conversion ~2.5% in 2024) while integrated payments and multi-carrier delivery options reduce checkout friction and increase AOV.
Social media fuels inspiration, new arrivals and quick style edits, converting visual content into discovery: 55% of Gen Z report discovering brands on social platforms (2024). It drives in-store and site traffic through shoppable posts and links, and supports influencer collaborations within a $21.1 billion global influencer market (2023). Platforms enable rapid feedback loops on trend uptake via real-time engagement metrics.
Email and SMS power lifecycle messaging and segmented campaigns—2024 benchmarks show email open rates ~21.5% (Mailchimp) and SMS open rates ~98% within minutes, driving high-engagement back-in-stock and drop alerts and early-access pushes that lift repeat purchases; combined channels convert with low cost per contact (email ≈ $0.01–$0.05, SMS ≈ $0.02–$0.04 depending on provider).
Selective marketplace presence extends reach when brand alignment exists; marketplaces accounted for ~60% of global e-commerce GMV in 2024 and Amazon held ~38% of US online retail sales in 2023. Use them to test demand in micro-segments while enforcing strict controls to protect full-price positioning and funnel discovery back to owned channels.
Omnichannel mix drives discovery and conversion: physical stores (77% of retail sales 2024) with 10–20% conversion and BOPIS +20% AOV, plus e-commerce ($6.3T global 2024) with ~2–3% conversion. Social and influencer channels fuel discovery (55% Gen Z discover on social 2024; influencer market $21.1B 2023). Lifecycle email/SMS (open 21.5%/98% 2024) and selective marketplaces (60% e‑commerce GMV 2024) complete the funnel.
| Channel | Key metric | 2024 stat |
|---|---|---|
| Stores | Sales share / conv | 77% / 10–20% |
| E‑commerce | GMV / conv | $6.3T / 2–3% |
| Social | Discovery | 55% Gen Z |
| Email/SMS | Open rates | 21.5% / 98% |
| Marketplaces | GMV share | 60% |
Urban professionals—men and women—seek polished everyday and workwear prioritizing fit, quality, and modern classics; they shop both in-store and online. In 2024 the global apparel market was about $1.7 trillion, with e-commerce representing roughly 30% of sales in developed markets. This segment shows a higher willingness to pay full price for durable, well-fitting pieces, driving premium ASPs and repeat purchases.
Trend-aware shoppers seek curated newness, following social media and seasonal drops for discovery; in 2024, about 45% of fashion consumers report following brands on social platforms. They favor events and limited capsules that create urgency and exclusivity. Highly responsive to styling content, these customers convert quickly when livestreams, shoppable posts, and influencer drops align with trends.
Occasion buyers shop primarily for events and travel, seeking complete outfits rather than single items and valuing fast, service-oriented experiences. 2024 research highlights growing demand for curated outfit guidance and styling services to reduce decision time and return rates. These shoppers are highly time-sensitive and frequently convert to add-on accessory purchases when presented with cohesive recommendations.
Gift purchasers buy for partners, family, and friends and often seek curated suggestions and easy returns to reduce gifting risk; in 2024 retailers reported rising demand for clearer size/style guidance. Seasonal peaks concentrate around holidays and special occasions, driving inventory and staffing needs. Gift cards remain a high-demand option in 2024 for flexibility and last-minute purchases.
In 2024 loyal local customers—regulars within 1–3 km—drive high repeat rates, often 60–75% of purchases in neighborhood grocers. They rely on associates for curated picks and generate about 30% of new customers via referrals. Active community engagement (events, loyalty nights) increases basket size by 8–12%.
Urban professionals prioritize fit/quality; 2024 apparel market ~$1.7T with e-commerce ~30% in developed markets; premium ASPs and repeat purchase rates high. Trend-aware shoppers (~45% follow brands on social) convert via drops and shoppable content. Occasion and gift buyers seek curated outfits and easy returns; holiday peaks drive volumes. Local loyal customers (within 1–3 km) show 60–75% repeat rates and +8–12% spend from events.
| Segment | Key metric | 2024 stat |
|---|---|---|
| Urban professionals | E‑commerce share | ~30% |
| Trend-aware | Follow brands | ~45% |
| Occasion/Gift | Gift card demand & returns | Seasonal peaks |
| Local loyal | Repeat rate / event lift | 60–75% / +8–12% |
Wholesale purchases from brand partners drive COGS, typically 55–70% of revenue in specialty retail in 2024, and include import duties (commonly 5–12%), freight (2–4% of sales) and handling. Currency volatility in 2024 moved costs by roughly ±3–8% versus local currency, and vendor terms (30–120 days) affect landed cost. MQ Marqet manages this via assortment optimization and dynamic pricing to protect margins.
Store operations drive fixed and variable costs: national retail asking rent averaged about $25–35 per sq ft in 2024, plus utilities and maintenance (~2–4% of sales). Staffing and visual merchandising account for ~10–12% of sales, with seasonal temps adding 10–20% more labor hours during peaks. Security and shrink mitigation remain material—US retail shrink ~1.8% of sales in 2024—requiring spend on fixtures and loss-prevention systems.
Warehousing, transport and last-mile make up the lion’s share of logistics costs, with last-mile accounting for up to 53% of total shipping cost; warehousing and materials add incremental per-order spend (packaging typically 2–5% of order value). Reverse logistics drives returns costs — e‑commerce average return rate ~16.6% — while SLA-related surcharges during peak windows can add roughly 10–25% to per-shipment fees.
Marketing and promotions consume 18–22% of MQ Marqet revenue in 2024, funding brand campaigns (digital CPMs $3–10), influencer deals (micro $250–1,000/post; macro $5k–50k), events and local mall co-marketing fees ($5k–30k per activation), plus CRM/email/SMS platforms (SaaS $50–500/month) and content production/photography ($1k–10k per shoot).
Technology and overhead for MQ Marqet include recurring POS, OMS, e-commerce and CRM subscriptions (mid‑market stacks commonly range $2k–15k/month in 2024), plus development and integrations often requiring one‑time projects of $50k–200k. Corporate staff and compliance drive ongoing payroll and audit costs (typically 15–25% of operating expense in 2024). Payment processing averages ~2.9% per transaction in 2024, and merchants spend ~0.5–1% of revenue on fraud prevention.
MQ Marqet COGS 55–70% of revenue in 2024; duties 5–12%, freight 2–4%. Rent $25–35/sqft; staffing 10–12% of sales; shrink 1.8%. Last‑mile ~53% of shipping; e‑commerce returns 16.6%. Marketing 18–22% of revenue; tech stacks $2k–15k/mo; payment fees ~2.9%.
| Metric | 2024 |
|---|---|
| COGS | 55–70% |
| Rent | $25–35/sqft |
| Returns | 16.6% |
| Marketing | 18–22% |
Primary revenue derives from full-price men’s and women’s apparel, driven by focused assortments and new-season arrivals. The model preserves margin integrity through selective pricing and limited promotional drainage. Sales are amplified by curated storytelling across product launches and in-store experiences.
Footwear and accessories — bags, shoes, belts, small leather goods — act as high-margin complements that frequently convert as impulse or add-on purchases at checkout, lifting AOV by roughly 12–18% in fashion retail cohorts. The global footwear market was valued near $445 billion in 2024 (Statista), highlighting scale and upsell potential. Prioritizing premium leather SKUs and curated bundles can push gross margins above apparel averages and improve overall basket value.
Omnichannel services—click-and-collect, ship-from-store and tiered express delivery fees—drive conversion by meeting immediate fulfillment needs and supporting in-store inventory velocity. Omnichannel shoppers spend up to three times more than single-channel customers, so value-added convenience builds loyalty. MQ Marqet subsidizes select services to boost conversion while charging for premium express options and occasional paid alterations coordination.
Private label capsules deliver 3–4 SKU co-created lines with 15–25% higher gross margins versus branded SKUs, filling assortment gaps and meeting exclusivity needs; in 2024 private label comprised ~18% of global CPG retail sales, supporting margin capture. Controlled distribution limits channel dilution and strengthens MQ Marqet differentiation.
Primary revenue is full‑price apparel with tight promotions; footwear & accessories add 12–18% AOV uplift and tap a $445B footwear market (2024). Omnichannel services boost spend up to 3x for omnichannel shoppers; premium fees subsidized to drive conversion. Private label yields 15–25% higher gross margins and accounts for ~18% CPG share; gift cards (> $400B market 2024) provide upfront cash and breakage.
| Revenue Stream | 2024 Metric | Margin Impact | Notes |
|---|---|---|---|
| Apparel | Core sales | Baseline | Selective pricing |
| Footwear & accessories | $445B market | +12–18% AOV | High-margin upsell |
| Omnichannel | 3x spend | Variable | Paid express/subsidized |
| Private label | ~18% CPG | +15–25% | Exclusive SKUs |
| Gift cards | >$400B market | Upfront cash | Breakage & cross-sell |


