
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
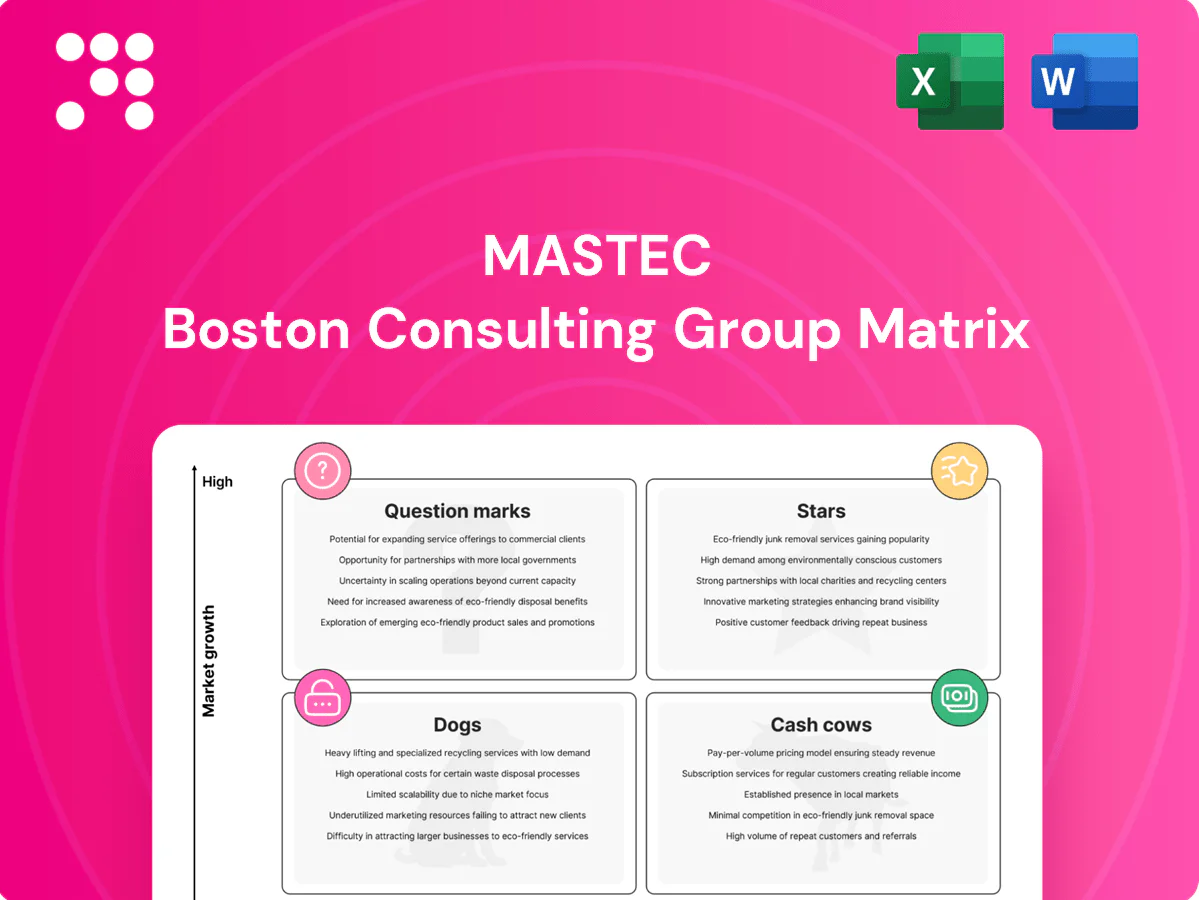
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where MasTec's products land—Stars, Cash Cows, Dogs, or Question Marks? This snapshot teases the story; the full BCG Matrix gives you quadrant-by-quadrant placement, hard data, and clear strategic moves you can act on. Purchase the complete report for a Word write-up plus an Excel summary that’s presentation-ready and editable. Skip the guesswork—get the full analysis and start allocating capital smarter, faster.
MasTec (MTZ) crews are heavily booked on dense 5G and fiber rollouts, where growth remains strong and the company holds chunky share; communications work helped drive MasTec to roughly $8.6 billion in 2023 revenue and a multi‑billion‑dollar backlog entering 2024. These projects consume cash for crews, permits and rapid mobilization but generate large topline inflows; steady execution can let them mature into cash cows. Invest to remain the prime on multi‑market awards.
Utilities are racing to upgrade transmission and distribution under programs such as the IIJA, which allocated $65 billion for grid modernization, and MasTec’s power delivery unit sits in the lead pack. High spend, high pace and repeat utility customers reflect classic star behavior. The work is capital- and labor-intensive, with heavy equipment and skilled crews driving margins. Stay embedded in multiyear utility programs to defend share as the cycle extends.
Clean energy is scaling rapidly—U.S. interconnection queues exceed 1,000 GW (EIA 2024)—and MasTec’s engineering and utility-scale build bench positions it to design, build and connect large projects. Pricing pressure persists, but deep backlog and fast execution sustain share; cash turns quickly in peak build seasons then resets. Continue investing in equipment, interconnect expertise and QA to outpace rivals.
EV charging and grid tie‑ins sit in Stars for MasTec: public and fleet charging networks are expanding rapidly, and MasTec straddles civil, electric, and telecom execution layers, making it well positioned. These projects are growthy, permit‑heavy and coordination‑intense, consuming cash today but with potential to convert to durable service and O&M revenue streams. Federal NEVI funding (5 billion USD) plus state incentives and accelerating fleet electrification are near‑term tailwinds; market leadership now can secure long‑term annuities.
Undergrounding and distribution hardening are scaling across storm‑prone regions, and MasTec’s national scale, strong safety record, and trenching expertise give it a clear execution edge; projects ramp quickly and require sustained field spend to meet demand. Winning multi‑year frameworks now converts bursty work into steadier, margin‑rich backlog as growth normalizes.
MasTec’s Stars (5G/fiber, transmission, clean energy, EV charging) drive high growth and strong share, producing $8.6B revenue in 2023 and a multi‑billion backlog into 2024. Projects are capex‑ and crew‑intensive but convert to cash with steady execution. Policy tailwinds: IIJA $65B grid funds, NEVI $5B, interconnection queues >1,000 GW (EIA 2024).
| Metric | Value |
|---|---|
| 2023 Revenue | $8.6B |
| Backlog (entering 2024) | Multi‑billion |
| IIJA grid funds | $65B |
| NEVI | $5B |
| Interconnection queues | >1,000 GW (EIA 2024) |
 Detailed Word Document
BCG Matrix analysis of MasTec's units—Stars, Cash Cows, Question Marks, Dogs—with clear invest, hold or divest guidance and trend context.

 Customizable Excel Spreadsheet
One-page MasTec BCG Matrix placing each business unit in a quadrant to cut debate, clarify priorities and speed C-level decisions.
Utility maintenance & term contracts are MasTec’s cash cow: recurring inspect‑repair‑replace programs and master service agreements (MasTec, NYSE: MTZ) deliver steady cash with low bid volatility and keep crews highly utilized. Backlog remained above $10B in 2024, growth is modest but operating margins improved as routing tech and tighter crew productivity lifted yields; milk via scheduling tech and strict cost control.
Even with muted new builds, existing oil and gas lines need mandated integrity work: PHMSA requires integrity assessments in high-consequence areas at least every 5 years. With over 2.7 million miles of US pipelines, demand is predictable, scheduleable, and repeat — classic cash cow. MasTec’s safety performance and digitized records reduce client risk and support premium utilization; efficiency gains widen contribution without heavy capex.
Outside and inside plant upkeep for telecom carriers provides steady tickets and quick turns, forming MasTec's network maintenance cash cow. Low growth but high recurrence and strong utilization drive predictable margins — MasTec reported roughly $10.8 billion revenue in 2024, with field services supporting mid‑teen operating margins industrywide. Cross‑trained crews maintain SLAs, minimize truck rolls and bank the cash.
Brownfield substation refreshes are steady, funded, and process‑driven; MasTec’s brownfield substation work is margin‑accretive when engineered right, with repeatable sequencing that minimizes outage hours and avoids costly rework.
MasTec’s repeatable playbook shortens outages and cuts rework through standardized kits and prefabs, improving labor productivity and cash conversion on routine substation refreshes.
Keep standardizing kits and prefabs to squeeze more cash flow: reduced field hours, fewer change orders, and faster turnover preserve margins on high‑certainty backlog projects.
When storms hit MasTec mobilizes rapidly and invoices promptly under established rate schedules; episodic demand converts to predictable cash flow across the year. Growth is secondary — readiness and utilization drive margins and free cash; fleets, crews and pre-negotiated rates turn emergency calls into clean, near-immediate revenue. Maintain assets and rostering to maximize billable hours and minimize outage-to-bill cycles.
MasTec’s cash cows are utility maintenance, pipeline integrity, telecom/network upkeep, brownfield substations and storm response—recurring, funded work with predictable schedules, high crew utilization and margin resilience. 2024 revenue was about $10.8B with backlog >$10B; pipeline integrity demand is steady and inspect/repair cycles drive repeatable cash conversion.
| Metric | 2024 / note |
|---|---|
| Revenue | $10.8B |
| Backlog | >$10B |
| US pipeline miles | 2.7M |
| Field services margin | mid‑teens |
| Utilization | high |
The file you're previewing is the exact MasTec BCG Matrix you'll receive after purchase—no watermarks, no demo placeholders, just the finished, fully formatted report. This preview equals the downloadable product, crafted for clear strategic insight and immediate use. Buy once and unlock the editable, print-ready document for presentations, planning, or client work. No surprises—what you see is what you get.
Greenfield oil pipeline mega‑projects in MasTec's BCG matrix suffer permitting drag and heightened public opposition, with 2024 project timelines routinely stretching beyond initial schedules and bid costs remaining on the books while work waits. Low growth in oil midstream demand has sapped returns, turning even won contracts into margin traps as execution complexity rises. Best to limit exposure to niche, hard‑to‑deliver one‑offs that concentrate risk and capital.
Legacy copper telecom builds are structurally declining as fiber wins: FTTH connections topped roughly 600 million globally by end-2023 (FTTH Council), shrinking long‑term copper demand. Copper awards are now low‑share, price‑driven contracts that compress margins and trap crews in low‑value tasks. De‑prioritize copper except when work is tightly bundled with higher‑value fiber or utility scopes to protect throughput and margin.
Coal‑adjacent civil work sits in Dogs: end‑market demand has collapsed as US coal capacity is down about 40% since 2010 and retirements accelerated through 2024, ESG screening tightened across lenders and insurers, and utility capex is being reallocated. Projects often only break even post‑mobilization and compliance; capital and brand risk now outweigh returns. Exit or let legacy contracts sunset.
Tiny, non-core regional jobs tie up crews and gear on MasTec projects, turning small stand-alone civil tasks into net drains; MasTec reported roughly $11.0B revenue in 2024, so marginal low-value work dilutes corporate efficiency.
Admin overhead on these pockets often erodes any margin; with low growth and low share they offer little strategic value and should be culled to free capacity for higher-return segments.
One‑off specialty fabrication sits in Dogs: custom fab lacks scale and consistent backlog, driving frequent cost overruns and margin erosion for MasTec’s nonrepeat work.
Pricing is highly variable and hard to standardize; cash becomes trapped in extended WIP with thin recovery on many jobs, increasing working capital days.
Recommendation: trim to strategic, repeatable SKUs and redeploy capacity to scalable utility and telecom projects to restore margins and shorten cash conversion.
Dogs: low‑growth, low‑share pockets (greenfield oil pipeline delays, legacy copper, coal‑adjacent civil, tiny regional jobs, one‑off fabrication) drain margins and cash; MasTec reported ~$11.0B revenue in 2024 so these dilute core efficiency. Cull tail, redeploy crews to scalable fiber/utility, and limit bespoke fab to repeatable SKUs to restore margins.
| Segment | 2024 metric | Action |
|---|---|---|
| Pipelines | Delays↑, bids on books | Limit exposure |
| Copper | FTTH ~600M (end‑2023) | De‑prioritize |
Hydrogen infrastructure sits as a Question Mark: growth narrative strong given policy support but projects remain early and sporadic; DOE awarded up to 7 billion for regional clean hydrogen hubs (2023–24). MasTec’s pipeline and power skillset align well, yet market share is not established and projects are cash hungry with uncertain take‑rates. Invest selectively where offtake agreements and policy incentives are locked to de‑risk capital.
Carbon capture transport & storage sits in Question Marks: strong policy push (US/EU incentives expanded 2022–24) but economics still forming; global commercial CO2 capture ~40 Mt/yr (Global CCS Institute, 2023). MasTec has the right engineering skills and scale (MasTec FY2023 revenue $9.1bn) but low awarded share so far and high engineering intensity; slow FIDs burn cash. Recommend option-style, partner-backed bets rather than balance-sheet exposure.
Microgrids and distributed energy are question marks for MasTec as commercial and municipal buyers are testing but not scaling evenly; the global microgrid market was about $13.5 billion in 2023 with a ~13% CAGR projected to 2030. MasTec can design‑build systems, yet standards and financing vary by jurisdiction and customer credit. With maturing procurement and IRA-era incentives, deployments could tip into a star; pursue anchor clients to build repeatable programs.
Enterprises and utilities demand private LTE/5G and edge but purchase decisions lag while vendors jostle; MasTec’s execution strength aligns with comms projects, though commercial share is still emerging and pilots often cost cash before revenue materializes; 2024 market activity shows pilots outnumber rollouts, favoring contractors that can scale multi‑site wins.
Question Marks: Offshore wind balance‑of‑plant (US) — big upside given the US federal 30 GW by 2030 target, but near‑term permitting and supply‑chain volatility keep projects choppy; MasTec’s onshore grid, civil and marine capex execution skills translate well, yet commercial scope capture remains early and capex/learning‑curve intensity is high, so prioritize partnerships, selective bidding and scaling only after award stability.
Hydrogen: DOE hubs $7bn (2023–24), big growth but early; CCS: global capture ~40 Mt/yr (2023) with incentives rising; Microgrids: $13.5bn market (2023), ~13% CAGR to 2030; Private LTE/5G pilots rising; Offshore: US 30 GW by 2030 target. MasTec (FY2023 rev $9.1bn) has execution edge but low share—advise selective, partner‑backed bids and offtake‑de‑risking.
| Segment | 2023/24 metric | MasTec position | Recommendation |
|---|---|---|---|
| Hydrogen | DOE $7bn | Skills align | Selective, offtake-backed |
| CCS | 40 Mt/yr | Engineering fit | Partnered options |
| Microgrids | $13.5bn | Design-build capability | Anchor clients |
| Private LTE/5G | 2024 pilots↑ | Execution DNA | Scale multi-site wins |
| Offshore | 30 GW by 2030 | Translatable skills | Partner, selective bids |


