
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Mattr Infratech faces moderate supplier power, rising competitive rivalry, and barriers that limit new entrants, while substitute threats and buyer leverage vary by segment. This snapshot highlights key pressures shaping margins and growth potential. Unlock the full Porter's Five Forces Analysis to explore force-by-force ratings, visuals, and actionable strategy tailored to Mattr Infratech.
High-spec valves, sensors and power electronics are often supplied by a handful of OEMs, concentrating leverage and enabling tougher payment terms such as net 60–90 days and price-escalation clauses; for energy projects this supplier dominance is estimated to cover 40–60% of critical-component sourcing. For a young firm like Mattr Infratech, dual-qualifying parts can add 6–12 months and raise procurement costs by 10–15%, while typical lead times of 20–40 weeks amplify dependence.
Steel, copper, specialty alloys and logistics can swing materially—suppliers often pass cost rises through quickly, with metals volatility commonly moving double digits year-on-year; index-linked contracts protect margins but are typically scarcer for newer firms. Inventory buffers tie up roughly 3–6 months of working capital for a 2023-founded firm. Hedging programs and VAVE initiatives can partially offset exposure, often covering 30–60% of price risk.
Utilities and oil & gas clients commonly mandate supplier-specific certifications and type approvals, creating design lock-in that raises switching costs; requalification processes often add 3–12 months to schedules and can increase procurement costs materially. Suppliers thus gain bargaining power as validated designs concentrate spend; building multi-vendor BOMs early can cut lock-in and preserve competitive sourcing.
Imported advanced monitoring, control systems and niche equipment often depend on foreign IP; export controls tightened in 2023–24 and FX swings raise landed costs, increasing supplier leverage. Licensing royalties commonly run 3–7% and localization typically requires volume or CAPEX commitments (often US$1–10m), which buyers can use to negotiate. Well-structured technology transfer agreements can shift up to half of long-term bargaining power back to the buyer.
When sector demand spikes, suppliers prioritize larger, long-term customers, so Mattr Infratech as a newer player may face lower allocation or expedited fees, which in 2024 market episodes rose roughly 10–20% for fast-tracked orders.
Supplier power is high: 40–60% of critical components from few OEMs, lead times 20–40 weeks, dual-qualification adds 6–12 months and +10–15% cost. Metals volatility moves double digits; inventory ties 3–6 months WC; hedging covers 30–60%. Export controls (2023–24) and licensing (3–7%) raise landed costs; localization CAPEX US$1–10m; expedited fees rose 10–20% in 2024.
| Metric | Value |
|---|---|
| Critical-component concentration | 40–60% |
| Lead times | 20–40 weeks |
| Dual-qualify impact | +6–12 months / +10–15% |
| Inventory WC | 3–6 months |
| Hedging coverage | 30–60% |
| Licensing fees | 3–7% |
| Localization CAPEX | US$1–10m |
| Expedited fees (2024) | +10–20% |
 Detailed Word Document
Uncovers key drivers of competition, customer influence, and market entry risks tailored to Mattr Infratech, evaluating supplier and buyer power, substitutes, competitive rivalry and barriers to entry to identify strategic threats, disruptive forces and actionable opportunities.

 Customizable Excel Spreadsheet
A concise one-sheet Porter's Five Forces for Mattr Infratech—quickly pinpoint competitive pressures and strategic levers to relieve analysis bottlenecks. Editable pressure levels and an instant radar chart make scenario testing and board-ready slides effortless.
Indian utilities, EPCs and energy majors run competitive RFPs with stringent SLAs—large public tenders and merchant auctions have driven solar/wind tariff declines of roughly 20–30% over the last decade, intensifying price pressure on suppliers. Their professional procurement and scale enable demands for customization without premium pricing, though relationship capital and proven on‑time delivery can progressively reduce that squeeze.
Open bidding in infrastructure tenders standardizes specs and compresses margins by intensifying comparability, with L1 award norms prevailing in the majority (>70%) of public tenders in 2024 and often overweighting price over lifecycle value. Early-stage spec-in and lifecycle costing can shift procurement focus toward total cost of ownership, softening margin pressure. Offering alternate bids that highlight TCO and O&M savings preserves margin and improves award prospects against price-only L1 benchmarks.
For commoditized SKUs buyers can switch suppliers with minimal risk when approvals exist, eroding differentiation and increasing buyer leverage; 2024 surveys show service and uptime now drive purchasing for over 50% of infrastructure buyers. Demonstrable reliability data, extended warranties and sub‑24h service response materially raise exit costs. Bundling maintenance and analytics with hardware further embeds customers and reduces churn.
Performance-linked payments with common 5% retention and typical liquidated damages of 0.5%/week (cap ~5%) shift certification and delivery risk to vendors, increasing willingness to concede when cash flow tightens; strong project management and digital traceability speed certifications, and test-backed performance guarantees can justify better commercial terms.
Demand cyclicality and public budget timing drive Mattr Infratech order cadence; India’s FY2024–25 capital expenditure target of 10 lakh crore INR concentrates public tender timing, lengthening lead times in slow cycles when buyers squeeze margins, while demand surges push clients to prioritize speed over price; a diversified end‑market mix reduces single‑buyer leverage and framework contracts improve volume visibility and pricing stability.
Buyers wield strong leverage: >70% public tenders in 2024 use L1 price awards, tariffs fell ~20–30% decade-to-date, and service now drives >50% of purchases; retention 5% and LD 0.5%/wk (cap ~5%) shift risk to vendors. Capex clustering (India FY2024–25 target 10 lakh crore INR) creates timing-driven squeeze; diversification, TCO bids and bundled O&M raise switching costs and protect margins.
| Metric | 2024 Value |
|---|---|
| L1 tenders | >70% |
| Tariff decline | 20–30% (10y) |
| Retention | 5% |
| LD | 0.5%/wk, cap ~5% |
| Service importance | >50% |
| FY24–25 Capex | 10 lakh crore INR |
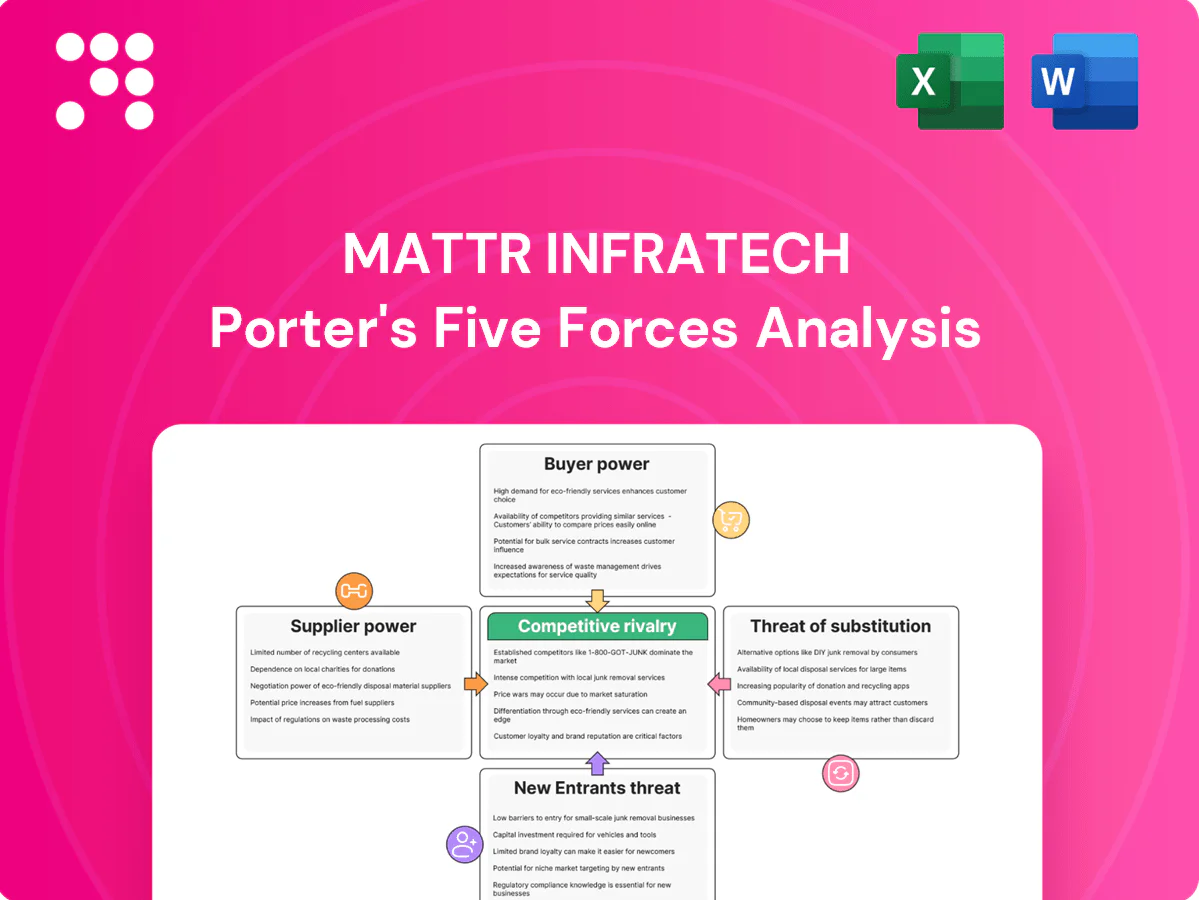
This preview shows the exact Mattr Infratech Porter’s Five Forces analysis you’ll receive immediately after purchase—fully formatted, complete and ready to use. No placeholders or mockups: the file displayed is the final deliverable available for instant download once payment is complete. Use it as-is for reporting, decision-making, or integration into your presentations.
Domestic EPCs such as Larsen & Toubro, Tata Projects and Sterlite Power, together with global OEMs like Siemens Energy, GE Renewable Energy and Vestas, intensify rivalry for Mattr Infratech as 2024 project pipelines favor proven suppliers. Brand trust and long-duration service contracts—often 10–15 years—create high switching costs and protect installed bases. Newer firms must outcompete on agility, lower LCOE or niche specialization to win share. Pilot project wins and documented case studies remain decisive for credibility.
Standardized mid-tier products trigger heavy discounting by regional manufacturers—2024 industry surveys report about 60% of bidders offer discounts up to 10%, compressing gross margins to single digits and creating a race to the bottom unless firms differentiate. Lean operations and modular designs allow competitive pricing while preserving quality; bundling value-added services (maintenance, financing) shifts competition from upfront price to lifetime value.
In energy infrastructure, downtime costs dominate so rivalry centers on SLA adherence, spares availability and MTBF (industry MTBF targets often exceed 100,000 hours). Benchmark SLAs at 99.95% uptime (~4.38 hours annual downtime) make rapid-response and remote monitoring investments decisive. Transparent KPI reporting (uptime, MTTR, spare-parts fill rates) materially improves renewal and expansion prospects.
Project sites are widely dispersed, and rivals with national footprints often cut response times to under 24 hours in priority regions, pressuring Mattr Infratech to match coverage. Local warehousing and dedicated field engineers typically reduce mean time to repair by 20–30%, lowering downtime and contract penalties. Strategic spares hubs in key states lift competitiveness by improving parts availability, while alliances with regional service partners can expand reach rapidly and at lower capex.
Intense rivalry from L&T, Tata Projects and global OEMs pushes Mattr Infratech to differentiate via lower LCOE, SLA performance and tech-enabled services; 2024 pipelines favor proven suppliers. Price compression is real—~60% bidders offer discounts up to 10%—so bundling maintenance/financing preserves margins. IoT market >$700B (2024); predictive maintenance can cut downtime ~50% and costs 20–30%, making tech parity essential.
| Metric | Benchmark (2024) | Impact |
|---|---|---|
| Bid discounts | ~60% bidders ≤10% | Gross margin compression |
| SLA | 99.95% uptime (~4.38h/yr) | Penalty risk, renewal driver |
| IoT market | >$700B | Enables predictive maintenance |
| Predictive maintenance | −50% downtime; −20–30% costs | Reduces MTTR, improves retention |
Shifts from conventional to renewables—with global renewable capacity additions exceeding 500 GW in 2024 and battery pack costs near $100/kWh—are changing required equipment from heavy mechanical to power-electronics and storage-centric systems. Legacy transformers and switchgear risk displacement by inverters, converters and batteries. Firms pivoting portfolios and offering hybrid plus grid-integration solutions reduce substitution exposure.
Advanced diagnostics and remote monitoring cut routine field visits, with industry case studies reporting on-site reductions of 30–40% where predictive maintenance is deployed; this directly threatens traditional service revenue. Client preference is shifting toward software subscriptions—global SaaS revenue reached about USD 226 billion in 2024 (Statista)—encouraging substitution of service contracts. Building a SaaS-like layer preserves recurring revenue and customer stickiness, but training client teams can lower billable hours unless services are repriced to reflect higher advisory/value offerings.
Cheaper imported components frequently undercut local offerings in price-sensitive tenders, while quality perceptions of some imports have notably improved in recent years. Compliance, certified warranties and after-sales guarantees often restore buyer confidence and limit gray-market substitution. Government localization incentives, notably Production Linked Incentive schemes amounting to about 1.97 trillion INR, tilt procurement toward domestic suppliers.
Equipment-as-a-service is displacing outright purchases as 2024 industry surveys show over 40% of industrial buyers prefer opex models, shifting vendor selection from price to service, uptime and financing flexibility. Vendors that partner with financiers retain value-chain roles by offering leasing; performance guarantees and SLAs have become decisive—contracts increasingly tie payment to measured output and availability.
Renewables added >500 GW in 2024 and battery packs ≈$100/kWh, shifting demand to inverters, converters and storage and risking legacy transformer/switchgear substitution. Predictive maintenance cuts onsite visits 30–40% (case studies) and SaaS revenue reached USD 226bn in 2024, pressuring service contracts. >40% buyers prefer opex models (2024), so leasing, SLAs and PLI incentives (≈1.97tn INR) shape substitution risk.
| Metric | 2024 value |
|---|---|
| Renewable additions | >500 GW |
| Battery pack cost | ≈$100/kWh |
| SaaS revenue | USD 226bn |
| Opex-first buyers | >40% |
| PLI incentives | ≈1.97tn INR |
| Predictive maintenance impact | 30–40% onsite reduction |
Basic fabrication and assembly for Mattr Infratech-style components can be achieved with moderate capital (~$0.5–2.0M), but obtaining industry certifications (ISO 9001, IEC) and credible references typically takes 6–18 months. Mission-critical energy projects demand higher trust, pushing sales cycles to 12–24 months and pilot-to-contract conversion rates often under 20% in 2024. Reputation thus functions as a de facto barrier to entry.
Grid, safety and industry approvals for Mattr Infratech are extensive: type tests and audits commonly add 6–18 months to market entry and cost roughly $50k–$300k (industry 2024 estimates). Established QA systems and accredited in‑house labs can cut approval timelines by ~30–50%, lowering friction for incumbents. These compliance costs and delays deter casual entrants and raise the effective capital barrier to entry.
Skilled engineers, welders, and project managers are scarce at peak demand; a 2024 industry survey found 64% of contractors reporting critical shortages, lengthening schedules. New entrants struggle to secure preferred supplier status with key OEMs, driving initial cost overruns often in the 10–20% range. Entrants without vendor networks face onboarding delays; employer brand and training pipelines are decisive differentiators.
Utilities and oil & gas clients heavily favor known vendors and LSTK partners, with long-term framework agreements typically channeling repeat work to incumbents, raising barriers for new entrants. Breaking in requires aggressive warranties, gap pricing, or niche technology wins to offset client risk aversion. JV or consortium strategies materially shorten procurement timelines and improve trust signals for newcomers.
Policy tailwinds such as Make in India and the approved Production Linked Incentive (PLI) schemes (total outlay ₹1.97 lakh crore across 14 sectors) plus India’s $1.4 trillion National Infrastructure Pipeline lower entry barriers and may attract new infra players, especially in construction tech and component manufacturing. Incentives, however, favor large-scale, local-capacity commitments that incumbents with scale and supply chains exploit, muting net entry; niche segments with unmet demand remain most accessible.
Moderate capital ($0.5–2.0M) and certifications (6–18m) lower but do not eliminate entry costs; pilot-to-contract rates <20% in 2024. Approval costs $50k–300k and talent shortages (64% contractors reporting) raise effective barriers. Frameworks, warranties and JVs are primary routes to entry; PLI ₹1.97 lakh crore and NIP $1.4tn favor scaled incumbents.
| Metric | 2024 value |
|---|---|
| Capex to start | $0.5–2.0M |
| Pilot→contract | <20% |
| Approval cost | $50k–300k |
| Talent shortage | 64% |


