
Digital download
Access the files immediately after checkout.
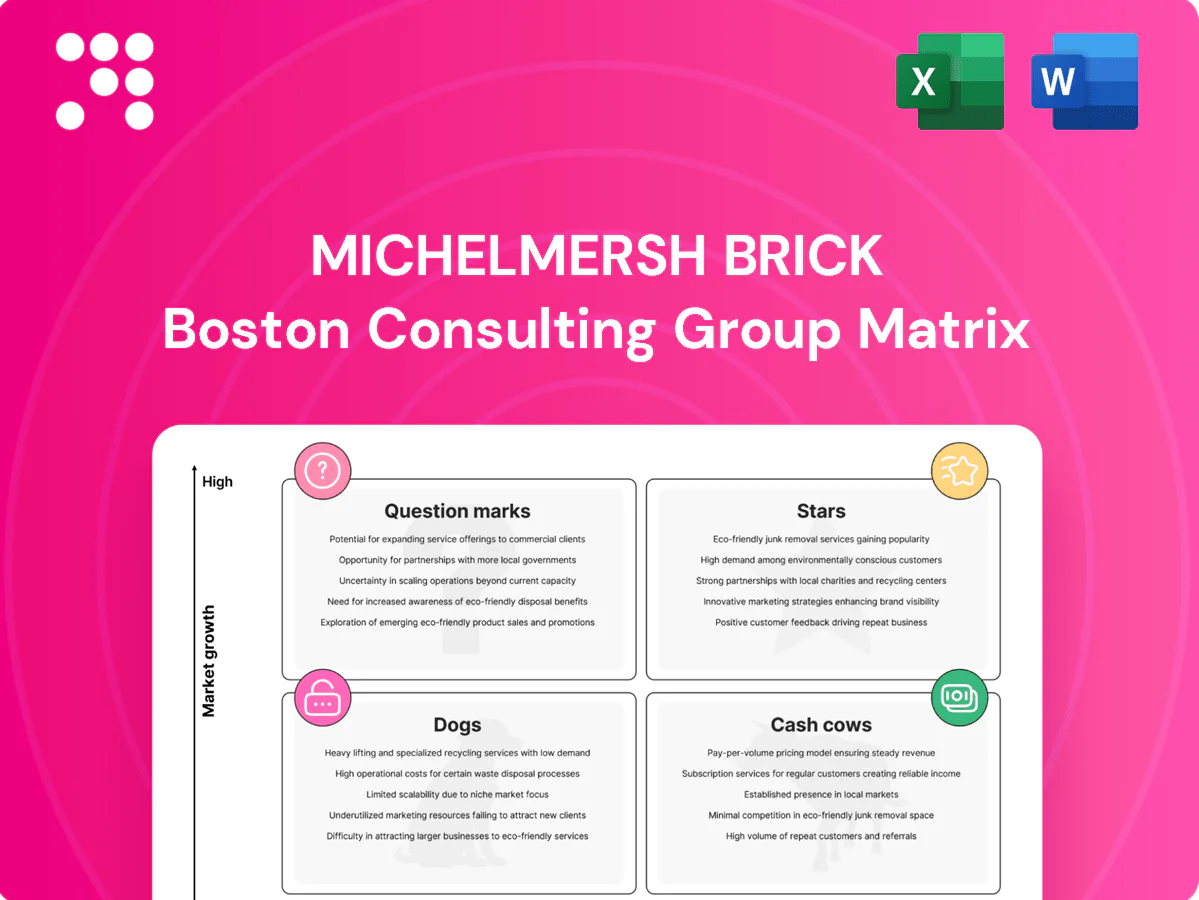
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
The Michelmersh Brick BCG Matrix preview gives you a quick snapshot of which product lines lead, which fund the business, and which might be weighing it down — but it’s only the tip of the iceberg. Buy the full BCG Matrix to get quadrant-level placements, data-driven recommendations, and a ready-to-use Word report plus an Excel summary you can present straight away. Skip the guesswork: this is the fast route to smarter allocation, clearer strategy, and practical moves you can act on now.
Premium handmade & heritage bricks hold a high market share in UK conservation and restoration projects, with strong brand pull among architects and specifiers. Demand is rising as conservation grants and high-end residential refurb programmes recover. Market leadership requires continued heavy spec selling, sampling and architect engagement to convert momentum. Ongoing investment in marketing and technical support is needed to defend and grow share.
Design-led commercial and mixed-use is a bright spot and Michelmersh, listed on AIM, sits on many flagship shortlists thanks to strong aesthetics, consistent quality and wide palettes. Winning specs relies on ongoing CPD and BIM (UK BIM Level 2 mandate from 2016) plus dedicated project support, which increases upfront cost. The investment protects the project pipeline and compounds into future cash as specified schemes move from design to delivery.
Regulation and client pressure are accelerating demand for low‑embodied‑carbon materials as buildings and construction account for about 38% of global energy‑related CO2 emissions. Michelmersh’s early, credible sustainability narrative and EPD-led positioning give it star potential in 2024. Growth is strong — low‑carbon building materials are forecast to grow at ~8% CAGR — but capex and certification (EPDs, product testing) keep cash flows tight. Keep investing: scale will turn this into tomorrow’s cash cow.
Specifiers increasingly start online and Michelmersh Brick’s digital library converts attention into specifications; MBH reported a 28% YoY rise in BIM object downloads in 2024, with usage climbing each project cycle and repeat access rates above 40%.
Michelmersh, a UK brickmaker, positions premium clay pavers as Stars in its BCG matrix: urban regeneration and placemaking demand is rising, and clay pavers deliver superior durability and aesthetics with typical service lives of 60+ years, fitting the brand sweet spot. Tenders require technical support and large sample runs, tying up working capital. Keep investment steady to cement leadership.
Premium heritage bricks and clay pavers are Stars: strong UK spec share in conservation and design-led commercial projects, buoyed by AIM-listed Michelmersh’s brand pull. 2024 momentum: 28% YoY BIM downloads and 40%+ repeat access; low‑carbon materials forecast ~8% CAGR. Continued investment in spec selling, samples and certification ties up working capital but protects a high-value project pipeline.
| Metric | Value (2024) |
|---|---|
| BIM downloads YoY | 28% |
| Repeat access | 40%+ |
| Low‑carbon materials CAGR | ~8% |
| Building sector CO2 share | ~38% |
| Clay paver life | 60+ years |
 Detailed Word Document
In-depth BCG analysis of Michelmersh Brick's portfolio, identifying Stars, Cash Cows, Question Marks and Dogs with strategic recommendations.

 Customizable Excel Spreadsheet
One-page Michelmersh Brick BCG Matrix placing each business unit in a quadrant for instant strategic clarity.
Core wirecut facing bricks sit in a large, mature market where Michelmersh holds a defensible premium slice and stable 2024 trading underlined resilient demand. Plants run efficiently with repeat SKUs driving volume and healthy gross margins versus group averages in 2024. Promotional needs remain modest versus Stars—milk the line, trim waste and prioritize reinvestment in kiln efficiency to protect cash generation.
Restoration specials and matching services deliver steady orders from listed buildings, councils and heritage architects, with Michelmersh reporting group revenue of £62.0m in FY 2024 and restoration work forming a stable recurring slice. Skilled craftsmanship commands premium pricing and strong client loyalty, supporting higher margins than commodity bricks. Growth is low but repeat business is predictable and cash generative, underpinning operating cash flow. Priority actions: shorten lead times and protect skilled labour capacity.
Standard formats sold through merchant networks benefit from established distribution and long-running relationships; Michelmersh reported group revenue of c.£71m in FY2023–24, keeping volumes stable into 2024. Demand from repair and smaller residential projects remains steady, limiting marketing needs to presence and reliability. Cash flows fund R&D and selective growth bets, supporting product development and capacity upgrades.
Clay roof tiles and slips complement brick orders, driving incremental revenue with decent margins in aesthetic-led projects; as of 2024 clay tiles commonly exceed 80–100 year lifespans, underpinning a mature market and dependable replacement cycles. Promotional intensity remains low beyond catalogs and samples; keep throughput smooth and bundle tile SKUs into brick project offers to maximize sell-through.
Core wirecut facing bricks sit in a mature market with resilient 2024 demand; Michelmersh reports restoration revenue £62.0m in FY2024 and standard formats c.£71m in FY2023–24, supporting higher gross margins than group averages and steady operating cash generation. Export premium ranges and clay tiles add niche, low-marketing cash streams; focus on kiln efficiency, lead-time reduction and skilled labour retention to protect cash flows.
| Segment | FY2024 rev | Margin/notes |
|---|---|---|
| Restoration | £62.0m | Premium pricing, repeat orders |
| Standard formats | c.£71m (FY23–24) | Stable volume, funding R&D |
| Export & tiles | Small but steady | Low promo, protect service |
The file you're previewing is the exact Michelmersh Brick BCG Matrix you'll receive after purchase. No watermarks, no demo pages—just the fully formatted, analysis-ready report. It’s crafted for clarity and strategic use, ready to edit, print, or present. After payment the full document is delivered instantly—no surprises, no revisions needed.
Commodity low‑end bricks sit in a near‑zero growth segment (≈0–1% in 2024) with brutal price competition, and MBH (LSE: MBH) lacks the scale to win on cost. Working capital becomes trapped for thin returns as margins compress. Historic turnarounds in low‑end plants rarely pay back. Minimise exposure and concentrate investment on premium ranges where the Michelmersh brand commands higher spreads.
Slow‑moving odd formats tie up kilns and inventory for one‑off jobs, killing throughput and raising per‑unit costs. Sales from these skews barely cover handling and storage, functioning as a cash trap for the business. Rationalize the catalog to remove low‑demand items and push close substitutes to free kiln capacity and working capital.
Legacy SKUs without spec demand sit idle unless architects or merchants request them, collecting dust and inspection costs. They divert commercial and manufacturing attention from higher-velocity lines that drive margin and cash flow. Typically they only break even, if that, after allocated overhead; sunseting them and redirecting capacity to core SKUs improves throughput and reduces unit cost.
Non-core accessories are small-ticket, fiddly items where reported e-commerce return rates rose to about 18% in 2024, eroding margins as quality disputes drive after-sales costs that often exceed per-item revenue.
The construction accessories segment shows flat demand with sub-1% annual growth in mature UK brick markets, offering little brand uplift for Michelmersh; recommendation: cull SKUs or outsource fulfilment and warranty handling to cut service burden.
Geographies with high freight and low repeat drain margin as long hauls erode price and repeat rates rarely justify the lane; margin volatility is constant and cash sits in transit, so Michelmersh should exit these lanes or tighten radius to profitable clusters.
Commodity low‑end bricks sit in a ≈0–1% growth UK market (2024) with severe price competition; MBH lacks scale so margins compress and WC is trapped. E‑commerce return rate ~18% (2024) for accessories, driving service costs above per‑item revenue. Recommendation: cull SKUs, outsource low‑margin accessories, and exit long‑haul lanes.
| Metric | 2024 | Recommended Action |
|---|---|---|
| Market growth | 0–1% | Deprioritise |
| Return rate | 18% | Outsource/cull |
| ROIC on dogs | ≈0–negative | Sunset/exit |
Specialist, design-led terra cotta/faience is seeing renewed demand on restorations and statement facades, supported by a UK heritage restoration market estimated at c.£3bn annually in 2024; MBH has craftsmanship credibility but faience remains under 5% of group revenue in 2024, so share is small. High engineering hours and lumpy project revenue make it a classic Question Mark: invest in capacity and partnerships to scale or keep it boutique and selective.
Brick slips for MMC/offsite facades are well positioned as MMC expands—global modular construction was ~USD 140bn in 2024 with ~7% CAGR, and lightweight systems increasingly demand thin, durable slips. The market remains fragmented with no clear leader, so scaling requires automation and tight QA to hit >95% yield targets. Michelmersh should deploy pilot lines and secure anchor customers to push this product into Star territory.
Ultra‑low‑carbon bricks sit in Question Marks: strong UK policy tailwinds (net zero by 2050, CCUS cluster support) clash with hefty tech and capex, leaving returns thin until scale and carbon/credits materialise. Early demonstration wins could reset market expectations and unlock industrial grants and partnerships. Prioritise grants, alliances and staged deployment to derisk; pause if payback metrics weaken.
Glazed bricks are a Question Mark: specifiers prize the aesthetic but demand is niche and sporadic, limiting predictable volume; MBH can leverage premium quality and expanded color range to capture design-led projects.
Setup costs per run are high (often tens of thousands of pounds), so the recommended approach is pilot SKUs, secure hero projects to build case studies, then scale and standardize best-sellers.
Direct-to-architect digital sampling addresses a 2024 shift toward on-demand, trackable samples; MBH has the digital backbone and a pilot showing early conversion signals (pilot spec conversion ~12% in 2024) but acquisition costs are high per lead, pushing CAC above acceptable thresholds for volume. If conversion to repeat specs sustains, the data loop creates a flywheel; otherwise kill fast to preserve margin.
Specialist faience sees renewed demand from a UK heritage restoration market c.£3bn in 2024; faience <5% of MBH revenue, high hours and lumpy projects. Brick slips tie to MMC (global modular ~USD140bn in 2024, ~7% CAGR) but need automation. Ultra‑low‑carbon bricks have policy tailwinds yet high capex; pilot conversion ~12% (2024) for D2A sampling—scale if repeat LTV:CAC justifies.
| Product | 2024 market | MBH share | key metric | rec. |
|---|---|---|---|---|
| Faience | UK heritage £3bn | <5% | High setup | Pilot/selective |
| Brick slips | Modular USD140bn | Small | Automation need | Pilot lines |
| Low‑C bricks | Policy tailwinds | None | High capex | Grants/alliances |


