
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
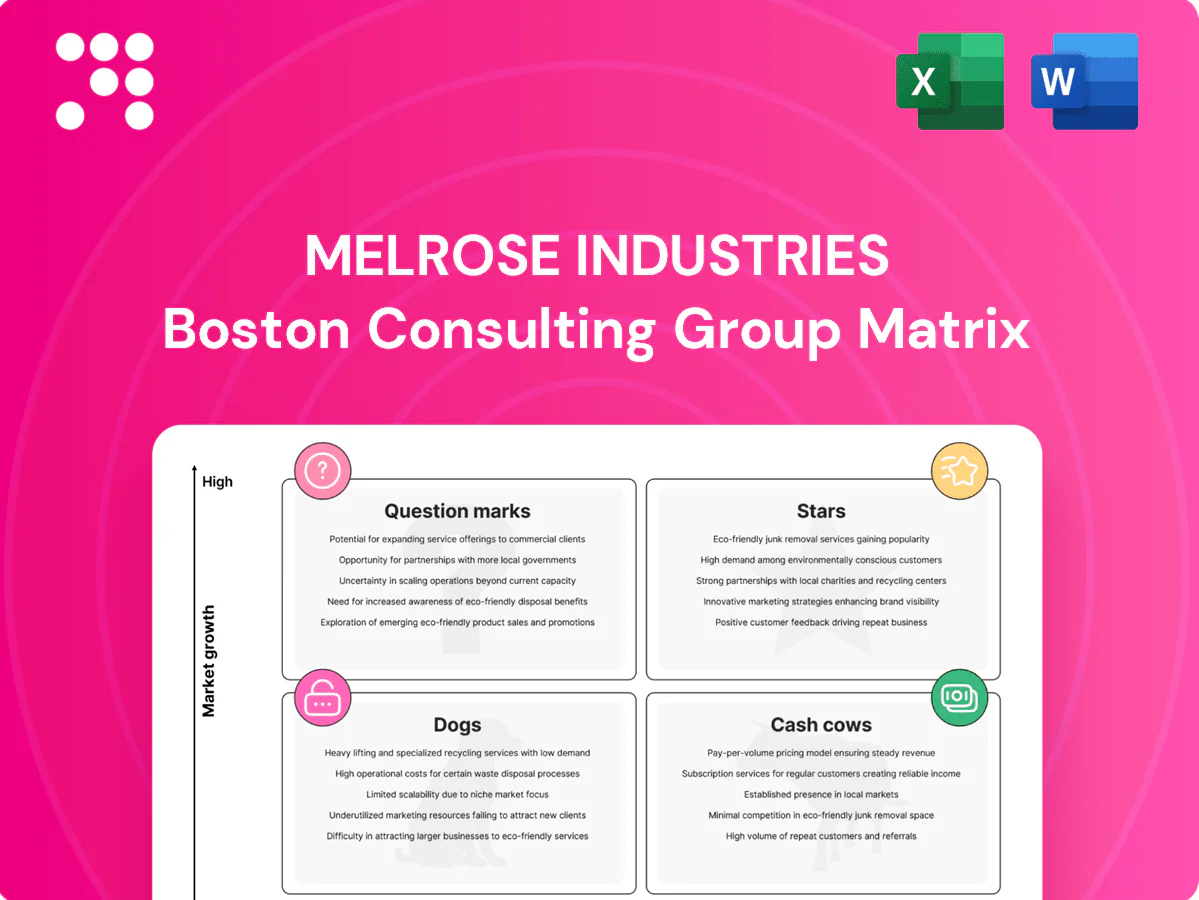
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Quick snapshot: Melrose Industries’ BCG Matrix teases which divisions are driving growth, which are funding the balance sheet, and which need a rethink—think Stars, Cash Cows, Dogs, and Question Marks. This preview points you in the right direction; the full report maps each business with data-backed quadrant placements and strategic moves you can act on. Buy the complete BCG Matrix for a ready-to-use Word report plus an Excel summary that makes board-ready recommendations simple. Purchase now and cut through the noise with clear, strategic clarity.
These Stars are high-growth, high-share units in markets Melrose has reshaped via its buy-improve-sell model; they already lead their categories but require heavy promotion, talent recruitment, and capex to scale.
For now cash-in equals cash-out as ongoing investment supports momentum; management guidance prioritises holding share and reinvesting to sustain growth.
If execution continues, these businesses are expected to mature into cash cows once scale and operational improvements lower incremental investment needs.
Category leaders sit in expanding end‑markets where Melrose’s playbook has unlocked clear cost and quality edges, winning bids, setting pricing tone and pulling growing backlog; they remain hungry for expanded sales coverage and capacity. In 2024 these businesses are focused on converting growth heat into durable cash flow through sustained operational leverage and targeted investment.
Melrose moved first on acquisitions such as the 2018 GKN takeover for £8.1bn, using rapid restructuring to outpace rivals and create an operational gap that functions as a strategic moat.
That agility has driven high growth trajectories and rising market share, supporting reinvestment in the flywheel; continued funding is essential until market margins normalize.
Monopoly‑like service positions are aftermarket or IP‑anchored slots with limited substitution tied to installed‑base growth; they require capital to secure coverage and uptime guarantees, and revenues scale with market expansion rather than price hikes. They absorb investment for service networks and SLAs, but once share is protected they convert into high‑margin cash cows. Protect share relentlessly—today’s star is tomorrow’s cow.
In 2024 Melrose's exit‑ready growth engines drew strategic interest as buyers targeted units dominating fast‑growing niches; marketing and channel placement remained central to locking customer adoption and scaling margins. Valuation accretes with each quarter of execution, so timing exits to capture peak multiples without starving growth is critical for maximising proceeds.
Stars are high‑growth, high‑share units requiring sustained capex and talent to convert momentum into durable cash flow. Cash‑in ≈ cash‑out as management reinvests to defend share and scale margins. Execution should drive transition to cash cows; timing exits to capture peak multiples is critical. Melrose’s 2018 GKN takeover was £8.1bn, underpinning the stars’ market positions.
| Metric | Value |
|---|---|
| Key acquisition | GKN takeover £8.1bn (2018) |
| 2024 priority | Reinvest to hold share & convert growth |
 Detailed Word Document
In-depth BCG analysis of Melrose Industries' units, defining Stars, Cash Cows, Question Marks and Dogs with clear investment recommendations.

 Customizable Excel Spreadsheet
One-page Melrose BCG matrix placing each unit in a quadrant for quick portfolio decisions.
Mature, high‑share units (Cash Cows) in Melrose sustain steady end‑markets with entrenched positions and low unit volatility in FY2024. Margins are strong after past turnarounds, supporting consistent free cash flow generation in FY2024. Modest promotional spend and maintenance capex keep operations running efficiently. Milk the cash to fund new turnaround investments and cover corporate overheads.
Melrose's stable aftermarket revenues stem from a large global installed base across its GKN aerospace and driveline businesses, delivering predictable spares and service flows with low growth but high repeatability. Conversion to cash is excellent, driven by long-term service contracts and renewals that minimize promotional spend and support strong operating cash conversion. Focus on optimizing working capital lets aftermarket operations consistently throw off funds for reinvestment and debt reduction.
Lean platforms post‑restructuring show a reset cost base and optimized footprint, with processes standardised across sites; Melrose reported pro forma FY 2024 revenue c.£6.7bn and an adjusted operating margin near 9%, underlining dependable profitability rather than rapid top‑line growth. Incremental automation has raised yields, delivering annualised efficiency gains in the low‑hundreds of millions of pounds and enabling harvest of savings to reinvest in higher‑growth pockets. Management is reallocating cash from these cash cows to fund targeted M&A and capex in growth segments.
Long‑term service contracts provide Melrose with locked‑in customer commitments and indexed pricing, delivering muted growth but high revenue visibility; once tooling and teams are established these contracts become capex light and reliably cash generative. Surplus cash from these contracts can be redeployed to de‑risk the portfolio through debt reduction, targeted M&A or share buybacks, supporting overall group resilience.
Divest‑and‑distribute cash cows in Melrose's BCG matrix are strong cash generators with limited organic upside; in 2024 these units continued to fund group deleveraging and dividends while showing muted growth prospects. The best owner may be a scale consolidator able to extract synergies; Melrose should maintain tight operational performance, avoid big strategic bets, and prepare a clean exit to crystallize value.
Cash cows: mature, high‑share units generated steady free cash flow in FY2024, funding deleveraging and dividends. Pro forma FY2024 revenue c.£6.7bn with adjusted operating margin ~9% underpins reliable cash conversion. Lean platforms and aftermarket contracts drove efficiency gains and low‑growth, high‑visibility cash generation.
| Metric | FY2024 |
|---|---|
| Pro forma revenue | c.£6.7bn |
| Adj operating margin | ~9% |
| Efficiency gains | £200–300m p.a. |
The file you're previewing is the final Melrose Industries BCG Matrix you'll receive after purchase. No watermarks, no filler—just a polished, ready-to-use strategic matrix tailored for Melrose. After buying, the exact same document unlocks for download and is editable, printable, and presentation-ready. Clean, precise, and market-focused—no surprises, just actionable insight.
Non-core laggards have low share in flat or shrinking markets, draining management focus with minimal strategic payoff. They typically only break even or underperform, often yielding returns below Melrose’s cost of capital. Continued investment is hard to justify given limited upside. These businesses are prime candidates for exit or closure to redeploy capital.
Heavy upkeep across Melrose Dogs drains cash: reported net debt around £1.16bn and stagnant top-line left returns thin in 2024. No growth tailwinds means each pound invested chases diminishing returns, with margins compressed versus peers. Operational complexity hides the true drag on cash conversion and working capital. Cut exposure quickly to stop compounding losses.
Melrose units geographically stranded—plants distant from key customers and talent pools—inflate transport and labour costs, undermining competitiveness; FY2024 revenue stood at £4.8bn, but logistic-driven lead times and freight premiums siphon margin. Despite CAPEX fixes and local hiring incentives, market share continues to erode as customers shift to nearer suppliers. Recommend divest, consolidate footprints, or orderly wind-down of non‑strategic sites.
High‑complexity, low‑margin product lines at Melrose demand bespoke effort but fail to command premium pricing; they sit in the Dogs quadrant with low market share and low growth, generating disproportionate operational headaches.
Turnaround attempts historically show limited stickiness; Melrose accelerated disposals in 2024 to simplify the portfolio and free capital for higher-return assets.
Small-tail brands: long SKU lists with negligible relevance drain working capital and management bandwidth; Melrose, with c.£4bn revenue in FY2024, cannot justify slow-moving SKUs that occupy warehouse space and cash conversion cycles while delivering <5% of sales from many niche lines.
Dogs: low share, low growth units draining cash and management focus; FY2024 revenue £4.8bn with net debt ~£1.16bn, limited upside—prioritise exit or sale to redeploy capital.
| Metric | FY2024 | Action |
|---|---|---|
| Revenue | £4.8bn | Divest/consolidate |
| Net debt | £1.16bn | Reduce exposure |
| Slow SKUs | <5% sales each | Trim tail |
Newly acquired fixes sit in fast-growing end markets but hold only a tiny share today, requiring material cash as restructuring and go-to-market builds ramp up. They are deliberate cash burners with uncertain outcomes: upside is genuine if integration delivers scale and margin improvement within the first 12–24 months. Invest aggressively only where a clear, provable edge emerges; otherwise move to sell to protect capital and focus on core earners.
Melrose's question marks include units doubling down on automation, electrification and digital service layers where 2024 industry growth runs near 20% in key niches, but Melrose's share remains small; early capex and R&D outlays are currently outpacing returns, compressing margins and cash conversion. Rapid scale could capture winner-take-most economics, but failure to scale risks a slide into dog status as unit value decays.
Bolt‑ons with promise are acquisitions that complement a Melrose platform but haven’t yet earned a full seat; integration, cross‑sell and operational discipline are the levers to demonstrate value. Cash consumption typically spikes in year one as capex and working capital are absorbed. Clear FY2024 milestones — against Melrose reported revenue of £4.5bn — decide whether to double‑down or divest.
Adjacent market tests push Melrose into nearby sectors where its restructuring playbook can transfer, but current positions are small and brand, channels and aftermarket capability need time to land.
Given hot end-markets, management must either scale market share rapidly through focused investment and M&A or cut losses and refocus core operations.
Data and services overlays — analytics, uptime guarantees and performance‑based contracts on Melrose hardware — are classic Question Marks: market growth and reported recurring service revenues rose ~12% in 2024, but share remains low. Success needs upfront systems, specialist talent and customer education; prioritise offerings with sticky unit economics and exit low-retention plays.
Question Marks: small-share, high-growth units needing heavy capex/R&D; success hinges on integration scaling within 12–24 months or divest. FY2024 context: Melrose revenue £4.5bn; target bets in automation/e‑services face ~20% niche growth and ~12% service recurring rev rise. Prioritise units hitting >70% retention and >15% gross margin or exit.
| Metric | FY2024/Target |
|---|---|
| Group revenue | £4.5bn |
| Target retention | >70% |
| Target gross margin | >15% |
| End‑market growth | ~20% |
| Service rev growth 2024 | ~12% |


