
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Mengniu’s strengths in scale, distribution, and R&D are balanced by margin pressure, regulatory sensitivity, and rising competition, while growth hinges on premiumization and export expansion. Our full SWOT unpacks these dynamics with data-driven insights and strategic recommendations. Purchase the complete report for editable Word and Excel deliverables to support investor pitches and planning.
As one of China’s leading dairy manufacturers, Mengniu leverages strong brand recognition and shelf presence—FY2023 revenue was about RMB 90 billion and its market share is roughly 20%, with top-two (Mengniu+Yili) exceeding 40% of the retail dairy market. Scale boosts bargaining power with suppliers and distributors and delivers operating leverage across production, logistics and marketing, helping defend positions in milk, yogurt, beverages, cheese and ice cream.
Mengniu, listed on the Hong Kong Stock Exchange since 2004, spans core liquid milk, yogurt, milk beverages, cheese and ice cream, smoothing category cycles. This breadth enables cross-selling and channel optimization across retail and e-commerce. It also permits rapid response to shifting taste and health trends, reducing reliance on any single SKU and enhancing portfolio resilience.
Brands like Mengniu, Champion and Shiny Meadow address distinct segments and price tiers, enabling premiumization while protecting mass‑market volumes; Mengniu Group holds roughly 20% of China’s dairy market. This tiered architecture captures urban and rural demand simultaneously and strengthens brand equity, lowering customer acquisition costs and boosting repeat purchase rates.
Mengniu’s national reach across modern trade, traditional trade and an expanding cold-chain network underpins volume and freshness, supporting reported 2023 revenue of RMB 87.4 billion and coverage of over 2.5 million retail outlets and 1,000+ cold-chain points.
Continuous NPD in functional, high-protein, low-temperature and flavored segments drives Mengniu’s top-line momentum and supports penetration of premium dairy categories.
Strong R&D capabilities and consumer-insight loops enable faster iteration on tastes and formats, shortening time-to-market and raising SKU productivity.
Innovation improves product mix and margins, strengthens premium positioning and provides clear differentiation versus private labels.
Mengniu is a top‑2 Chinese dairy with RMB87.4bn revenue in 2023 and ~20% retail share (top‑2 >40%), yielding scale advantages in procurement, distribution and marketing.
Broad portfolio (liquid milk, yogurt, cheese, ice cream) and brands (Mengniu, Champion, Shiny Meadow) enable premiumization and cross‑channel resilience.
National reach (~2.5M outlets, 1,000+ cold‑chain sites) plus rapid NPD boosts mix and margins.
| Metric | 2023 |
|---|---|
| Revenue | RMB87.4bn |
| Retail share | ~20% |
| Top‑2 share | >40% |
| Outlets | ~2.5M |
| Cold‑chain sites | 1,000+ |
 Detailed Word Document
Provides a concise strategic overview of Mengniu’s internal strengths and weaknesses and external opportunities and threats, mapping competitive position, growth drivers, operational gaps, and market risks to inform strategic decisions.

 Customizable Excel Spreadsheet
Provides a concise SWOT matrix of Mengniu for fast strategic alignment and stakeholder-ready summaries, enabling quick edits to reflect market shifts and streamline decision-making.
Revenue remains concentrated in mainland China, accounting for over 90% of Mengniu’s sales, heightening sensitivity to domestic macro and regulatory shifts. Regional slowdowns or demand shocks can quickly pressure volumes and margins, as domestic demand drives near-term growth. Geographic concentration also limits currency diversification, with international operations contributing under 10% of revenue.
Liquid milk remains highly competitive and typically posts margins 8–12 percentage points lower than premium yogurt or cheese, squeezing Mengniu’s profitability on core volumes. Heavy promotions and regional price wars can further erode margins by 2–4 percentage points during peak campaigns. Shifting the portfolio toward higher-value SKUs demands sustained marketing and R&D investment, and short-term profitability often dips during the transition.
Volatile raw milk, feed, energy and packaging costs compress Mengniu’s gross margins—raw milk can represent c.40% of dairy COGS—forcing price pass-through that risks volume elasticity in lower-value tiers. Hedging programs only partially offset swings, leaving residual exposure to feed and energy spikes. Sudden cost surges have previously forced cuts to marketing and R&D budgets, constraining innovation and premiumization efforts.
Perishability demands reliable cold storage and flawless last-mile execution; breaches lead to waste, returns and brand damage. Expanding cold-chain into lower-tier cities raises capex and OPEX, with China cold-chain market surpassing RMB 1 trillion in 2022. Network complexity increases inventory days and can strain Mengniu’s working capital and cash conversion cycle.
The dairy category is highly sensitive to safety and quality perceptions; past industry crises such as the 2008 melamine scandal show how quickly trust can collapse, forcing Mengniu into sustained QA and traceability investment and tighter supplier controls.
Revenue >90% China concentration heightens exposure to domestic macro and regulatory shocks; international sales remain under 10%. Liquid milk margins trail premium SKUs by c.8–12 pp, with promotions cutting 2–4 pp. Raw milk ≈40% of dairy COGS; cold-chain capex is material (China cold-chain > RMB 1 trillion in 2022).
| Metric | Value |
|---|---|
| China revenue share | >90% |
| International revenue | <10% |
| Liquid vs premium margin gap | 8–12 pp |
| Raw milk share of COGS | ≈40% |
| China cold-chain market (2022) | RMB 1+ trillion |
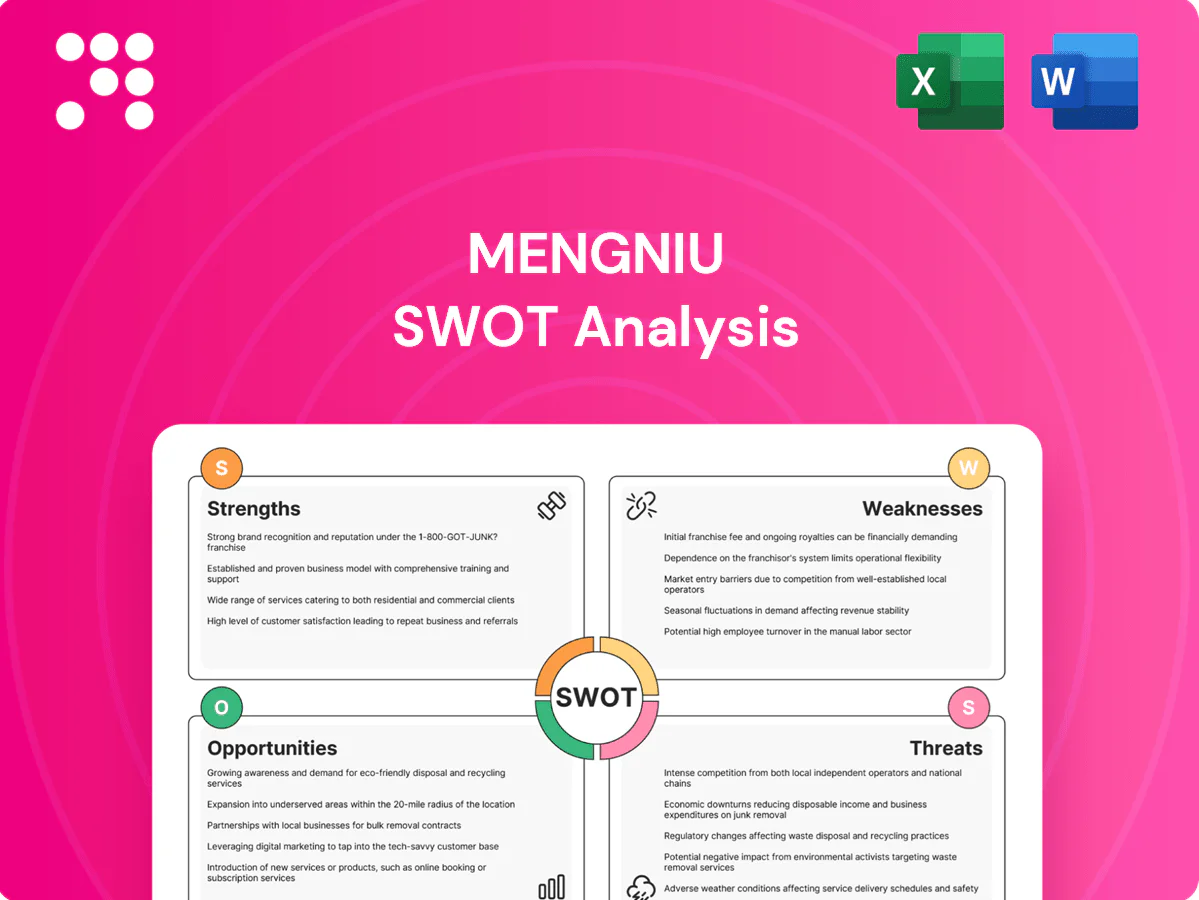
This is the actual Mengniu SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report you'll get; purchase unlocks the complete, editable version. Get the full, structured analysis immediately after checkout.
Urban Chinese consumers are trading up to grass-fed, organic and low-temperature fresh milk, with premium fresh milk prices typically commanding a 20–30% premium over standard products and China’s premium dairy segment growing >10% YoY in 2023.
Shiny Meadow can anchor higher price points and emotive brand storytelling, supporting Mengniu’s premium mix expansion which lifts gross margins and repeat purchase rates.
Bundling Shiny Meadow with functional benefits (e.g., high-protein, probiotics) can deepen penetration in tier‑1/2 cities and drive basket size increases and loyalty.
High-protein, probiotics, lactose-free and low-sugar lines match rising health demand and support Mengniu capturing the China functional dairy segment, which saw double-digit unit growth in 2024; functional SKUs typically command a 10–30% pricing premium versus standard lines. Partnerships with nutrition institutes can validate claims and reduce regulatory risk, while expanded on-the-go formats tap urban consumers where single-serve RTD dairy grew ~12% in 2024.
China's cheese consumption remains low at about 1 kg per capita in 2024 versus a global average near 6.8 kg, indicating substantial upside for Mengniu. Kid-focused cheese snacks and shredded/baking cheese have seen double-digit sales growth recently, driven by urban families and e-commerce. Localized flavors and consumer education can accelerate adoption across inland regions. Cheese typically yields higher gross margins than commodity liquid milk, improving portfolio profitability.
Online channels enable targeted promotions, richer data capture and subscription models to boost lifetime value; China’s online retail sales reached 13.1 trillion yuan in 2023 (NBS), highlighting scale. D2C reduces channel conflict and improves repeat rates, while digital-only launches let Mengniu test concepts before national rollouts; cold-chain partnerships extend refrigerated reach efficiently.
Selective international expansion targets Southeast Asia (≈670 million population) and Belt and Road markets (140+ partner countries), leveraging export and JV models to diversify revenue and currency exposure; tapping an overseas Chinese diaspora of ~50 million can seed premium brand demand, and phased market entry limits execution and supply-chain risks.
Premium fresh milk growth >10% YoY (2023) and 20–30% price premium, functional dairy double-digit unit growth (2024) and RTD dairy +12% (2024) create margin-expanding premiumization and innovation opportunities; cheese per capita 1 kg (2024) vs global 6.8 kg signals large upside; online retail 13.1 tn yuan (2023) and ~50M overseas Chinese enable D2C and regional expansion.
| Metric | Value |
|---|---|
| Premium growth (2023) | >10% YoY |
| Premium price | +20–30% |
| RTD dairy (2024) | +12% |
| Cheese per capita (China 2024) | 1 kg |
| Online retail (China 2023) | 13.1 tn yuan |
Domestic rivals such as Yili, Bright Dairy and multinational players like Nestlé and Danone compete aggressively with Mengniu on price, product innovation and omnichannel distribution, driving frequent promotions that erode margins. Rising-quality private labels and regional niche brands are taking shelf space, while category fragmentation forces higher marketing and SKU management costs, intensifying share battles across retail and e-commerce.
Plant-based and alternative proteins threaten Mengniu as the global plant-based dairy market reached about $24 billion in 2023 and is growing near 9–10% annually, attracting health- and eco-conscious consumers. Non-dairy beverages gain shelf space, pressuring dairy velocities while price gaps on key SKUs have narrowed. Substitution risk is highest among younger, urban buyers, where adoption rates and trial frequency are markedly greater.
Stringent and evolving food safety, labeling and advertising rules in China raise regulatory risk for Mengniu; compliance failures can trigger fines and product withdrawals and damaged trust. New technical standards and traceability rules are likely to increase operating costs and capex, while policy shifts on raw milk sourcing and import tariffs can disrupt supply chains and input prices, affecting margins and revenue stability.
Slower consumption growth and cautious households risk depressing discretionary dairy upgrades; China recorded 9.56 million births in 2023 and a total fertility rate near 1.09, pressuring kids-focused segments. Rising income polarization (Gini ~0.47) complicates uniform pricing, and prolonged weak demand can delay premium product adoption for Mengniu.
Extreme weather, highlighted by the IPCC as increasing in frequency, depresses feed yields and destabilizes raw milk supply for China, the world’s largest dairy producer, raising risk of seasonal shortages. Disease outbreaks such as ASF-like livestock shocks strain herds and logistics, elevating biosecurity and transport costs. Resulting supply shocks drive input-cost volatility and intermittent stockouts, while rising ESG expectations force capital expenditures for sustainable farming and traceability upgrades.
Intense competition from Yili, Bright Dairy, Nestlé and Danone compresses margins via promotions and SKU proliferation. Plant‑based dairy (≈$24B in 2023; CAGR ~9–10%) and non‑dairy substitutes cut volumes among urban youth. Regulatory shifts, supply shocks and climate-driven feed volatility raise compliance and input‑cost risks; China births 9.56M (2023), TFR ~1.09, Gini ~0.47.
| Threat | Key data |
|---|---|
| Competition | Price wars, SKU growth |
| Alternatives | Plant‑based $24B (2023), CAGR 9–10% |
| Demographics | Births 9.56M (2023), TFR 1.09 |
| Regulatory/Climate | Higher capex, supply volatility |


