
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
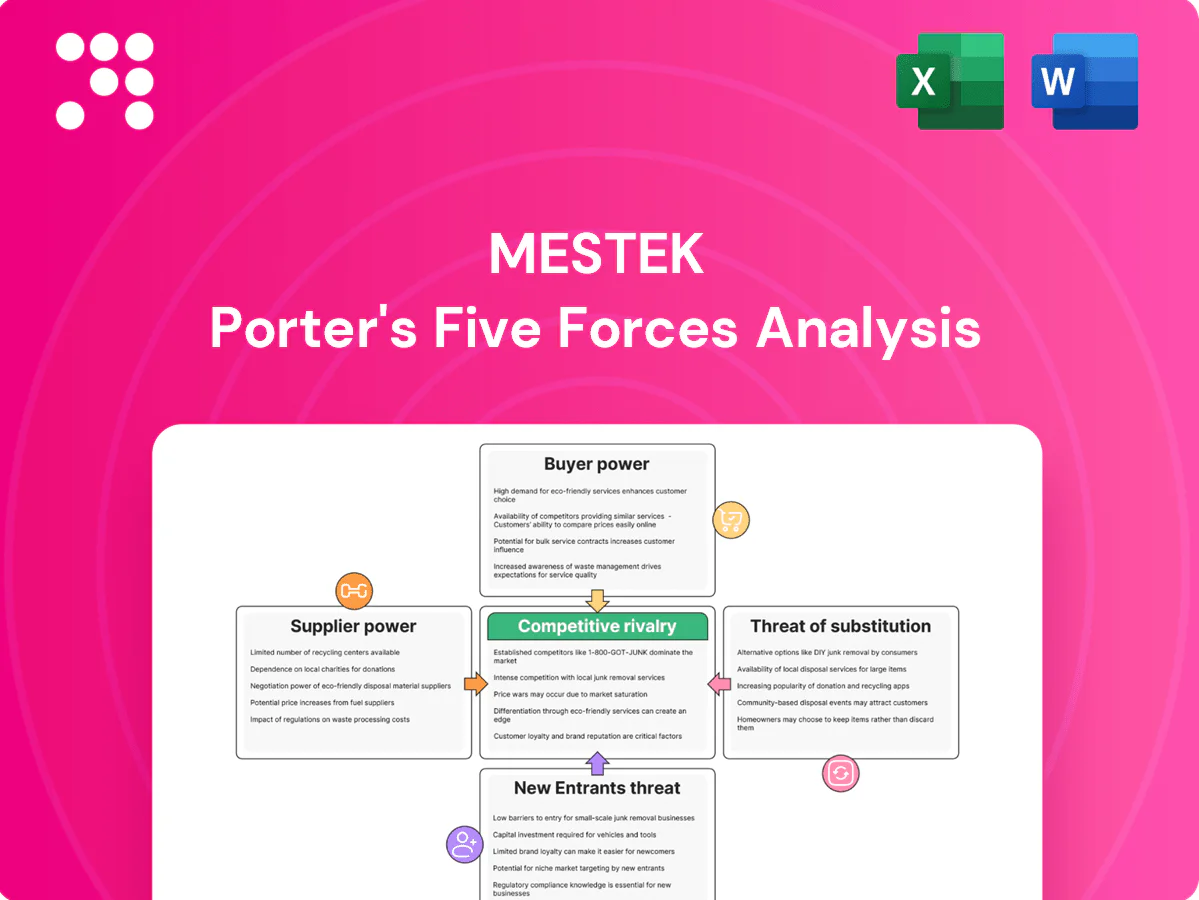
Mestek’s Porter's Five Forces highlights supplier leverage, buyer power, competitive rivalry, threat of entrants and substitutes, and how these shape margins and strategic positioning. This snapshot surfaces key risks and opportunities but only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore Mestek’s competitive dynamics, market pressures, and strategic advantages in detail.
Steel, copper and aluminum plus motors, compressors and heat exchangers are core HVAC inputs; commodity surcharges commonly add 5–15% to supplier invoices. Price swings in 2024 increased input cost volatility, compressing margins quickly and forcing pass-throughs. Concentrated specialty suppliers (top 3 compressor/EC-fan makers ~50% share) wield pricing leverage. Long-term contracts and hedging partially mitigate but do not eliminate risk.
Dependence on PLC/PCB, sensors and VFDs keeps supplier power high as 2024 industry surveys cite lead times commonly between 12–20 weeks, raising component costs by roughly 10–25% versus pre‑pandemic levels. Design qualification cycles of 6–12 months limit rapid switching, while firmware, safety and regulatory certifications create vendor stickiness. Dual‑sourcing and modular designs can cut single‑supplier exposure by ~30–40% but do not fully eliminate risk.
Supplier-specific tooling for rolls, dies, castings and coils creates high changeover costs and requalification delays, often 4–12 weeks and commonly costing $20,000–$200,000, granting suppliers leverage. Buyers frequently must commit volumes or long-term contracts to secure capacity; in metals fabrication, volume commitments of 12–36 months are typical. Close engineering collaboration can shift margin to suppliers in exchange for improved performance and reduced lead times.
Imported components face freight, tariff and geopolitical risk; freight spikes (2–3x historic levels in recent shocks) and customs delays (adding ~10–30% to lead times) amplify supplier clout in 2024.
Nearshoring cuts transit and geopolitical exposure but can raise unit costs roughly 5–20% versus low-cost offshore sourcing.
Higher safety stocks (raising inventory by ~10–25%) buffer shocks yet tie up working capital and compress ROIC.
Core HVAC inputs (steel, copper, compressors, motors) drove 2024 supplier leverage via 5–15% commodity surcharges and concentrated specialty suppliers (~50% share). Key electronics saw 12–20 week lead times, raising component costs 10–25% and limiting switching. Tooling/requalification ($20k–$200k, 4–12 weeks), freight spikes (2–3x) and nearshoring premiums (+5–20%) sustain high supplier power.
| Metric | 2024 |
|---|---|
| Commodity surcharge | 5–15% |
| Specialty supplier share | ~50% |
| Lead times (electronics) | 12–20 wk |
| Component cost rise | 10–25% |
| Tooling cost/time | $20k–$200k / 4–12 wk |
| Freight spikes | 2–3x |
| Nearshoring premium | +5–20% |
| Inventory impact | +10–25% |
| Low‑GWP premiums | 10–20% (lead +3–6 mo) |
 Detailed Word Document
Comprehensive Porter’s Five Forces analysis tailored for Mestek, assessing competitive rivalry, supplier and buyer power, threat of substitutes and new entrants to reveal strategic vulnerabilities and defensive advantages.

 Customizable Excel Spreadsheet
A concise, one-sheet Mestek Porter's Five Forces summary that visualizes competitive pressures with an editable radar chart and clear labels—perfect for quick strategic decisions, slide-ready reporting, and non-technical users.
Large distributors, OEMs, and national contractors aggregate demand and often account for a material share of manufacturers sales (commonly 20–50% in 2024), enabling negotiation of price, payment terms, and rebates. Losing a key account can reduce plant utilization by 10–30%, pressuring margins. Differentiated specs and superior service limit discount pressure and protect unit economics.
Project-based procurement concentrates buyer power as RFPs and engineered-to-order jobs drive side-by-side price comparisons, with projects typically attracting 3–5 bidders, intensifying margin pressure. Consulting engineers and spec writers shape vendor shortlists and shift buying toward specified solutions. Late-cycle value engineering commonly trims scope and erodes margin, while strong references and lifecycle performance data (warranty, energy, maintenance) defend premium pricing.
Installed-base compatibility and commissioning know-how create stickiness in HVAC, with replacement cycles of 10–20 years and OEM retrofit uptake often exceeding 60% in 2024. Metal forming buyers face high switching costs from tooling that commonly runs tens to hundreds of thousands of dollars plus operator training. Commodity SKUs, which can represent ~25–35% of volumes, are easier to swap and pressure margins. Service contracts and uptime guarantees have been shown to cut churn by up to 15%.
Cyclical budget sensitivity means construction and manufacturing cycles heavily sway volumes and discounting; in 2024 buyers increasingly demanded extended payment terms and lower prices as project pipelines tightened. Inventory overhang forced suppliers to concede on price and lead times, while flexible financing and extended-credit programs helped some vendors preserve margin and share.
Large distributors, OEMs and national contractors made up 20–50% of manufacturer sales in 2024, giving buyers strong price and payment leverage; losing a key account can cut plant utilization 10–30%. Project RFPs (typically 3–5 bidders) and late-stage value engineering compress margins, while differentiated specs, service and warranties defend premiums. Commodity SKUs (~25–35% of volume) boost switching power; service contracts cut churn up to 15%.
| Metric | 2024 Value |
|---|---|
| Share from large buyers | 20–50% |
| Utilization loss if lost | 10–30% |
| Typical bidders per RFP | 3–5 |
| Commodity SKU share | 25–35% |
This preview shows the exact Mestek Porter's Five Forces Analysis you'll receive—no mockups or placeholders. The file visible here is the full, professionally formatted document, ready for immediate download and use upon purchase. What you see is precisely what you get.
Mestek faces a broad incumbent field in HVAC—Carrier (~$24B 2024), Trane (~$16B), Daikin (~$24B), Lennox (~$4.5B) and Johnson Controls (~$28B) plus niche hydronic and air-movement firms—while metal forming rivals include Amada and Bradbury. Brand equity, deep channel networks and a large installed base create high switching costs and drive aftermarket stickiness. Many competitors pursue niche specialization to avoid direct head-to-head battles, preserving margins.
Refrigerant shifts driven by the Kigali HFC phasedown and DOE efficiency rules (2023) that raised many AC/furnace efficiency targets by roughly 10–15% force frequent redesigns. Controls, IoT upgrades and 2–3 year product cycles compress differentiation windows as fast followers adopt features quickly. Rising compliance and retooling costs raise table stakes and intensify spec battles. Proprietary hardware-software stacks remain the clearest route to sustain edge.
Air handlers, coils and simple forming equipment are increasingly subject to price-led bids, with low-cost imports undercutting domestic offers by as much as 20% in 2024 and compressing margins on commoditized SKUs. Value-add services, engineering support and customization sustain margin pockets, often preserving 10–15% higher gross margins versus pure parts. Bundled offerings and system-level solutions shift competition from discrete components to integrated systems, raising switching costs and protecting OEM position.
Aftermarket parts, field service, and training form a service-network moat for Mestek, boosting win rates and loyalty by ensuring rapid repairs and skilled operation; rivals with denser coverage gain a clear advantage in bids. Uptime SLAs (99%+ in critical contracts) and remote diagnostics raise switching costs and justify premium pricing. Investing in service capacity measurably curbs churn and drives recurring revenue.
Cyclical demand swings push plants below optimal loads, triggering price wars; US manufacturing capacity utilization averaged about 76% in 2024, intensifying discounting during troughs. Suppliers with sub-8-week lead times won awards in tight pockets, while flexible manufacturing reduced the need for deep discounts. Improved backlog visibility in 2024 strengthened pricing discipline and limited margin erosion.
Mestek competes with large incumbents (Johnson Controls $28B, Carrier $24B, Daikin $24B, Trane $16B, Lennox $4.5B) and niche metal-forming firms, creating intense spec and price battles. 2024 refrigerant/efficiency rules and fast IoT adoption compress product cycles and raise retooling costs. Aftermarket/service yields 10–15% higher gross margins and, with 76% US capacity utilization (2024), service networks and lead-time advantages are decisive.
| Metric | 2024 |
|---|---|
| US capacity utilization | ~76% |
| Import price undercut | ~20% |
| Aftermarket margin premium | 10–15% |
Air-to-water and VRF heat pumps, with typical seasonal COPs of 2–4, can directly substitute hydronic and steam systems, cutting operational energy use by 20–50%. Policy incentives such as the US Inflation Reduction Act offering up to 30% tax credits and EU national rebates in 2024 have accelerated adoption. Improved cold-climate models operating near −25°C expand addressable markets, while hybrid heat-pump+boiler systems partially blunt full substitution.
Improved insulation, upgraded glazing and tighter envelopes can cut HVAC capacity needs by roughly 20–40% (US DOE/2024), materially lowering unit sizing. Demand-side management and smart thermostats typically trim runtime 10–15%, enabling deferred replacements. The net effect is erosion of traditional equipment sales, while controls optimization shifts value to software/services—building controls market projected ~8% CAGR in 2024 estimates.
Laser cutting, press brakes and additive manufacturing can replace roll-forming in short runs and complex geometries—typically under a few hundred parts—where setup and lead-time advantages outweigh per-piece cost. For high volumes (thousands+ units) roll-forming retains a clear cost advantage. Strong application engineering and forming design can preserve fit and performance, limiting substitution.
Customers increasingly outsource metal parts to contract manufacturers rather than buying equipment, shifting demand from capex to opex and reducing Mestek's equipment-sales addressable market.
Turnkey suppliers offering integrated production lines and end-to-end services compress the need for in-house capability, while service, maintenance and financing packages from OEMs and suppliers aim to counteract the shift by preserving recurring revenue streams.
Air-to-water/VRF heat pumps (COP 2–4) can cut HVAC energy 20–50% and gained 2024 policy support (US 30% tax credit). Envelope upgrades plus smart controls trim load 20–40% and runtime 10–15%. Manufacturing substitutes and outsourcing shift demand from capex to opex, while turnkey suppliers and service packages preserve recurring revenue.
| Substitute | Impact | Metric |
|---|---|---|
| Heat pumps | Direct substitution | 20–50% energy, COP 2–4 |
| Envelope/controls | Load reduction | 20–40% load, 10–15% runtime |
| Manufacturing/outsourcing | Market shift | Capex→Opex |
Building manufacturing lines and accredited testing labs typically requires CAPEX of roughly $5–25 million and specialized rigs; UL certification can cost $20k–150k while AHRI/CE test campaigns often run $50k–200k. Tight safety and refrigerant rules (F‑gas/HFC phase‑downs) add compliance complexity and retrofit costs. New entrants face 12–24 month approval cycles and established QA credentials and audit histories (years of documented reliability) deter entry.
Distributor relationships and spec-in positions create high switching barriers for Mestek; engineers and owners consistently favor proven brands, driving repeat business and reducing churn. Service coverage expectations—often requiring 24-hour response and regional parts inventories—raise entry costs for newcomers. Pilot projects and 1–3 year performance warranties are commonly required to gain trust and win initial specs.
In 2024 incumbents leverage scale to secure materially better pricing on metals, motors and electronics, lowering delivered unit cost and using volume buys and hedging to smooth input volatility; new entrants typically cannot match these delivered costs. Contract manufacturing can narrow the gap by providing procurement leverage and fixed-cost absorption but generally does not eliminate incumbents’ end-to-end sourcing advantage.
Modular designs, cloud controls and ecommerce let niche entrants reach market faster, but high-touch field service and on-site commissioning keep barriers; compliance data and cybersecure controls are non-negotiable for customers. Entrants typically prove product-market fit in narrow segments before scaling across channels and service models.
Incumbents often defend share by discounting, bundling, or pursuing litigation, raising barriers for entrants; tooling know-how and process IP are concentrated and difficult to replicate, increasing sunk costs for new players. Customers discount greenfield risk and prefer established vendors, so partnerships, OEM agreements, or white-label routes are more common than standalone greenfield entry.
High CAPEX ($5–25M), certification costs (UL $20k–150k; AHRI $50k–200k) and 12–24 month approvals create steep entry barriers. Distributor ties, 24h service expectations and 1–3yr warranties favor incumbents; scale yields ~10–25% delivered cost advantage. Niche modular/cloud entrants succeed via OEM/partnership routes before scaling.
| Metric | Value |
|---|---|
| CAPEX | $5–25M |
| Cert costs | $20k–200k |
| Approval cycle | 12–24 months |
| Incumbent cost edge | ~10–25% |


