
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
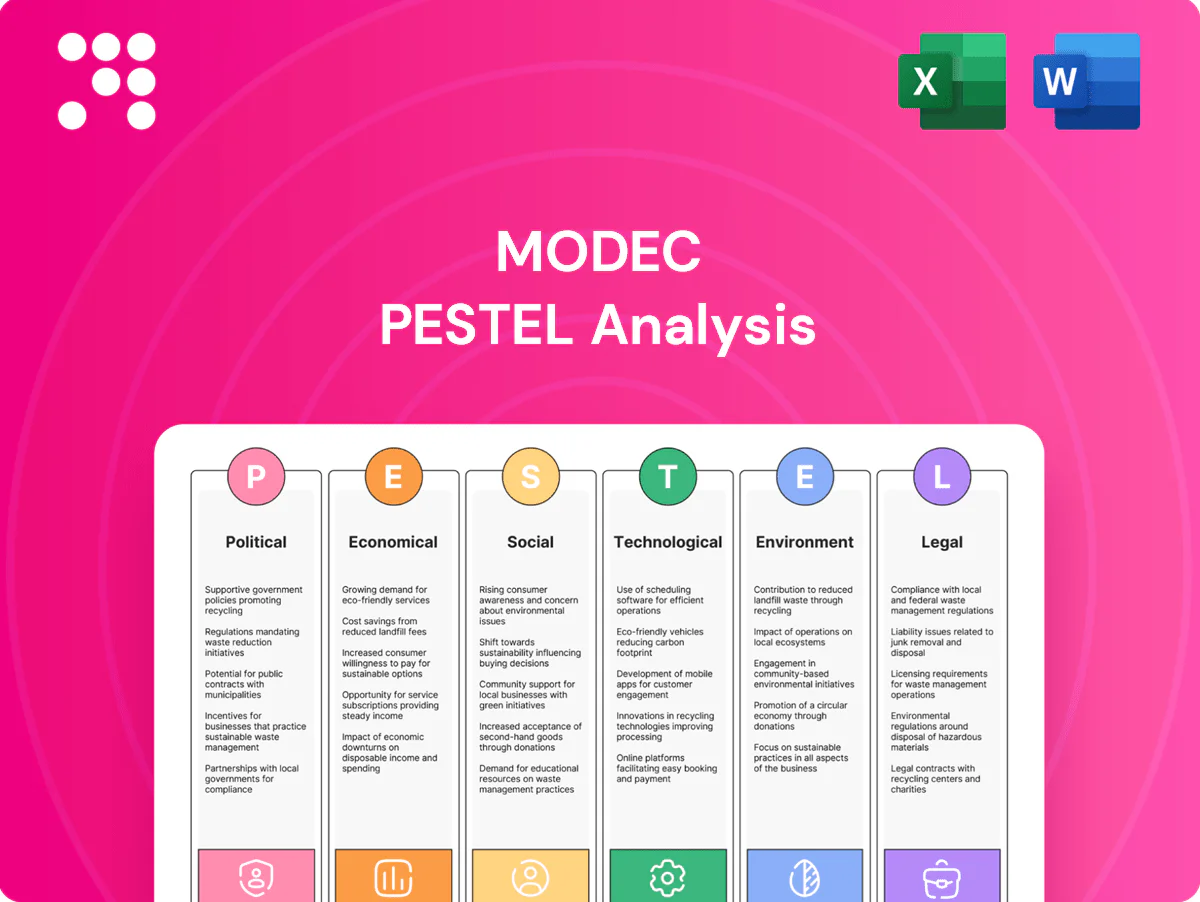
Unlock how political shifts, offshore energy economics, and environmental regulation shape MODEC’s strategic path in our focused PESTLE snapshot. This concise brief highlights risks and opportunities you can act on now. Purchase the full PESTLE for the complete, editable analysis and turn insights into advantage.
Host governments increasingly push local content, higher taxation and state participation in offshore projects, which can reshape FPSO contract economics; FPSO capex typically runs $500m–$2bn, so even small policy shifts materially affect returns and schedules. MODEC must navigate changing rules across more than 10 producing jurisdictions by forging strategic partnerships with national oil companies and stakeholder engagement to mitigate renegotiation risk. Continuous monitoring of policy signals and early local engagement helps preempt costly contract changes and delays.
MODEC operates in politically diverse basins including West Africa, Latin America and Asia, where local instability can interrupt EPCI and O&M activities and delay project schedules.
Heightened security risks drive higher insurance premiums and complicate logistics for offshore platforms, increasing operating expenditure and project timelines.
Geographic diversification and robust contingency planning reduce exposure, while scenario planning underpins resilient backlog management and contract execution.
Energy security agendas that push for domestic supply are accelerating deepwater sanctions and support rising FPSO demand, with over 200 FPSOs operating globally by 2024. Conversely, national energy transition targets and green financing have redirected capital to renewables, tightening oil & gas project timelines. MODEC can align with national plans to access concessional financing and permits, and targeted policy advocacy will shape its long-cycle investment decisions.
Sanctions regimes can block MODEC from clients, shipyards or key components, with OFAC’s SDN list exceeding 6,000 entries (2023) and EU/UK measures expanding since 2022, raising supplier risk and insurance costs. Compliance adds lead time and 3–8% procurement cost premia and requires continuous legal oversight and alternative sourcing to avoid project delays.
Many FPSO awards are driven by state-linked buyers and NOCs (for example Petrobras, ADNOC, CNOOC, Equinor), whose bespoke tender rules and 4-year political cycles shape timing and budgets; electoral or budget resets often delay awards into new fiscal years. Transparent procurement, strong ESG credentials and visible relationship capital with policymakers materially improve competitiveness and pipeline visibility.
Host governments push local content, higher taxes and state participation reshaping FPSO economics; capex ~$500m–$2bn so small policy shifts matter. MODEC operates in >10 producing jurisdictions and >200 FPSOs globally (2024), needing NOC partnerships and continuous policy monitoring. Sanctions, rising insurance and 3–8% procurement premia require alternative sourcing and legal oversight.
| Item | Key datum |
|---|---|
| FPSOs global (2024) | >200 |
| Jurisdictions | >10 |
| Capex | $500m–$2bn |
| Sanctions list (OFAC 2023) | >6,000 |
 Detailed Word Document
Explores how macro-environmental factors uniquely affect MODEC across Political, Economic, Social, Technological, Environmental, and Legal dimensions, with data-driven trends and region-specific regulatory context; designed for executives and investors, it includes forward-looking insights, scenario inputs, and deck-ready formatting to identify risks and opportunities.

 Customizable Excel Spreadsheet
A clean, summarized MODEC PESTLE analysis for easy referencing during meetings or presentations, visually segmented by PESTLE categories for quick interpretation and easily shareable to align teams and support external risk discussions.
Brent around $85/b in mid-2025 directly influences FID timing for deepwater projects and FPSO orders, with sustained sub-$60/b historically delaying awards and compressing day rates. Higher Brent expands project backlogs and improves contractor margins, benefiting MODEC which leverages strict cost discipline and counter-cyclical tendering to win work. MODEC’s use of hedging and flexible contracting helps stabilize cash flows and reduce exposure to volatile day rates.
FPSOs are capital intensive (newbuild capex commonly $1–2bn) and highly sensitive to interest rates; US Fed funds were about 5.25–5.50% in mid‑2025, raising lease costs and client hurdle rates. Strong relationships with lenders and export credit agencies (eg JBIC, Hermes) secure longer tenors and tighter margins. Innovative structures—ECA financing, sale‑leaseback, project bonds—keep projects bankable by lowering sponsor equity and improving debt tenors.
Rising steel (HRC ~700 USD/ton in H1 2025), topside module and marine-equipment cost inflation are materially pressuring EPC budgets for MODEC, with module fabrication often accounting for a large share of capex. Yard utilization above ~85% and constrained vendor capacity are lengthening schedules to 12–24 months and inflating prices. Early procurement and frame agreements have proven to lower volatility, while contractual cost pass-through clauses preserve margins by enabling recovery of material and fabrication inflation.
MODEC faces FX risk as revenues and costs span USD, JPY, BRL and others; currency mismatches over multi-year projects can erode margins, highlighted by a stronger USD in 2024 (DXY ~103) and significant BRL swings during 2024.
Macro growth shapes oil demand and investment appetite: IMF projected global GDP growth at 3.0% in 2024, while IEA reported oil demand rising about 1.1 mb/d in 2024, with petrochemicals accounting for roughly 40–45% of demand growth—supporting offshore development. Recession risks can defer FIDs, but MODEC’s diversified client base across majors and NOCs helps smooth cyclical swings.
Brent ~85 USD/b mid‑2025 supports FID activity and FPSO day rates; sub‑60 USD/b historically delays awards. Higher rates (Fed funds 5.25–5.50% mid‑2025) raise capex financing costs; ECA and sale‑leaseback mitigate. Input inflation (HRC ~700 USD/t H1‑2025) and FX (DXY ~103 in 2024; BRL vol ~15% 2024) pressure margins.
| Metric | Value |
|---|---|
| Brent | ~85 USD/b (mid‑2025) |
| Fed funds | 5.25–5.50% (mid‑2025) |
| HRC | ~700 USD/t (H1‑2025) |
| DXY | ~103 (2024) |
The preview shown here is the exact MODEC PESTLE Analysis document you’ll receive after purchase—fully formatted and ready to use. The layout, content, and structure visible are identical to the downloadable file, with no placeholders or surprises. After payment you’ll immediately get this finalized, professionally structured report.
Offshore environments demand rigorous HSE practices; MODEC reported zero fatalities in 2023 and maintained an LTIFR of 0.10, reinforcing that strong safety performance sustains license to operate and client trust. Continuous training and behavior-based safety programs cut incident rates and supported a 12% year-on-year reduction in recordable incidents in 2024. Transparent reporting of HSE metrics strengthened stakeholder confidence and contract retention.
Communities and regulators expect job creation and skills transfer; in key markets like Brazil and Nigeria local content rules commonly target 30-40% local procurement, pressuring MODEC to develop local supply chains and training programs. Effective localization enhances bid competitiveness and can reduce logistical costs by lowering import dependency. It also fosters goodwill, improving permit timelines and community relations.
Perceptions of environmental and social impact can directly affect MODEC project approvals; IFC Performance Standard 1 mandates stakeholder engagement and a grievance mechanism for projects seeking IFC or Equator Principles-linked finance.
Proactive engagement and community investment (e.g., local hiring, supplier development) are proven mitigants to opposition in offshore projects.
Clear grievance mechanisms build trust and social KPIs increasingly feed tender scoring and sustainability ratings.
Specialized marine and process engineering skills remain scarce; 62% of energy firms reported talent shortages in 2023, making competitive compensation, clear career pathways and global mobility critical for MODEC to staff FPSOs and FLNG projects.
Diversity and inclusion correlate with stronger innovation and safety—McKinsey 2020 found gender-diverse companies 25% more likely to outperform—while university partnerships secure engineering pipelines and reduce hiring costs.
Public sentiment is shifting toward lower‑carbon solutions as the IEA notes oil demand could peak in the mid‑2020s under net‑zero scenarios (IEA WEO 2023); MODEC can frame FPSOs as lower‑emissions upstream enablers and quantify intensity reductions to win public trust. Clear decarbonization communication boosts reputation and aligning with clients’ ESG targets strengthens long‑term contracts and partnerships.
Strong HSE (zero fatalities 2023; LTIFR 0.10) and 12% fewer recordable incidents in 2024 sustain license to operate and client trust. Local content rules (30–40% in Brazil/Nigeria) force supplier development and training; skills shortages (62% firms, 2023) raise labor costs. Public demand for lower‑carbon projects and D&I (+25% outperformance) shape hiring, bids and reputational risk.
| Metric | Value |
|---|---|
| LTIFR 2023 | 0.10 |
| Recordable incidents change 2024 | -12% |
| Local content targets | 30–40% |
| Skills shortage (2023) | 62% |
Modular topsides and standardized hulls shorten build schedules by about 25% and can trim capex ~15%, while digital twins cut commissioning time and unplanned downtime by up to 20%; advanced process technologies boost uptime and recovery by several percentage points. MODEC’s engineering IP—backed by over 100 patents—differentiates bids, and ongoing R&D (around 2–3% of revenue in recent years) sustains cost and performance leadership.
IoT sensors, predictive analytics and remote monitoring can cut unplanned downtime by up to 50% and maintenance costs 10–40%, raising uptime and lowering O&M bills. Cybersecure data platforms enhance real-time decision-making while mitigating the average breach cost (around $4.45M in recent IBM reports). Digital twins drive lifecycle optimization with 10–20% capex/opex savings and integration with client systems improves transparency and reporting efficiency by ~30%.
Tighter integration of MODEC hulls with subsea production systems boosts operational efficiency and uptime, with industry case studies showing commissioning time cuts around 15–25%. Close collaboration with subsea OEMs reduces interface risk and has been linked to capital expenditure savings in the mid-teens percent range. Standardized interfaces accelerate EPCI cycles, while advanced systems engineering expertise creates a defendable competitive moat for MODEC.
Gas compression optimization, flare minimization and waste-heat recovery can cut CO2e materially: compression saves ~5–15% fuel, waste-heat recovery recovers ~10–30% of energy and flare cuts methane/CO2 significantly. Electrification and hybrid power (batteries or gas-to-wire) can reduce platform CO2 intensity by up to ~40%. Carbon-capture readiness supports ~90% potential capture; quantified emissions performance increasingly wins tenders.
Advanced coatings and high-performance alloys can extend offshore asset life by ~30–50% in harsh marine conditions; MODEC adoption reduces replacement CAPEX and increases uptime. Robotics and remote inspection cut human exposure and inspection costs by ~20–40% while improving frequency. Reliability engineering programs typically lower lifecycle costs by ~10–20% and supply qualification drives defect rates below ~2%.
Modular topsides, digital twins and IoT cut build/commissioning/unplanned downtime ~15–25% and O&M 10–40%; MODEC R&D (~2–3% revenue) and 100+ patents sustain differentiation. Electrification, compression and waste-heat recovery lower CO2/energy 5–40%. Robotics, coatings and reliability programs extend asset life 30–50% and trim lifecycle cost 10–20%.
| Metric | Range |
|---|---|
| Downtime/capex | 15–25% |
| O&M | 10–40% |
| CO2/energy | 5–40% |
| Life extension | 30–50% |
Strict offshore HSE regulations govern MODEC design and operations, driving detailed engineering, certification and audit readiness and often adding weeks to months to project timelines. Compliance and documentation are essential for tendering and inspections; non-compliance can trigger multimillion-dollar fines and remediation (eg Deepwater Horizon costs ~65 billion USD). Exceeding standards measurably lowers incident and liability risk, and continuous updates are required as rules evolve.
EPCI and lease contracts shift delay, performance and availability risks between MODEC and clients on projects with contract values typically in the hundreds of millions to >$1bn. Liquidated damages and warranties can be material versus contract value, sometimes reaching multi-million exposures. Careful drafting and tailored insurance (e.g., delay-in-startup, P&I) protect margins. Robust dispute resolution clauses reduce project uncertainty and cashflow disruption.
FPSOs must comply with flag, class and port-state control regimes; Paris MoU detention rates averaged about 1.2% in 2023–24, underscoring enforcement risk. Class society rules drive design choices and can add roughly 0.5–2% to CAPEX, with typical FPSO builds costing $0.8–2.0 billion. Regulatory changes frequently trigger retrofits costing $50–200 million and downtime at $1–3 million/day; proactive compliance planning reduces retrofit risk and commercial interruptions.
Sanctions, anti-bribery (ABAC) and AML laws compel MODEC to maintain robust compliance programs covering policy, controls and reporting; failures have led to multi-million to billion-dollar fines and debarment by multilateral development banks in past cases. Complex offshore supply chains amplify third-party risks, making enhanced due diligence, ongoing monitoring and targeted training essential to avoid enforcement action.
Multijurisdictional MODEC projects face complex tax regimes and contested permanent establishment risks; OECD Pillar Two (15% minimum tax) applies to groups with consolidated revenue above EUR 750 million, altering effective tax planning. Heightened transfer pricing scrutiny can compress internal margins and increase cash-tax volatility. Advanced pricing agreements and robust documentation reduce dispute risk and, alongside tax-efficient structuring, optimize after-tax returns.
Strict offshore HSE, flag/class/port-state rules and ABAC/AML/sanctions drive certification, retrofits and fines (Deepwater Horizon ~65bn USD); Paris MoU detention ~1.2% (2023–24). EPCI contracts allocate multi‑million LD/warranty risk; typical FPSO builds $0.8–2.0bn, retrofits $50–200m, downtime $1–3m/day. OECD Pillar Two 15% floor (EUR 750m threshold) and TP scrutiny raise tax and margin risk.
| Risk | 2023–25 Data | Typical Impact |
|---|---|---|
| Detention | Paris MoU 1.2% | Operational delay, fines |
| FPSO capex | $0.8–2.0bn | Project financing |
| Retrofit | $50–200m | Downtime $1–3m/day |
| Tax | Pillar Two 15% / EUR 750m | Higher ETR, restructuring |
Installation and operations can alter habitats, raise underwater noise (pile driving and machinery commonly exceed 160 dB re 1 µPa) and affect local biodiversity, prompting EIAs and mitigation plans as mandatory regulatory steps in most offshore jurisdictions.
Environmental impact assessments and legally required mitigation frameworks typically mandate baseline studies and compensation measures, with post-installation monitoring programs often running 5–25 years to track recovery and compliance.
Robust monitoring programs, including acoustic and benthic surveys, demonstrate stewardship and can reduce regulatory delays and fines; partnering with NGOs and academic institutions — used increasingly across the sector — enhances transparency and credibility with stakeholders.
Hydrocarbon handling demands robust containment and emergency preparedness, exemplified by the Deepwater Horizon legacy (total industry costs estimated near USD 65 billion), driving adoption of double barriers and continuous leak detection. Regular response drills—often mandated annually—plus strong incident response curb environmental and reputational damage. Insurers and operators maintain contingency and liability coverage commonly in the hundreds of millions to ensure swift remediation.
FPSOs drive significant Scope 1 emissions from onboard power generation and flaring; global flaring was ~140 billion m3 in 2022, emitting roughly 400 MtCO2, highlighting sector exposure. Efficiency upgrades and flare-gas recovery can cut onsite emissions materially and lower operating fuel costs. Transparent measurement and reporting meet client/regulatory demands, and emissions-linked contracts are increasingly likely.
Produced water treatment and waste handling must meet strict discharge limits such as the OSPAR 30 mg/L oil-in-water standard; advanced treatment trains (membranes, flotation, hydrocyclones) routinely lower oil-in-water to below 10 mg/L, reducing environmental impact and permitting reuse. Compliance prevents fines and operational shutdowns.
Extreme weather and changing sea-states threaten FPSO uptime and crew safety; satellite-era sea level has risen ~3.3 mm/yr and IPCC AR6 projects 0.3–1.2 m by 2100, increasing storm surge risk and operational interruptions.
Installation noise (>160 dB) and habitat disturbance force EIAs and mitigation plans; monitoring programs run 5–25 years. Major spills (Deepwater Horizon ~USD 65bn) and produced-water limits (OSPAR 30 mg/L; advanced treatment <10 mg/L) shape containment and treatment standards. FPSO emissions and global flaring (~140 bcm in 2022 ≈400 MtCO2) drive efficiency, reporting and flare-recovery investments.
| Metric | Value |
|---|---|
| Installation noise | >160 dB |
| Monitoring duration | 5–25 years |
| Deepwater Horizon cost | ~USD 65bn |
| Flaring 2022 | ~140 bcm / ~400 MtCO2 |
| OSPAR limit | 30 mg/L (oil-in-water) |


