
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
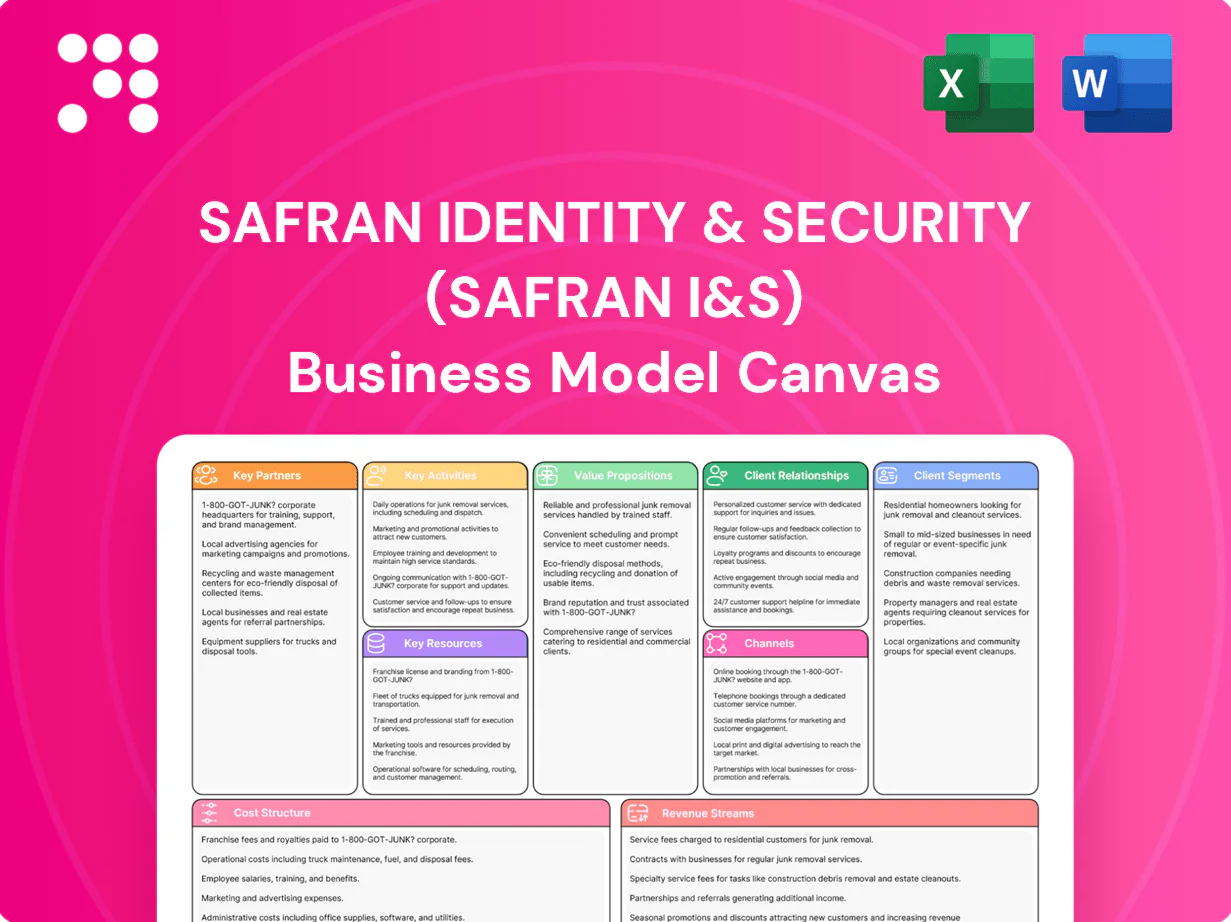
Unlock the full Business Model Canvas for Safran Identity & Security (Safran I&S) to see how its value propositions, partnerships, and revenue engines secure market leadership; this concise, actionable blueprint is ideal for investors, consultants, and strategists. Download the complete Word/Excel canvas to benchmark, adapt, and scale proven identity and security strategies today.
Collaborations with ministries of interior, border forces and civil registries enable delivery of large-scale ID programs that often enroll tens of millions of citizens and integrate with national border systems. These partners provide policy alignment, data stewardship and program funding, while co-design ensures compliance with national security and privacy mandates. Multi-year frameworks, typically 3–7 years, stabilize demand and set roadmap priorities.
Alliances with global system integrators deliver turnkey identity platforms, enabling Safran I&S to scale deployments across enterprise and government clients; the global biometric market exceeded $50 billion in 2024, driving higher platform demand. OEM deals embed Safran sensors and SDKs into third-party devices and kiosks, accelerating field uptake. Joint bids expand reach in complex, multi-vendor projects and shared SLAs streamline deployment and life-cycle support.
Partnerships secure advanced sensors, secure elements and cryptographic modules—ensuring biometric accuracy through dedicated silicon and optics suppliers that underpin performance and reliability. Co-development with vendors accelerates innovation and mitigates bill-of-materials risk by aligning roadmaps and reducing integration cycles. Dual-sourcing increases supply resilience and aids compliance with regulatory frameworks such as NIS2 transposition due in Oct 2024.
Banks and telcos enable digital onboarding and strong authentication, linking KYC, SIM registration and payment tokenization; collaboration leverages the 5.3 billion global mobile subscribers in 2024 (GSMA) to scale real-world deployments. High-volume transactions—hundreds of millions monthly in many markets—validate performance; revenue-sharing aligns incentives across ecosystems.
Engagement with ISO/IEC, FIDO, ICAO, and NIST ensures Safran I&S delivers interoperable identity and credentialing solutions, aligning to ICAO standards used by 193 member states and NIST guidance adopted across US federal programs. Certification pathways de-risk public procurements and improve bid success in regulated markets. Early alignment accelerates approvals and cross-border acceptance while continuous updates keep products compliant as rules evolve.
Strategic alliances with ministries, system integrators, OEMs, banks/telcos and standards bodies enable Safran I&S to deliver national ID, border and digital onboarding programs at scale, de-risk procurements and accelerate certifications.
Multi-year frameworks (3–7 years), dual-sourcing and revenue-sharing models stabilize demand and boost bid success in regulated markets.
| Metric | Value |
|---|---|
| Biometric market (2024) | $50B+ |
| Mobile subs (2024) | 5.3B |
| ICAO members | 193 |
| Framework length | 3–7 yrs |
 Detailed Word Document
A concise, pre-built Business Model Canvas for Safran Identity & Security detailing its nine blocks—customer segments, value propositions, channels, customer relationships, revenue streams, key resources, activities, partners, and cost structure—aligned to real-world operations, competitive advantages, SWOT insights, and investor-ready presentation use.

 Customizable Excel Spreadsheet
High-level, editable Business Model Canvas for Safran Identity & Security that condenses complex identity, biometric and secure-document strategies into a one-page snapshot, saving hours of structuring and enabling rapid team collaboration, comparison and board-ready briefings.
Continuous R&D improves fingerprint, face, iris and multimodal matching using diverse datasets exceeding 5 million samples to boost accuracy and mitigate bias; models aim for latency under 50 ms, FAR ~0.001% and FRR below 1%, with spoof-resistance tests reducing attacks by over 90% in lab benchmarks. Active patenting and licensing create differentiation and recurring revenue streams.
Design of sensors, enrollment stations, AFIS/ABIS and credential systems combines secure coding, peer code review and cryptography integration as core practices; in 2024 the global biometrics market was estimated at $48.6B, driving demand for higher-assurance systems.
Firmware-hardware co-design prioritizes throughput and tamper resistance, with secure boot and hardware roots of trust embedded at manufacture.
Continuous secure updates and patching maintain security posture and add features, reducing lifecycle breach risk and supporting compliance for government and enterprise customers.
End-to-end rollout of national ID, ePassport, border and voter systems covers design, enrollment, personalization and operations, aligning with the fact that by 2024 over 150 countries issue ePassports per ICAO. Requirements capture, customization and interoperability testing are mandatory to meet diverse registry and biometric standards. On-site installation, migration and formal acceptance testing secure go-live. PMO governance enforces scope, risk controls and milestone delivery.
Managed Services and Customer Support deliver 24/7/365 operations with target SLAs of 99.9% availability and preventive maintenance to sustain uptime; field engineers and multi-tier helpdesks resolve incidents fast, meeting median time-to-repair targets under 4 hours (2024 benchmarks). Capacity planning and upgrades accommodate 20%+ annual load growth and policy shifts, while training drives customer adoption and self-sufficiency.
Continuous R&D on fingerprint/face/iris with >5M samples targets <50 ms latency, FAR ~0.001% and FRR <1%; active patenting/licensing creates recurring revenue. Sensor/enrollment/AFIS design embeds secure boot and HW roots of trust. HSM/CA ops (FIPS/CC) and SOC/IR preserve trust; managed services target 99.9% SLA and MTTR <4h.
| Activity | 2024 metric | Target/notes |
|---|---|---|
| R&D | >5M samples | <50 ms, FAR 0.001% |
| Market | Biometrics $48.6B | ePassports>150 countries |
| HSM/CA | HSM market $1.3B | FIPS/CC, certs |
| Support | SLA 99.9% | MTTR <4h |
The Safran Identity & Security Business Model Canvas shown here is the actual deliverable, not a mockup or sample. When you purchase, you’ll receive this same complete document—formatted and structured exactly as previewed—for immediate download and editing. No hidden pages or placeholders, just the full, professional Canvas ready to use.
Core matching, liveness and anti-spoofing algorithms drive accuracy—NIST FRVT 2023 shows top face algorithms achieving >99.5% true accept rates at low false accept rates, underscoring algorithmic value. A strong patent/IP portfolio supports defensible differentiation and licensing in a biometric market exceeding $50 billion in 2024. Proprietary datasets improve model robustness and fairness, while trade secrets secure edge implementations and deployment know-how.
Precision production lines deliver sensors, scanners and enrollment kits with traceable process controls; environmental and stress testing follows MIL‑STD‑810 and IP68 criteria to guarantee field reliability. Secure, access‑controlled facilities comply with export control regimes (ITAR/EAR) and aim for ISO 27001 information security standards. Scalable manufacturing supports peak tender deliveries with modular production cells.
Data centers, HSMs and CA/RA systems form the PKI backbone, with HSMs certified to FIPS 140-2/140-3 and CA/RA operations handling millions of certificates; high-availability architectures target 99.999% uptime for mission-critical services. Tooling for automated key management and secure provisioning (4-eyes approvals, RBAC) is essential. Compliance controls embed SOC 2 and ISO 27001 auditability and strict segregation of duties.
Engineers, cryptographers, data scientists, and program managers drive Safran I&S delivery, combining product engineering with certified program oversight.
Field teams with government experience ensure compliance with security norms and procurement processes, while certification-trained staff support audits and standards.
Active partnerships with academia feed research pipelines and talent development.
Regulatory certifications ISO 27001, Common Criteria and ICAO compliance signal trust across governments and airports: ICAO has 193 contracting states, Common Criteria operates under the CCRA with 31 members, and ISO 27001 requires annual surveillance with triennial recertification to preserve market access.
Robust documentation and QA systems enable repeatable assurance and ease procurement barriers by meeting mandatory certification prerequisites for tenders.
Core biometric algorithms (NIST FRVT 2023: >99.5% TAR at low FAR), patent/IP protection and proprietary datasets underpin product differentiation; secure manufacturing (MIL‑STD/IP68) and certified HSMs (FIPS 140-2/3) support deployments. PKI and HA data centers target 99.999% uptime; ISO 27001/Common Criteria/ICAO compliance enable government procurement.
| Resource | Metric |
|---|---|
| Algorithm accuracy | >99.5% TAR (NIST FRVT 2023) |
| Market size | $50B (2024) |
| HSM | FIPS 140-2/140-3 |
| Uptime | 99.999% |
| ICAO | 193 states |
| CCRA | 31 members |
State-of-the-art matching delivers proven FAR/FRR performance on independent evaluation programs, supporting deployment in high-security missions. Robust liveness detection thwarts presentation attacks across contact and contactless modes. Multimodal fusion (face, fingerprint, iris) increases accuracy and reduces demographic bias. Independent benchmarks from NIST and third-party labs validate readiness for critical use cases.
End-to-End identity lifecycle from capture, enroll, deduplicate, credential, authenticate to revoke consolidates workflows, reducing vendor sprawl and risk; unified dashboards enhance governance and audits; pre-integrated modules speed time-to-value. 2024 Verizon DBIR highlights credential misuse as the top breach vector, underscoring need for integrated IAM.
Strong cryptography, PKI, and secure elements protect data at rest and in transit, reducing breach risk highlighted by IBM Cost of a Data Breach Report 2024, which cites an average cost of 4.45 million USD per incident. Privacy controls, consent management, and data minimization ensure regulatory alignment. Transparent logging enables oversight and auditability, while regular pen-tests and timely updates maintain operational resilience.
Architected for national-scale throughput with built-in disaster recovery and 99.99% availability SLAs, Safran I&S keeps border and civil services running continuously. Elastic capacity scales to handle election- or migration-driven surges of millions of transactions per day. Proven in dozens of national programs and harsh operational environments worldwide.
Real-time verification can cut identity-fraud incidents by up to 70%, materially lowering loss exposure; streamlined KYC shortens onboarding time by 60–90%, accelerating customer acquisition. Automation trims manual review costs by as much as 80%, while improved UX lifts conversion rates 20–40% and strengthens regulatory compliance.
Safran I&S delivers NIST-validated multimodal biometrics (state-of-the-art FAR/FRR), national-scale throughput with 99.99% SLA, and integrated IAM cutting onboarding 60–90% while reducing fraud up to 70%, lowering exposure versus 2024 average breach cost $4.45M; proven in dozens of national programs.
| Metric | Value |
|---|---|
| NIST FAR/FRR | State-of-the-art |
| Availability SLA | 99.99% |
| Onboarding speed | 60–90% faster |
| Fraud reduction | Up to 70% |
| Avg breach cost (2024) | $4.45M |
Multi-year contracts (typically 5–10 years) include renewal and expansion options to secure long-term state partnerships; dedicated governance boards meet quarterly to align policy and delivery. Performance KPIs and independent audits sustain accountability with regular reporting cycles. Knowledge transfer programs run over 12–36 months to embed operational capability in-country and support sovereign control.
Named account teams provide continuity and domain context with 24/7 coverage and dedicated specialists. Tiered SLAs (P1 ≤1h, P2 ≤4h, P3 ≤24h) align response to criticality. Quarterly reviews (4 per year) track system health, upgrades and risk metrics. Executive sponsors escalate strategic issues to resolution within 48 hours.
Proofs-of-concept validate use cases and performance, with the global digital identity market reaching about $17.5 billion in 2024, underscoring demand for validated solutions. Joint roadmaps align feature development to policy needs and stakeholder KPIs. Rapid prototyping reduces technical and programmatic risk ahead of large rollouts. Pilot learnings feed iterative improvements that inform nationwide deployments.
Structured curricula upskill operators and admins through role-based modules, while certification paths enforce consistent quality and measurable competencies; documentation and sandbox environments accelerate adoption and reduce integration time. Train-the-trainer programs scale expertise across customer sites. Global cybersecurity workforce gap stood at 3.4 million in 2024 (ISC2), underscoring training demand.
Continuous 24/7 monitoring in Safran I&S detects anomalies early; IBM 2024 reports an average breach lifecycle of 277 days and an average cost of $4.45M, underscoring early detection value. Runbooks standardize containment and remediation to speed response and reduce human error. Post-incident reviews harden systems while transparent communications preserve customer trust and support retention.
Multi-year 5–10y contracts with governance boards and KPI audits ensure long-term state partnerships; named account teams deliver 24/7 coverage with tiered SLAs (P1 ≤1h). PoCs and joint roadmaps de-risk rollouts; global digital ID market ~$17.5B (2024). Training/certification scale skills amid a 3.4M cyber workforce gap (2024).
| Metric | 2024 |
|---|---|
| Market size | $17.5B |
| Avg breach cost | $4.45M |
| Cyber gap | 3.4M |
Strategic sales teams manage complex procurement cycles lasting 6–18 months, coordinating stakeholders and compliance for large enterprise and public sector bids. RFP/RFQ responses are tailored to national requirements and certified standards such as ISO/IEC 27001 and Common Criteria. Executive briefings and demos increase stakeholder confidence; contracting aligns delivery, IP and security terms to meet jurisdictional rules.
Joint go-to-market with global system integrators delivers turnkey Safran I&S solutions, bundling hardware, software and services under a single SOW to shorten procurement cycles. Shared reference architectures with integrators accelerate deployments and reduce integration costs. Co-marketing expands reach into regulated sectors where demand is concentrated; global security spending topped about $200 billion in 2024 (Gartner).
Self-serve developer portals, SDKs, and APIs let customers embed Safran I&S biometrics in days, backed by sample code and a sandbox that accelerates proof-of-concept; the global biometrics market reached about $44.6B in 2024. Versioned APIs provide stable contracts and clear migration paths, while built-in analytics (conversion, latency, fraud rates) let customers continuously optimize authentication flows.
In 2024 Safran I&S maintained presence at leading security and government tech conferences, delivering live demos that showcased platform accuracy and throughput, engaging in standards forums to influence technical direction, and converting networking into partnerships and sales pipeline growth.
Regional subsidiaries and local partners enable Safran I&S to navigate country-specific regulations and cultural nuances, improving contract win rates and regulatory compliance. Certified resellers deliver last-mile support and field deployments, while localization of interfaces and documentation enhances UX and reduces integration issues. In 2024 the global identity and access management market exceeded USD 18 billion, underscoring demand for localized identity solutions.
Channels combine strategic sales (6–18 month enterprise/public bids) and joint GTM with system integrators to deliver turnkey, standards-certified solutions; self-serve SDKs/APIs and sandbox enable days-to-PoC, while conferences and local partners drive pipeline, compliance and faster deployments worldwide.
| Channel | Role | 2024 metric |
|---|---|---|
| Strategic sales | Manage complex bids | 6–18 months |
| System integrators | Turnkey deployment | Global security spend ~$200B |
| Developer portals | Rapid PoC | Biometrics market $44.6B |
| Local partners | Compliance & support | IAM market >$18B |
National ID, eID and voter-roll programs—from India’s Aadhaar at ~1.36 billion enrollees (UIDAI 2024) to many 10–100M projects—demand solutions stressing sovereignty, security and inclusivity; World Bank/ID4D notes ~1 billion people still lack ID (2024). Large-scale enrollments require robust deduplication to prevent fraud and reduce costs; programs with multi-decade horizons justify sustainable investment and recurring revenue streams.
Law enforcement and border agencies require AFIS/ABIS capable of searching millions in seconds, mobile ID for in‑field checks and watchlist matching at operational speed; interoperability with INTERPOL’s 194 member network is essential. Chain‑of‑custody and evidentiary standards must be maintained; systems target 99.99% uptime since accuracy and availability directly affect public safety.
Safran I&S targets Financial Services and Payments with KYC, AML and strong customer authentication for onboarding and transaction verification, helping reduce fraud in a market with card fraud losses of about 32.4 billion USD in 2023; regulatory compliance demands auditability and controls, while global digital payment volumes exceeding 10 trillion USD require low-latency, high-throughput identity solutions.
Telecom and digital service providers use Safran I&S for SIM registration, eKYC, and account recovery flows, supporting regulatory compliance in over 100 countries and addressing 5.6 billion unique mobile subscribers in 2024. API-driven verification scales to millions daily while frictionless UX balances security and conversion, improving onboarding completion. Flexible configurations adapt to regional rules, operator SLAs and fraud thresholds.
Safran I&S serves national ID (Aadhaar ~1.36B enrollees 2024; ~1B people unregistered per World Bank/ID4D 2024), law enforcement/ border agencies needing sub-second AFIS/ABIS searches and 99.99% uptime, financial services combating $32.4B card fraud (2023) with KYC/AML, and telco/digital services covering 5.6B mobile subscribers (2024). Integrated enterprise access for utilities/defense drives recurring platform revenue.
| Segment | Key metric (2024) |
|---|---|
| National ID | 1.36B enrollees / ~1B unregistered |
| Telco | 5.6B subscribers |
Sustained R&D in algorithms, firmware and platforms is core to Safran I&S, aligning with Safran group R&D of about €1.1bn in 2023; data acquisition and labeling add material costs (industry labeling often ranges ~$0.10–$1 per label), ongoing tooling/testing/benchmarks drive Opex, and prototyping requires incremental CapEx.
Sensors, optics, secure elements and PCBs drive BOM, often representing over half of unit cost per industry reports in 2024. Factory operations, calibration and QA add overhead typically in the 15–25% range of manufacturing spend. Yield variability (commonly 85–98% for precision ID modules in 2024) affects margin predictability, while dual-sourcing adopted in 2024 reduces supply-disruption risk and improves resilience.
Field engineering, installation, and training are labor-intensive and can drive 30–50% of deployment costs; the global IAM services market was about USD 28 billion in 2024, underscoring service-led spend. Customization and legacy integration commonly extend timelines by weeks to months, while travel, logistics, and spares add roughly 8–12% to project budgets. PMO oversight and compliance reviews are mandatory and add fixed governance costs.
Data centers, HSMs, and secure networking drive recurring Opex for Safran I&S; hardware and colocation rentals plus managed HSM services are core line items, while monitoring, patching, and incident response are continuous labor and tooling costs, with SOC analyst median U.S. pay around 88,000 USD in 2024. Licensing for databases and middleware materially increases software spend, and DR sites plus HA architectures typically raise infrastructure costs by roughly 20–40%.
Sustained R&D (Safran group R&D ~€1.1bn in 2023) plus data labeling ($0.10–$1/label) and prototyping drive CapEx/Opex. BOM (sensors, optics, secure elements) often >50% of unit cost; yields 85–98% affect margins. Services (installation, training) can be 30–50% of deployment; IAM market ~USD28bn (2024). Compliance, HSMs, DR/HA add recurring costs (+20–40%).
| Item | 2024/2023 Metric |
|---|---|
| Group R&D | €1.1bn (2023) |
| Label cost | $0.10–$1/label |
| Yield | 85–98% |
| IAM market | USD28bn (2024) |
| SOC pay | ~USD88k/yr (2024) |
Revenue mixes sensors, scanners, enrollment kits and platform fees, with Safran I&S reporting approximately €1.5bn revenue in 2024 for identity solutions, driven by hardware units and platform contracts. Perpetual and term licenses coexist, with term licenses growing faster as recurring revenues rose ~18% year-on-year in 2024. Bundled hardware-software offers lift average deal size by ~20–30%, while paid upgrades and module add-ons generate steady follow-on sales.
Multi-year government contracts for national ID and border systems typically span 5–10 years, securing large-scale revenue for Safran I&S and enabling predictability in program planning. Milestone payments tied to delivery phases de-risk cash flow timing and improve working capital management. Ongoing O&M contracts generate steady recurring cash flow, often representing 20–30% of lifecycle revenue. Change orders commonly expand scope by 5–15% over contract life, boosting aftermarket revenue.
Cloud verification and digital onboarding are billed per transaction (market ranges in 2024 commonly $0.25–$2.00 per check), with tiered plans that align price to volume and features and typically lift ARPU by 20–40% in 2024 benchmarks. SLAs and compliance options command premiums (often 15–30% higher fees). Elastic capacity supports spiky demand, enabling cost-efficient scaling during peak verification windows.
Maintenance, support, and managed services generate recurring annual support revenue (≈18% of license ARR in 2024) via patches, feature updates and SLA-bound remote or on-site interventions (typical response 4–24h). Predictable renewals (≈85% average in 2024) improve revenue visibility; premium tiers (≈+35% price uplift) add 24/7 coverage and advanced analytics.
Licensing of biometric algorithms and SDKs to third parties drives recurring revenue and supports OEM agreements that generate per-device royalties; in 2024 the global biometrics market was estimated at about $47 billion, increasing addressable demand for such licenses. Certification-ready components reduce time-to-market for partners, while co-innovation deals often include revenue sharing and joint-IP monetization.
Revenue mixes hardware, software and services with Safran I&S identity revenue ≈€1.5bn in 2024; recurring revenue grew ≈18% YoY and bundles lift deal size ~20–30%. Multi-year government contracts (5–10y) plus milestone payments and O&M (≈20–30% lifecycle; maintenance ≈18% license ARR) drive predictability; renewals ≈85%. Cloud verification priced $0.25–$2.00/check; premium SLAs +15–30% fees.
| Metric | 2024 Value |
|---|---|
| Identity revenue | €1.5bn |
| Recurring growth | ≈18% YoY |
| Maintenance share | ≈18% license ARR |
| Renewal rate | ≈85% |
| Per-check price | $0.25–$2.00 |


