
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
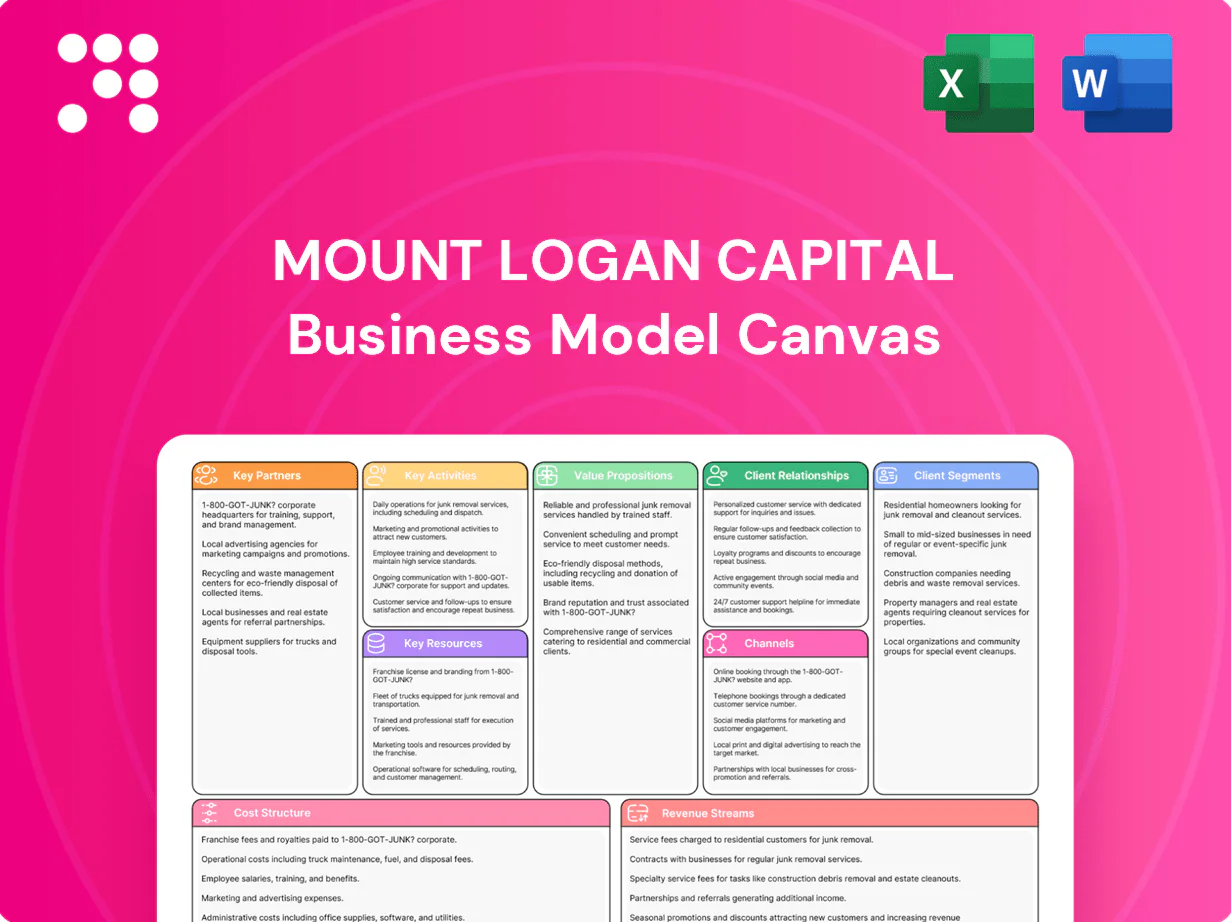
Explore Mount Logan Capital’s strategic playbook with our concise Business Model Canvas—three to five sentences won’t cut it, so get the full version for the complete picture. The downloadable Canvas maps value propositions, revenue streams, partnerships and cost structure in editable Word and Excel. Ideal for investors, consultants, and founders seeking actionable, ready-to-use insights to replicate and benchmark success.
Large pensions, endowments, and sovereigns—holding roughly $70–85 trillion combined in 2024—provide committed capital across credit, real assets, and opportunistic strategies, enabling fund launches and co-investments in deals often exceeding $200–500 million; their long-duration capital stabilizes deployment cadence and strategic LP feedback shapes product design and reporting standards.
Commercial banks, specialty finance firms and direct lenders supply primary deal flow and financing to Mount Logan Capital, with global private credit AUM near $1.5 trillion in 2024 (Preqin). They co-lead club deals, underwritings and provide warehouse lines for leveraged loans and asset-backed strategies, improving pricing and structure through pipeline access. These partners also enable refinancing and exit execution via syndicated sales or CLO placements.
Experienced developers and property managers provide on-the-ground execution across asset classes, originating transactions and managing repositioning to drive targeted NOI uplifts typically in the 3–7% annual range for value-add deals. Partnerships align incentives via promote structures commonly allocating 20–30% carried interest after an 8% preferred return and layered performance hurdles. Local market knowledge reduces underwriting variance and capex overruns, shortening stabilization timelines and preserving investor IRRs.
Advisors, administrators, legal counsel, tax advisors, and auditors secure governance, NAV integrity, and regulatory compliance for Mount Logan Capital, supporting complex credit documentation, securitizations, and cross-border structures; in 2024 asset managers oversee over $100 trillion AUM, increasing demand for robust controls. Strong controls boost investor confidence and due diligence outcomes, while standardized processes reduce operational friction and can shorten time-to-close materially.
Placement agents and investment-consultant gatekeepers expand Mount Logan Capital’s institutional reach, handling RFPs, database listings and consultant ratings that drive mandate awards. Their diligence and brand endorsement commonly shorten sales cycles, while fee benchmarking (placement fees typically 1–2%) and consultant feedback refine product-market fit and pricing.
Large pensions, endowments and sovereigns provide long-duration capital ($70–85T combined in 2024) enabling fund launches and >$200–500M co-invests. Banks, specialty finance and direct lenders (private credit AUM ~$1.5T in 2024) supply deal flow, warehousing and refinancing. Developers, ops partners and service providers drive 3–7% NOI uplifts and ensure governance, while placement agents shorten fundraising (fees 1–2%).
| Partner | Role | 2024 metric |
|---|---|---|
| Pensions/sovereigns | Committed capital | $70–85T |
| Banks/credit | Financing/deals | $1.5T AUM |
| Developers/ops | Execution/NOI | 3–7% uplift |
| Placement agents | Distribution | Fees 1–2% |
 Detailed Word Document
A comprehensive, pre-written Business Model Canvas tailored to Mount Logan Capital, covering all nine BMC blocks with detailed customer segments, channels, value propositions, revenue streams and cost structure; includes competitive advantages, SWOT-linked insights and validation data—polished for presentations, investor pitches and strategic decision-making.

 Customizable Excel Spreadsheet
Condenses Mount Logan Capital’s strategy into a clean, editable one-page Business Model Canvas that saves hours of formatting, makes boardroom-ready summaries fast, and enables shareable, collaborative iteration for quicker decision-making.
Mount Logan Capital builds and leverages an extensive sponsor, lender, and advisor network to access privately negotiated debt, equity, and real estate opportunities, tapping a private credit market that exceeded 1 trillion USD in AUM by 2024. Continuous origination ensures pipeline depth while screening aligns each opportunity with mandate fit and strict risk budgets. Preference for bilateral and off-market situations secures a measurable pricing advantage and faster execution.
Perform rigorous credit, collateral, market and legal diligence, stress-testing cash flows and modeling downside cases including covenant breaches and recovery scenarios; target downside haircuts consistent with industry practice and a minimum 1.2x debt service coverage. Structure pricing, covenants and security to optimize risk-adjusted returns, targeting 12%+ IRR net of fees. Align incentives via upfront and performance fees, ratchets and clear performance triggers tied to cash-on-cash and covenant remediation milestones. Use market data and loan-level analytics to calibrate expected recovery and loss given default assumptions for 2024 portfolio underwriting.
Monitor KPIs, covenants and asset performance post-close with monthly reporting and immediate re-underwrite within 30 days after material events; execute value-creation plans to target cash yield uplifts. Hedge rates, spreads and FX as needed within policy, typically hedging up to 80% of marked exposures. Recycle capital via refinances, sales and workouts, targeting 15–25% portfolio turnover annually.
Mount Logan markets funds and bespoke SMAs to institutions and family offices, leveraging 2024 demand as institutional alternative allocations rose to about 12% and boosted appetite for customized exposure. The team delivers transparent reporting, audited track records and attribution analyses, hosts quarterly updates, annual AGMs and co-invest pipelines, and manages DDQs, due diligence and consultant processes.
Maintain a robust middle/back-office with strict NAV and cash controls, ensuring daily reconciliation, exception management, and timely investor reporting; ensure regulatory filings, policies, and annual audits meet jurisdictional standards and SEC/ESMA expectations; manage data integrity via valuation committees and vendor oversight while institutionalizing processes for scale and reliability.
Mount Logan originates off-market private credit and real estate deals via a 1T+ USD sponsor network (2024), targeting 12%+ net IRR and 1.2x minimum DSC; hedges up to 80% of exposures and targets 15–25% annual turnover. Rigorous diligence, covenant structuring and active asset management drive recoveries and liquidity recycling.
| Metric | 2024 |
|---|---|
| Private credit AUM | 1T+ USD |
| Target IRR | 12%+ |
| Turnover | 15–25% |
The preview you see is the exact Mount Logan Capital Business Model Canvas you'll receive after purchase — not a mockup. This same editable, professional document is delivered in full upon order, formatted for immediate use in Word and Excel. No hidden pages or placeholders: what you see is what you'll download, ready to edit, present, or share.
Analysts, portfolio managers, and underwriting specialists with deep sector expertise provide Mount Logan Capital a measurable edge in sourcing and structuring opportunities. Their judgement in complex credit and real estate scenarios is central to risk-adjusted returns. Track records across cycles reinforce credibility and support investor confidence. Strong team cohesion accelerates execution and improves decision quality.
Corporate balance sheet capital at Mount Logan funds seed investments and warehousing, while LP commitments provide scale and fee durability; private credit AUM exceeded $1.5 trillion in 2024, underscoring market capacity. Co-invest capacity raises win rates in competitive processes by enabling larger, tailored bids. Flexible capital supports opportunistic timing and bespoke deal structures, reducing execution risk.
Longstanding ties with lenders, sponsors and operators give Mount Logan Capital proprietary access to deal flow and first-look opportunities; private credit AUM exceeded 1 trillion USD by 2024, amplifying the value of relationship-driven origination. Repeat counterparties reduce friction and due diligence uncertainty, lowering execution risk and improving pricing. Relationship equity speeds syndication and exits, enabling quicker realizations and tighter terms from familiar sponsors.
Data, analytics, and a modern tech stack power Mount Logan Capital’s credit models, market data feeds, and underwriting tools to speed decisions and improve accuracy; workflow systems maintain audit trails and compliance; portfolio analytics support risk aggregation and hedging; secure, SOC 2–aligned infrastructure with 99.99% uptime targets protects sensitive deal information in 2024.
Regulatory licenses (SEC registration, FCA/ESMA compliance) enable Mount Logan Capital to operate across targeted jurisdictions; as of 2024 these frameworks remain central to market access. A verifiable performance history supports fundraising and consultant approvals, while recognized governance and ESG practices broaden allocator appeal and brand equity attracts talent and partners.
Deep-sector investment professionals, proprietary relationships, flexible balance-sheet and LP capital, plus a modern analytics and SOC 2-secure tech stack drive Mount Logan Capital’s execution edge. Private credit AUM exceeded 1.5 trillion USD in 2024, supporting scale and co-invest capacity. Regulatory registrations (SEC, FCA/ESMA) and audited track record underpin market access and allocator confidence. These resources reduce execution risk and accelerate realizations.
| Metric | Value (2024) |
|---|---|
| Private credit AUM | >1.5 trillion USD |
| Security standard | SOC 2, 99.99% uptime target |
| Licenses | SEC, FCA/ESMA |
Mount Logan gives investors access to negotiated credit and real estate not typically public, tapping off-market deal flow that industry studies show can yield price concessions of 5–10% and superior protective covenants. Reduced competition in bilateral negotiations tends to produce stronger documentation and senior-secured structures, improving recovery prospects versus broadly syndicated markets. This privately sourced deal pipeline supports enhanced downside mitigation and differentiated return profiles.
Constructs diversified portfolios across public and private debt, leveraged loans, and real assets with emphasis on seniority, collateral, and cash yield to enhance stability. Dynamic allocation adjusts to rate and credit cycles amid a 2024 Fed funds range of 5.25–5.50%. Targets consistent distributions of 6–8% while prioritizing capital preservation.
Invest alongside clients to align incentives, deploying firm capital alongside LPs to ensure shared upside and downside; in 2024 Mount Logan Capital continued this practice to signal conviction. Seed and warehouse deals with balance-sheet capital to accelerate deployment and de-risk execution. Offer co-investments to lower fee loads and concentrate capital in highest-conviction positions. These actions visibly demonstrate commitment to strategy execution.
Mount Logan engages in hands-on monitoring with covenants and detailed operational plans, employing structuring, hedging and workout capabilities to protect capital; private credit AUM exceeded $1 trillion by 2024, highlighting market scale. We extract value via refinances, asset sales and sponsor negotiations to realize recoveries and target attractive risk-adjusted returns, not just headline IRR.
Mount Logan offers SMAs and tailored sleeves to align allocations and liabilities, with reporting designed for T+1 environments (post-May 28, 2024 settlement). We deliver granular look-through holdings, attribution and audit-ready disclosures meeting GIPS and SEC/consultant standards, and provide timely, candid communications to accelerate decision-making.
Mount Logan sources off-market credit and real estate yielding 5–10% price concessions with stronger covenants, driving downside protection and differentiated returns. Portfolios prioritize seniority, collateral and cash yield targeting 6–8% distributions while adjusting to a 2024 Fed funds range of 5.25–5.50%. Firm capital alignment, co-invests and warehouse capacity accelerate deployment and signal conviction.
| Metric | 2024 Data |
|---|---|
| Off-market concession | 5–10% |
| Target distribution | 6–8% |
| Fed funds | 5.25–5.50% |
| Private credit AUM | >$1T |
| T+1 reporting live | post-May 28, 2024 |
Dedicated IR and PM access ensures continuous dialogue with institutional clients, enabling quarterly reviews, site visits and portfolio deep dives to align strategy and risk. Rapid responses to information requests and operational due diligence maintain transparency and shorten decision cycles. Relationship continuity is preserved through market cycles by consistent account teams and proactive communication, supporting long-term trust and capital retention.
Collaborate on pipeline sharing and customized structures, leveraging co-invest fee ranges of 0–1% and SMA advisory fees typically 0.5–1.0% to align economics with scale and governance preferences. Offer expedited approvals within 48–72 hours for time-sensitive transactions to preserve deal momentum. Build long-term trust and preferential access through repeat allocations and joint underwriting commitments.
Transparent, data-rich reporting delivers detailed positions, cash flows and KPI dashboards with risk metrics, 95% VaR, stress-test scenarios (including 30% equity shock) and attribution across strategies. Outputs are XBRL/CSV-ready for consultant databases and 2024 regulatory reporting. Proactive monthly disclosure and exception alerts reduce surprises for investors and auditors.
Mount Logan delivers quarterly credit outlooks, real estate trend reports and thematic research, translating 2024 market signals—10-year Treasury average ~4.2%—into actionable allocation and pacing guidance. We hosted 12 webinars and roundtables with operators and originators in 2024 to bridge structuring complexity and execution. Clients receive concise takeaways to navigate allocations and pacing across credit cycles.
Mount Logan coordinates capital calls, distributions and secondary options to align with client liquidity windows and risk budgets, leveraging processes proven as global private equity dry powder reached about $2.7 trillion in 2024 to smooth timing and optionality. The team guides re-ups and portfolio construction, pacing commitments across 6–18 month liquidity cycles and reducing operational frictions across vehicles.
Dedicated IR/PM teams provide quarterly reviews, 48–72h expedited approvals and proactive communication to retain capital through cycles. Transparent XBRL/CSV-ready reporting, 95% VaR and stress tests (30% equity shock) shorten due diligence. 12 webinars (2024) and thematic guidance tied to 10yr Treasury ~4.2% align pacing and allocations.
| Metric | Value (2024) |
|---|---|
| 10yr Treasury | ~4.2% |
| Webinars/Roundtables | 12 |
| Co-invest fee | 0–1% |
| SMA advisory fee | 0.5–1.0% |
| Global PE dry powder | $2.7T |
| Expedited approvals | 48–72h |
PMs and IR teams engage CIOs, portfolio managers and ODD teams directly to win institutional business. Target RFPs and bespoke mandates focused on mandates above $50m, with emphasis on tailored terms and fee schedules. Build relationships through regular meetings and on-site diligence visits to asset locations. Maintain CRM-driven coverage cadences with weekly touches and quarterly on-site reviews.
Engage investment consultants (eg Preqin, eVestment) for ratings and buy lists, ensuring Mount Logan appears on consultant shortlists used by institutional investors in 2024. Maintain up-to-date profiles in major institutional databases and align pitchbooks with consultants’ RFP frameworks and scoring criteria. Leverage consultant recommendations and documented 2024 shortlist placements to convert visibility into mandates.
Partnering with capital introduction and placement agents expands allocator reach—often connecting funds to over 1,000 institutional allocators globally—and delivers faster fundraising momentum through established pipelines. Their packaged diligence, standardized messaging and investor materials compress marketing timelines, while industry success fees typically range 1–2.5% of capital raised. Aligning incentives via milestone-based fees limits upfront cost and ties pay to closings.
Present Mount Logan Capital’s strategy at conferences to reach institutional allocators, host quarterly webinars on credit and real estate (2024 webinar benchmark attendance ~50% of registrants) and publish whitepapers to evidence proprietary models, driving trust and differentiation; target conversion from content to qualified leads using gated assets and follow-up cadences (typical whitepaper lead conversion range 1–3% in 2024 benchmarks).
Maintain a professional website detailing strategy and case studies, with investor-grade pages and downloadable track records; in 2024, 86% of investors expect digital disclosures. Use secure investor portals for encrypted reporting and document exchange, enabling audit trails and MFA access. Track engagement analytics (CTR, time on page, portal logins) to refine outreach and automate subscriptions, delivering updates and e-deliverables.
Direct PM/IR outreach targets RFPs >$50m with CRM cadences and quarterly on-site diligence; placement agents used with success fees 1–2.5% to accelerate closes. Engage consultants and databases to secure 2024 shortlists; webinars (50% attendance), whitepapers (1–3% lead conv.), and 86% investor digital disclosure expectation drive digital+events mix.
| Channel | KPI | 2024 Benchmark |
|---|---|---|
| Direct IR | Target size | >$50m |
| Webinars | Attendance | ~50% |
| Whitepapers | Lead conv. | 1–3% |
| Placement agents | Fee | 1–2.5% |
| Digital | Investor expect. | 86% |
Pension funds and sovereign wealth managers, which held roughly $68 trillion in combined AUM in 2024, seek long-duration, income-oriented alternatives with strong governance and downside protection. They prioritize scalable platforms that can absorb large allocations and demand robust reporting and consultant alignment. Many pursue co-invests and fee-efficient structures to lower total costs.
Endowments and foundations pursue total-return objectives and diversification, targeting long-term real returns (typically aiming for 6–8% nominal) while tolerating measured illiquidity—often agreeing to 5–10 year private investment lockups—to capture alpha. In 2024 many large endowments increased allocations to alternatives, emphasizing manager edge, alignment of incentives, and exclusive access. They favor concentrated, high-conviction co-investments to lower fees and boost net returns.
Insurance companies seek capital-efficient income that complies with NAIC solvency regimes, typically targeting RBC ratios comfortably above 300% and favoring assets that optimize capital charges. They prefer senior secured and structured credit with low volatility and high investment-grade exposure (roughly 85–90% of bond portfolios). ALM matching and ratings awareness drive portfolio selection to limit duration and credit mismatch. Predictable cash flows and strong covenants are prioritized to support reserve adequacy and statutory liquidity.
Family offices and HNW clients seek differentiated private deals with strong cash yield, valuing transparency, co-invest access and flexible liquidity; many prioritize tax-efficient structures and estate planning while preferring direct communication with decision-makers (Campden Wealth estimates ~7,300 single-family offices globally, 2024).
Fund-of-Funds and OCIOs aggregate allocations across multiple client mandates, leaning on stringent diligence; the OCIO market reached roughly $2.2 trillion AUM in 2024, intensifying demand for repeatable, capacity-driven processes. They require standardized data and operational excellence to onboard and scale commitments rapidly after approval.
Pension/sovereign ($68T AUM 2024) seek long-duration, scalable income with fee-efficient co-invests. Endowments/foundations target 6–8% nominal returns and accept 5–10y lockups for diversification. Insurers favor capital-efficient, ~85–90% investment-grade credit; family offices (~7,300 SFOs 2024) want yield, co-invests and tax-efficient structures; OCIOs ($2.2T 2024) demand standardized data and repeatable processes.
| Segment | Key metric 2024 |
|---|---|
| Pension/Sovereign | $68T AUM |
| Endowments | 6–8% target |
| Insurance | 85–90% IG |
| Family Offices | ~7,300 SFOs |
| OCIO | $2.2T AUM |
Base salaries at Mount Logan span roughly $80k–$120k for analysts, $120k–$200k for associates and $250k–$600k+ for senior investment/ops roles, with bonuses commonly 50–150% of base; carried interest typically ranges 10–20% to align long-term returns. Competitive pay is critical to retain specialized credit and real estate expertise. Performance-linked incentives tie compensation to fund and asset-level outcomes. Recruiting, onboarding and training add roughly $1,200 per employee annually (2024).
Third-party reports and consultants typically run $5k–$50k per deal in 2024, with site inspections and travel adding $1k–$15k; legal diligence and specialized underwriting commonly cost $20k–$150k. Travel for sourcing and portfolio oversight drives variable line items tied to geography. Overall costs scale roughly linearly with deal volume and nonlinearly with complexity.
Fund administration fees, audit engagements and tax filings drive fixed fund overheads—typical 2024 market ranges: administration $25k–$250k/year, audits $20k–$150k/engagement and tax filings $5k–$30k/jurisdiction. Regulatory compliance and cross‑jurisdiction filings (AML, AIFMD/SEC/FSRA notifications) add material recurring costs, often tens of thousands annually for multi‑jurisdiction funds. Vehicle setup and maintenance for funds and SPVs incur one‑time setup fees of $1k–$15k and ongoing servicing $2k–$20k/year, essential to deliver institutional‑grade operations.
Mount Logan allocates significant spend to market data, risk systems and portfolio tools for real-time pricing and analytics; enterprise cybersecurity and secure data rooms protect transactions—IBM reports the average 2024 data breach cost at $4.45 million. Hardware, cloud capacity and SaaS subscriptions are ongoing operating fees that enable scalability and operational control. Vendor mix includes Bloomberg, Refinitiv and specialist risk vendors.
Financing and transaction expenses include warehouse lines typically priced at SOFR plus 200–350 bps in 2024, hedging costs for interest-rate swaps and caps often adding 20–100 bps, and interest expenses driven by prevailing short-term rates near 5.25–5.50% in 2024; deal closing fees, ratings and trustee costs for structured deals range from tens to low hundreds of thousands of dollars, with syndication and placement fees commonly 0.5–2.0%, all actively managed to protect net returns and target double-digit net IRRs.
Compensation (base + bonus + carry) is the largest cost, with 2024 ranges: analysts $80–120k, associates $120–200k, seniors $250–600k+, bonuses 50–150% and carry 10–20%. Due diligence, legal and travel scale per deal: due diligence $5–150k, travel $1–15k. Fund admin, audit, compliance and IT/security add recurring fixed overheads.
| Cost Type | 2024 Range | Notes |
|---|---|---|
| Compensation | $80k–$600k+ | bonuses 50–150%, carry 10–20% |
| Diligence/Legal | $5k–$150k | per deal |
| Admin/Audit/Tax | $5k–$250k | fund-level |
| Financing | SOFR+200–350bps | hedges 20–100bps |
Management fees at Mount Logan Capital are charged as recurring percentages on committed or invested capital, typically in the industry range of 1–2% annually on private capital vehicles, creating predictable cash flow. These fees provide operating leverage and business stability as fixed revenue scales faster than incremental operating costs. Tiered fee schedules reward scale by reducing rates as assets grow, aligning incentives and lowering client costs. Fees are applied consistently across pooled funds and separately managed accounts (SMAs).
Incentive allocations at Mount Logan Capital mirror market practice, typically 20% carried interest with an 8% preferred-return hurdle as reported by Preqin 2024. These fees are paid only on realized returns above the hurdle. Structures align manager and investor outcomes by tying pay to excess performance. Carry crystallizes on exits or periodic realizations and is subject to high-water marks and clawbacks where applicable.
Arrangement, structuring and underwriting fees typically range 1–3% of deal size for origination and 0.5–1.5% for underwriting, compensating sourcing and closing effort; fee splits with LPs are common and disclosed in offering documents. In 2024 private credit norms showed these fee lines materially boost gross-to-net as platform scale exceeds roughly $500m AUM, improving margin leverage.
Investment and interest income from Mount Logan Capital’s balance-sheet coinvestments and warehousing generates incremental returns via interest, dividends and realized gains, reinforcing the firm’s conviction and track record while smoothing fee cyclicality.
Ongoing monitoring, servicing and asset management fees provide steady non-performance revenue, typically charged to portfolio companies or vehicles for oversight, reporting and operational involvement; in 2024 global private equity AUM was about 6.3 trillion USD and monitoring fees commonly range 0.5–1.0% of AUM while servicing fees often run 50k–250k USD per company annually.
Management fees: recurring 1–2% AUM, tiered by scale, drive predictable cash flow. Performance fees: 20% carry with an 8% hurdle (Preqin 2024), crystallized on realizations. Transaction fees: origination 1–3%, underwriting 0.5–1.5%; monitoring 0.5–1% AUM and servicing 50k–250k/company. Balance-sheet coinvests and warehousing add interest/dividend gains and smoothing.
| Revenue Type | 2024 Benchmarks |
|---|---|
| Management Fee | 1–2% AUM |
| Carry | 20% / 8% hurdle |
| Origination/Underwrite | 1–3% / 0.5–1.5% |
| Monitoring/Servicing | 0.5–1% AUM / 50k–250k |


