
Digital download
Access the files immediately after checkout.
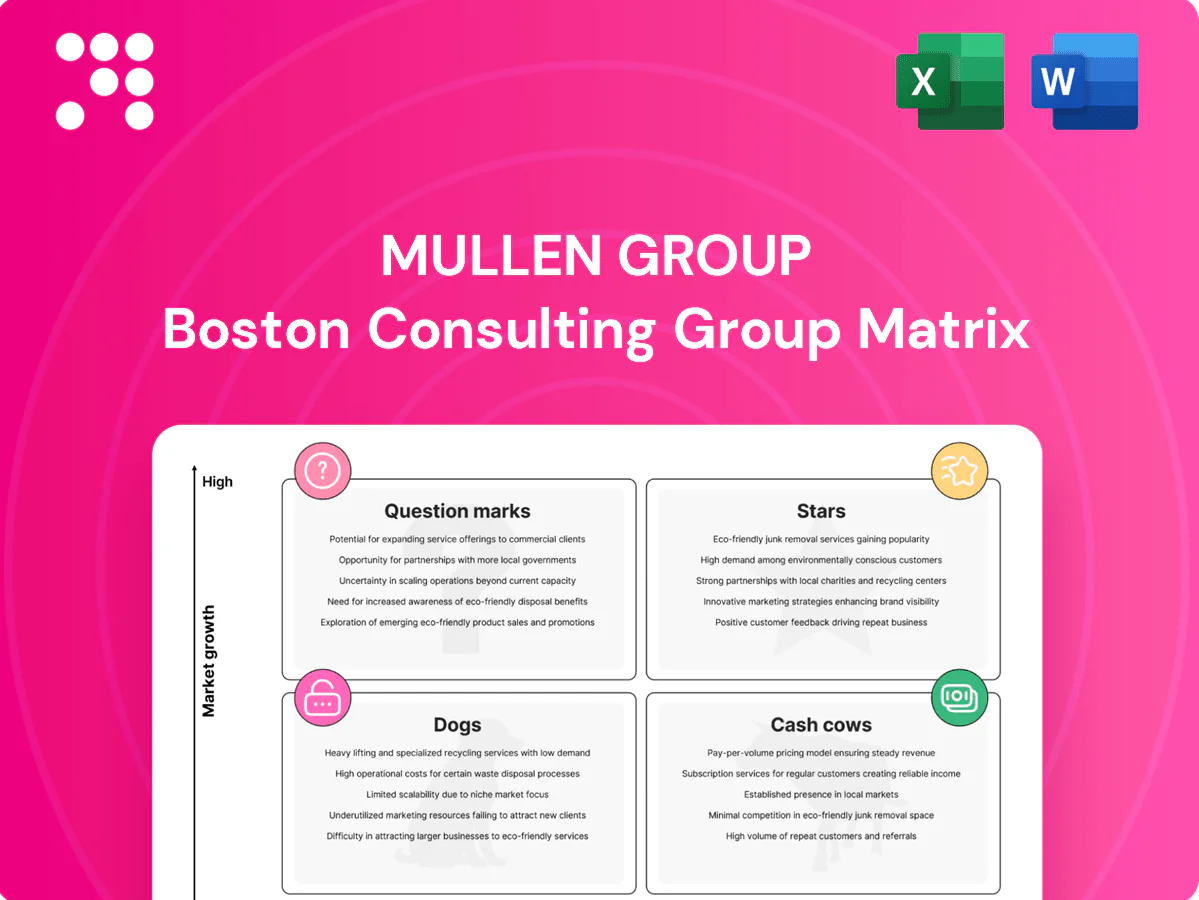
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
The Mullen Group BCG Matrix snapshot shows where its services sit—who’s winning market share, who’s funding growth, and where risks hide. This preview teases quadrant placements; buy the full BCG Matrix for the definitive breakdown, data-led recommendations, and ready-to-use Word + Excel files to act fast and confidently.
Specialized freight and heavy haul is a Star for Mullen Group with dominant market share in high-barrier, niche corridors across Western Canada and energy sectors; project-driven demand and infrastructure spend accelerated loads in 2024. Mullen’s deep asset base and control over pilot, escort and multi-axle gear win complex, high-margin contracts despite heavy capital use. Continued capacity additions, tech-enabled dispatch and targeted sales sustain utilization and justify the margin profile.
US–Canada cross-border trade exceeded US$1.1 trillion in 2023, with premium time-definite freight growing as shippers pay for certainty; Mullen’s safety, compliance and secure protocols position it to capture higher-yield lanes. The company must keep investing in drivers, refrigerated and high-value trailers and real-time visibility tools to sustain service. Hold share aggressively—stabilizing lanes can convert Stars into cash cows.
Parcel-heavy, fast-growing e-commerce (global sales $5.7 trillion in 2022) demands reliable regional networks and warehouses; Mullen Group’s asset-based, regional footprint targets errors where service failures cost brands in returns and loyalty. Growth requires cash for facilities, tech integrations and peak staffing, driving capex and working capital pressure. Scaling dense routes in key metros compounds route efficiency and lowers unit costs as parcel density rises toward projected industry volumes.
Shippers are consolidating providers and want one throat to choke; Mullen’s blended asset + 3PL model captures sticky, multi-year programs and cross-sell wins. Onboarding and systems integrations are costly up front, but investments in control towers and analytics convert into annuity-like cash as volumes normalize. Global 3PL market was about US$1.3 trillion in 2023 with ~6% projected CAGR to 2028.
Food, pharma, and specialty chemical cold-chain flows are expanding and stringently regulated; reliability and compliance are key differentiators where Mullen’s quality focus aligns with customer needs. Equipment and monitoring tech are capital intensive, so Mullen should target long-term contracts with predictable volumes to justify capex. The global cold-chain logistics market grew materially through 2024, reinforcing Stars status.
Specialized heavy-haul and regional asset-backed logistics are Stars for Mullen Group, capturing high-margin energy and project lanes as US–Canada trade topped US$1.1 trillion in 2023. The global 3PL market was ~US$1.3 trillion in 2023 with ~6% CAGR to 2028, supporting program wins and annuity cashflow. Cold-chain and e-commerce tailwinds in 2024 reinforce capital-light scaling opportunities.
| Metric | 2023/2024 | Implication |
|---|---|---|
| US–Canada trade | US$1.1T (2023) | Higher cross-border premium lanes |
| 3PL market | US$1.3T (2023) | Program growth, stickiness |
 Detailed Word Document
Clear BCG Matrix breakdown of Mullen Group units with strategic recommendations to invest, hold or divest, and trend-based risks.

 Customizable Excel Spreadsheet
One-page Mullen Group BCG Matrix pinpointing cash cows, stars and pain points for fast strategic fixes.
Regional LTL in mature Canadian corridors represents a cash cow for Mullen Group with a defensible market share in core lanes, stable demand from retail and manufacturing shippers, and strong density economics that lower unit costs. The network and brand are established, pricing discipline sustains yields, and incremental capex is limited to fleet refresh and terminal upkeep. Continuous improvement initiatives and selective rate management enable margin preservation. Operations focus on milking steady cash flow while optimizing productivity.
Dedicated contract carriage provides Mullen with multi-year customer contracts (typically 3–7 years) that secure predictable volumes and revenue visibility. High asset utilization—often exceeding 90%—and steady driver hours drive margin expansion. Minimal promotion is required as service levels and on-time performance retain contracts. Route optimization and rotating aging units into sale-lease or trade programs squeeze additional free cash.
Bulk and general commodity trucking on Mullen Group core routes sits in mature lanes with consistent reloads and limited volatility, generating steady cash flow in 2024. Scale (fleet >3,000 units) drives cost advantage and dependable cash generation. Growth is modest; focus is on yield improvement and a 100–200 bp margin lift via equipment reliability and incremental automation.
Established warehousing in key hubs shows leased/owned facilities at healthy occupancy, supporting recurring storage and handling fees that underpin dependable cash flows; CBRE reported Canadian industrial vacancy near 1.6% in 2024, keeping demand and pricing strong.
Operating expenses remain manageable through disciplined processes and labor productivity programs, while incremental racking and WMS tweaks can raise throughput 10–20% without major capital outlays, preserving cash generation.
In-house shops sustain high fleet uptime and keep cost per mile predictable by centralizing repairs and preventative maintenance, while selective external work generates incremental margin with minimal selling effort; the maintenance market is mature, so focus is on margin retention rather than aggressive growth, and standardized PM schedules and inventory protocols lock in steady operating savings.
Regional LTL, dedicated contracts, core bulk trucking and warehousing generate stable free cash flow for Mullen in 2024: fleet >3,000, utilization ~90%+, industrial vacancy ~1.6%, contracts 3–7 yrs. Focus on yield, 100–200 bp margin upside, 10–20% throughput gains via WMS/racking, limited capex beyond fleet refresh.
| Metric | 2024 |
|---|---|
| Fleet | >3,000 units |
| Utilization | ~90%+ |
| Industrial vacancy | 1.6% |
| Contract length | 3–7 yrs |
| Margin upside | 100–200 bp |
| Throughput upside | 10–20% |
The file you're previewing is the exact Mullen Group BCG Matrix report you'll receive after purchase. No watermarks or demo content — just a fully formatted, analysis-ready document tailored for strategic clarity. After buying, the same clean, editable file is immediately downloadable and ready to present or print. Crafted by strategy pros, it slots straight into your planning or board materials.
Legacy long-haul TL on commoditized lanes shows low market share, acute rate pressure and little differentiation, driving operating leverage to the brink. Driver scarcity (~20,000 short in Canada, 2024) and fuel swings (avg diesel ~CAD 1.76/L in 2024) erode already thin margins. Cash ties up in receivables with limited payback, so consider exit, brokering overflow, or folding lanes into higher-yield networks.
Underutilized remote depots show light volumes with high fixed facility and equipment costs eroding margins, while market growth in these corridors is muted and competitors are entrenched. Capital sits idle in parked trailers and surplus yard space, tying up working capital and reducing ROIC. Consolidate routes, sublease excess space, or divest marginal depots to release cash and improve fleet utilization.
Non-core spot brokerage acts as a price-taker facing single-digit gross margins in 2024, high customer churn and minimal operational leverage. With market share well below national and digital brokers, it consumes working capital and delivers inconsistent yield quarter-to-quarter. Strategic options: scale via tuck-in acquisitions to rebuild density or orderly wind down to stop cash burn.
Paper-heavy, manual workflows act like a product for Mullen Group with low return and high drag: Gartner 2024 found 64% of organizations still rely on paper-based processes, driving higher error rates, delays, and admin costs that stack up against margins. These flows don’t win customers and burn operational time; sunset and replace with standardized digital flows (RPA/ERP) to cut cycle times and reduce rework.
Ad hoc oilfield peaks on marginal pads sit squarely in Dogs: volatile, low-share, low-growth demand with crowded vendor lists; Baker Hughes U.S. rig count averaged about 600 in 2024, underscoring limited expansion. Mobilization costs often consume margins on small jobs, cash becomes tied up with little visibility, and ROI on standalone pads is typically negative. Prioritize contracted multi-pad programs or walk away.
Legacy long-haul TL, underutilized depots, spot brokerage and ad hoc oilfield pads show low share/low growth with margin pressure: driver shortfall ~20,000 Canada (2024), diesel ~CAD 1.76/L (2024), Baker Hughes rig count ~600 (2024), Gartner: 64% paper workflows (2024). Exit, consolidate, digitize or contract to stop cash burn.
| Item | 2024 Metric | Action |
|---|---|---|
| Drivers | −20,000 | Consolidate routes |
| Diesel | CAD 1.76/L | Fuel surcharges |
| Rig count | ~600 | Prefer contracts |
US expansion via targeted acquisitions offers high-growth exposure to a market whose 2024 nominal GDP was about USD 28.6 trillion, yet Mullen Group's share remains low in many states. Integration of systems, culture, and operations is a heavy lift and can raise short-term costs. Successful deals could unlock cross-border density and routing synergies. Invest only when targets bring defensible niches and margins; otherwise pass.
Market for EV and alternative-fuel fleets is expanding rapidly while Mullen Group’s deployed share remains small, making the segment a classic Question Mark in the BCG matrix.
Capex is high and charging/refueling infrastructure uneven, with returns still uncertain; customers are increasingly demanding greener lanes and ESG reporting.
Recommend doubling down selectively where incentives, dense routes and depot charging exist; pursue pilots focused on high-utilization lanes and measure economics before scaling.
Shippers increasingly demand control towers and KPI-rich dashboards; building integrated visibility and data products positions Mullen Group to capture rising demand while current penetration remains low. Mullen reported CAD 1.47B revenue in 2024, allowing investment in productization and tight integrations. Prioritize productized control-tower modules that differentiate bids and lift retention through measurable KPIs and SLA-linked dashboards.
Cross-border cold-chain is a high-growth vertical—the global cold-chain market was estimated at about 260 billion USD in 2023 with ~7.5% CAGR—requiring tight compliance (temperature control, customs, food safety). Mullen’s share remains emerging versus incumbents; early deployment demands heavy capital and SOP investments. Invest selectively in lanes anchored by strategic customers with multi-year contracts to de-risk scale-up.
Mexico–US–Canada nearshoring corridors drove freight volumes up about 7% YoY in 2024, accelerating lane growth while Mullen’s presence remains nascent with limited cross‑border density. Cross‑border complexity and multi‑partner orchestration raise risk and add cost, pushing up dwell and compliance spend. The prize is large if density and strategic partners click; start with pilot anchor programs before scaling assets.
Mullen’s Question Marks: US expansion, EV fleets, control‑tower products, and cross‑border cold‑chain are high growth but low share; 2024 U.S. GDP ~USD 28.6T, Mullen revenue CAD 1.47B (2024). Invest selectively where dense lanes, incentives, anchor contracts and depot charging de‑risk scale; pilot before asset‑heavy rollout.
| Metric | Value |
|---|---|
| US GDP 2024 | USD 28.6T |
| Mullen revenue 2024 | CAD 1.47B |
| Cold‑chain market 2023 | USD 260B, 7.5% CAGR |
| Nearshoring freight 2024 | +7% YoY |


