
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
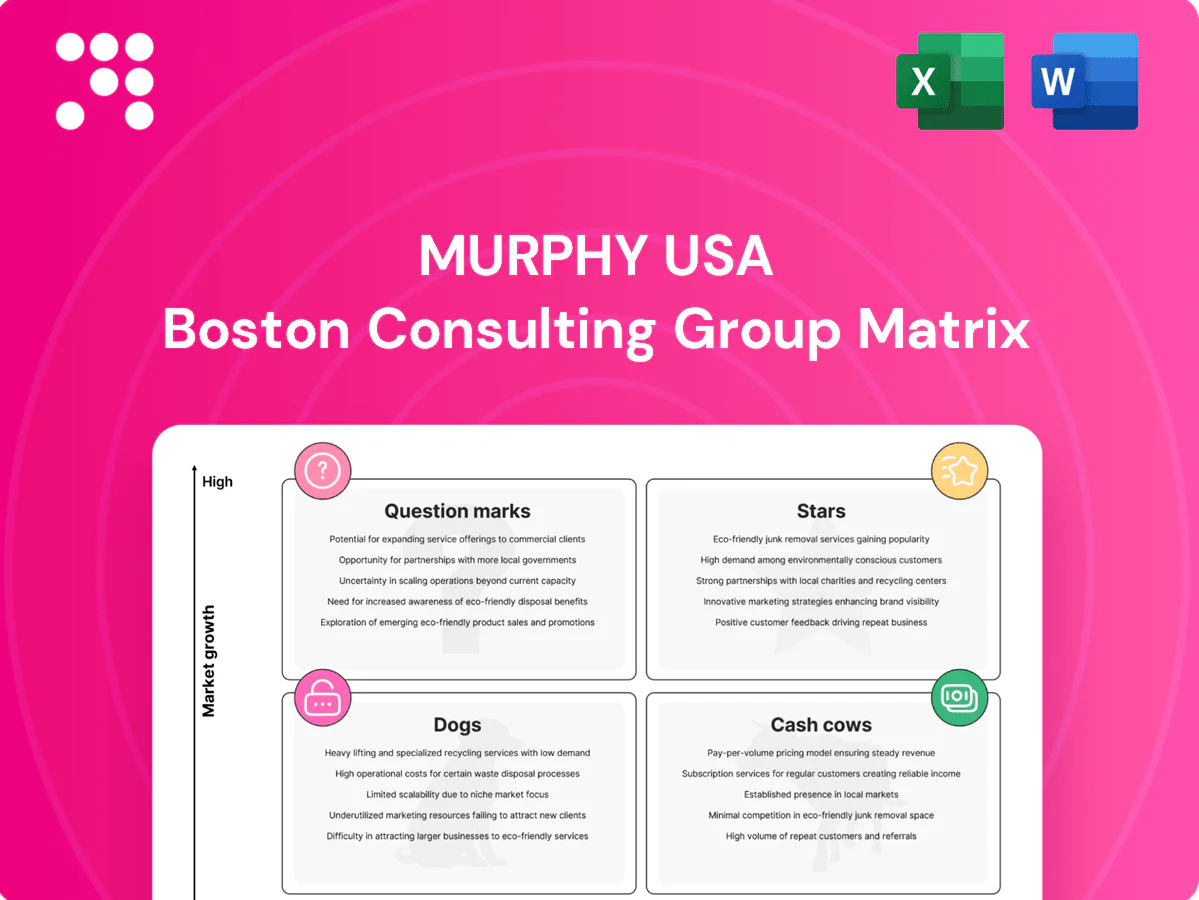
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Want a crisp read on Murphy USA’s product lineup and where each fuel and retail offering lands—Stars, Cash Cows, Dogs, or Question Marks? This snapshot hints at the moves they should make; the full BCG Matrix gives you quadrant-by-quadrant placement, data-driven recommendations, and a ready-to-use Word report plus an Excel summary. Skip the guesswork and buy the full version to get strategic clarity and an execution-ready roadmap. Purchase now for instant access and practical next steps.
Murphy USA’s core forecourt model, with about 1,500 Walmart-adjacent fuel sites, drives very high gallon volumes by capturing strong grocery and value-seeking traffic. Scale and a persistent low-price perception have sustained retail share in a price-sensitive market. Keep promotions razor-sharp and operational uptime near 100% to protect throughput. If this momentum persists as the market matures, the business cleanly graduates into Cash Cow territory.
Price leadership is Murphy USA's calling card and a durable moat in inflation-aware times, driving frequent trips and habit formation.
It blunts competitors' promos but depends on disciplined sourcing and razor-thin operational waste across roughly 1,500 sites (2024).
Continued investment in data-driven pricing and demand-shaping analytics is essential to sustain star-market growth.
Murphy Express stand-alone growth nodes extend reach beyond Walmart lots into fast-growing corridors, capturing incremental market share and foot traffic. Where the format fits demographic and traffic profiles, volumes and in-store attachment run well above company averages. Execution requires disciplined capital allocation, rigorous site selection and tight build-cost control. When done right, these nodes scale into high-return growth posters that feed future cash generation.
Discounts, app rewards and targeted offers keep price-sensitive drivers loyal, lifting visit frequency and shifting basket mix toward higher-margin convenience items during quick in-and-outs; Murphy USA leverages these levers to protect share as retail fuel demand grows in 2024. The customer-data flywheel improves promo ROI over time, enabling more efficient acquisition and retention. Scale personalized offers to defend share while the market expands.
Sunbelt population gains and rising commuter miles (US VMT ~3.18 trillion in 2023, FHWA) favor Murphy USA’s convenience-fuel format, converting new rooftops into regular value-fuel customers; Murphy USA operates about 1,500 retail fuel sites in high-growth southern and Sunbelt corridors (2024 company data). Site density boosts brand recognition and lowers marketing cost per site, supporting a focused roll-out where competitors remain fragmented and growth curves steep.
Murphy USA’s ~1,500 Walmart‑adjacent fuel sites (2024) drive high volumes via price leadership and habitual trips, sealing retail share in price‑sensitive corridors. Targeted discounts, app rewards and a data flywheel lift visit frequency and basket mix, turning Stars into future Cash Cows if execution and disciplined sourcing persist. Sunbelt population and rising VMT underpin continued unit-level growth.
| Metric | Value | Source |
|---|---|---|
| Sites | ~1,500 | Company 2024 |
| US VMT | ~3.18T | FHWA 2023 |
| Population trend | Sunbelt gains | US Census 2023/24 |
 Detailed Word Document
BCG analysis of Murphy USA’s portfolio: identifies Stars, Cash Cows, Question Marks, Dogs with strategic invest/hold/divest guidance.

 Customizable Excel Spreadsheet
One-page Murphy USA BCG Matrix highlighting cash cows and stars to cut confusion and prioritize investment.
Mature Walmart-adjacent forecourts, roughly 1,500 sites in 2024, deliver steady, predictable fuel and convenience margins from established traffic patterns. Growth upside is limited but volumes are sticky, with weekday/weekend throughput consistent across markets. Low promotional spend preserves gross margins and operating leverage. Focus on asset upkeep, labor optimization, and throughput management to sustain cash generation.
Core c-store staples — beverages, snacks, tobacco — create fast, repeatable convenience baskets that drive dependable cash flow at Murphy USA, with roughly 1,400 retail sites in 2024 concentrating on high-frequency purchases. Assortment discipline and vendor programs protect in-store margins, while limited category complexity keeps shrink and waste low. These steady dollars fund new growth bets without rocking the boat.
Lottery, ATM, and service add-ons are low-lift, steady-fee cash cows that pad Murphy USA profitability with minimal inventory risk and capital expenditure.
They capture fuel traffic, deliver high-margin per-transaction revenue, and are simple to operate and maintain.
Focus on preserving placements and renegotiating merchant and lottery terms to incrementally boost yield.
Scale buying and tight logistics turn pennies per gallon into real money; in stable demand lanes execution beats heroics and incremental margin gains are durable. Systems are in place and improvements come from tweaks to routing, rack strategy and supplier mix. Murphy USA’s scale—about 1,500 retail fuel sites as of 2024—magnifies those penny gains.
≈1,500 established Murphy Express locations in mature trade areas cooled to low-single-digit traffic growth in 2024 but continue to print steady cash as customer fueling and in-store habits stick. Marketing needs are light since local customers already know the drill; operational focus is uptime, cleanliness, and speed to preserve margins. Bank excess cash and redeploy into higher-growth DMAs with stronger unit economics.
Mature Walmart-adjacent forecourts (~1,500 sites in 2024) and ~1,400 core c-store locations generate steady, low-volatility cash flow with low promotional spend and low-single-digit traffic growth in 2024; focus remains on uptime, throughput and vendor terms to squeeze incremental margin.
| Metric | 2024 |
|---|---|
| Fuel sites | ≈1,500 |
| Retail c-stores | ≈1,400 |
| Traffic growth | Low-single-digit |
The file you're previewing is the exact Murphy USA BCG Matrix report you'll get after purchase. No watermarks, no placeholders—just the finished, professionally formatted analysis. It’s ready to edit, print, or present to your team. Buy once and download instantly; what you see is what you’ll use.
Underperforming low-density rural Murphy USA sites see limited commuter flow and often too many pumps for local demand, so cash trickles in while capex remains tied up in station equipment and canopy upkeep. Turnarounds are expensive and slow, with ROI horizons stretching multiple years and often missing corporate hurdle rates. Prune or repurpose sites when projected cash-on-cash returns and payback periods fail to meet 2024 portfolio thresholds.
Legacy kiosk formats with constrained retail mix at Murphy USA—approximately 1,500 sites—limit average basket growth and crush add-on sales; industry comparisons show fueling-only footprints typically generate materially lower per-site nonfuel revenue than full c-stores. Operating cost savings from tiny footprints do not shrink enough to justify the margin loss. Competitors with fuller stores poach impulse buys; sunset or convert selectively.
Premium SKUs in price-sensitive micro-markets underperform: EIA reports premium grades at about 6% of U.S. gasoline volumes in 2023–24, causing slow high-octane turns and inventory carrying costs that erode margins. Murphy USA’s value-oriented customer mix and throughput favor regular grades, so forecourt space is better used elsewhere. Reduce premium nozzles or exit sites where demand is chronically thin.
Overlapped sites cannibalizing each other: Too-close Murphy USA locations split volumes instead of growing the pie, eroding margins as same customers shift between nearby stores; in 2024 Murphy USA operated about 1,500 retail fuel sites, where dense clustering can cut per-site throughput materially. Labor and maintenance costs effectively double for the same revenue pool, so network density should help, not hurt, and targeted consolidation can restore unit economics.
Niche in-store Dogs—low-velocity SKUs at Murphy USA (approx 1,470 sites in 2024)—tie up shelf space, complicate restock rhythms and labor; spoilage/obsolescence (retail shrink ~1.4% in 2024) erodes margins and fails to drive trip frequency or basket build, so pruning tail SKUs while retaining top sellers improves turns and ROC.
Underperforming rural Murphy USA Dogs (~1,500 sites in 2024) show low throughput, long ROI horizons and excess capex tied in pumps/canopies, suggesting prune or convert. Premium fuel ~6% of volumes (2023–24), slow turns; cut premium nozzles where demand is thin. Retail shrink ~1.4% (2024); trim low-velocity SKUs and consolidate overlapping sites to restore unit economics.
| Metric | 2024 | Action |
|---|---|---|
| Sites | ~1,500 | Prune/convert |
| Premium share | ~6% | Reduce |
| Shrink | ~1.4% | Cut tails |
EV charging pilots sit in a high-growth category—US public chargers surpassed 150,000 outlets in 2024 and NEVI/IRA funding (about 5 billion federal NEVI plus IRA incentives) lowers network cost—but Murphy’s share and utilization remain nascent. Capital expenditure per fast charger can be $100k–500k, incentives help, and customer charging behavior is still forming. If economics and dwell-time retail lift margins, chargers could anchor future traffic. Test, learn, and scale only at sites where dwell-time retail can cover incremental rent.
Enhanced F&B (hot/iced coffee, grab-and-go, light foodservice) is a Question Mark for Murphy USA: with ~1,600 sites and a small current share in fresh offerings, upside exists if baskets rise — NACS 2023 found fresh food can lift basket size 10–20%. Execution risk is non-trivial: freshness, labor and waste hit margins. If average ticket increases as pilots show, margins can reshape; pilot tightly before wide rollout.
Growing interest in E15 and biodiesel blends is emerging in pockets with regulatory tailwinds and localized demand; Murphy USA operates approximately 1,500 retail fuel locations (Murphy USA, 2024), yet current alternative-fuel share remains modest and infrastructure uneven. Margin per gallon can improve if adoption sticks, so invest selectively where fleet contracts and regional patterns justify station upgrades and storage additions.
Data exists across Murphy USA’s ≈1,500 sites and digital touchpoints, but one-to-one activation remains in the early innings; McKinsey 2024 estimates personalization can boost purchase frequency and basket size 5–15% when executed well. Expect front-loaded tech and analytics spend (retailers average ~4–5% of revenue on digital transformation in 2024) with ROI trailing; adopt build, measure, kill fast to avoid discount burn.
New-market Murphy Express infill in unfamiliar metros brings clear ramp risk: traffic models show attractive unit economics but brand awareness starts low, so initial volumes may lag; Murphy USA operates roughly 1,600 sites nationwide (2024), and if pilot volumes hit plan these infill sites can graduate to Stars quickly.
Question Marks (EV charging, F&B, alt fuels, personalization) show high upside but nascent returns: US public chargers >150,000 (2024) and NEVI/IRA ≈$5B lower build cost, Murphy’s ~1,600 sites (2024) need selective pilots; fresh food can lift baskets 10–20% (NACS 2023); personalization may boost spend 5–15% (McKinsey 2024).
| Initiative | 2024 status | Key metric | Next step |
|---|---|---|---|
| EV charging | Pilot | 150k chargers; $100k–500k/charger | Site-level ROI |
| F&B | Limited fresh | +10–20% basket | Tight pilots |
| Alt fuels | Selective | ~1,600 sites | Fleet targets |
| Personalization | Early | +5–15% lift | Fast A/B |


