
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
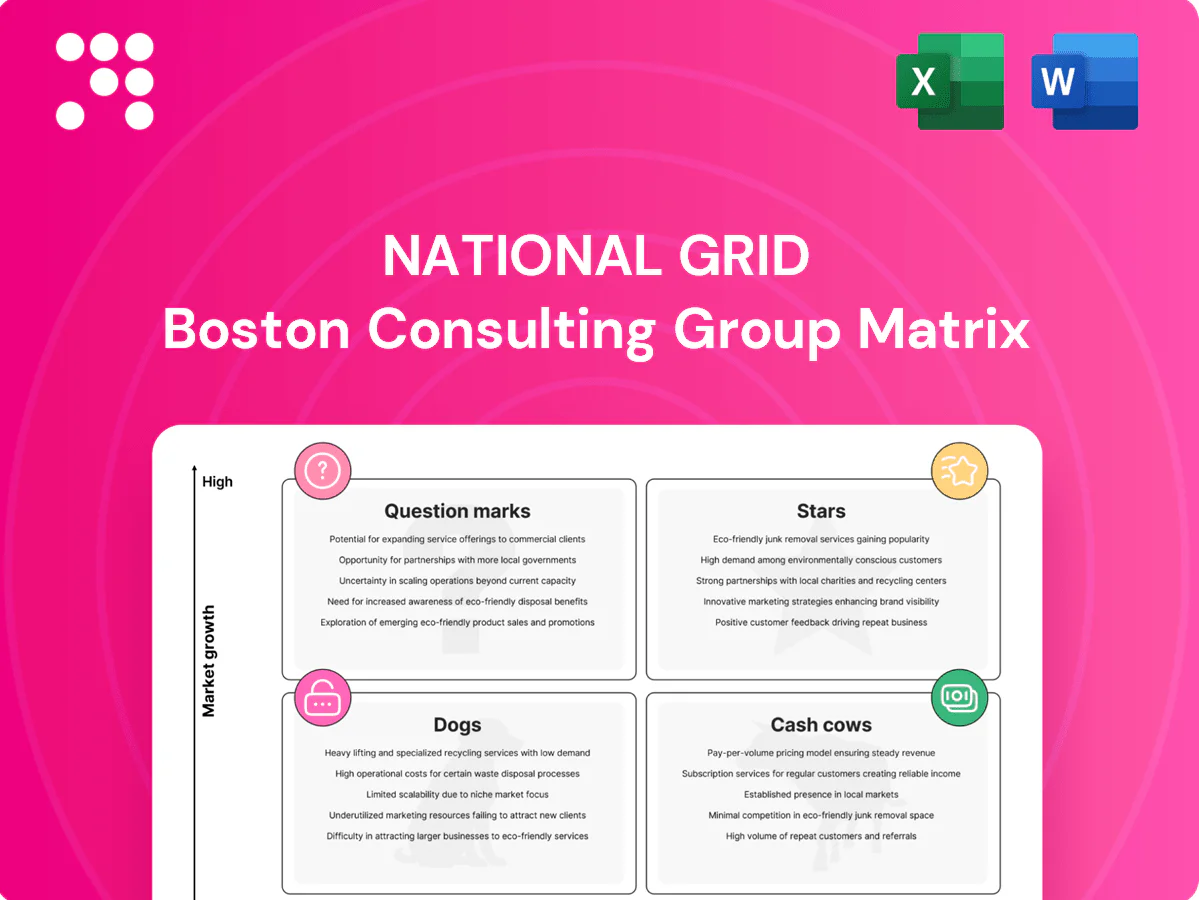
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
National Grid’s BCG Matrix snapshot highlights which business lines are powering growth, which steady assets fund the future, and where attention or divestment is overdue — a crisp view of winners, laggards, and risky bets. This preview teases quadrant placements and high-level signals; buy the full BCG Matrix for precise product-level positioning, data-driven recommendations, and an actionable playbook. Get both a polished Word report and an Excel summary to present, model, and decide with confidence. Purchase now and stop guessing—start acting.
National Grid is the go-to for tying massive offshore wind into the UK system as the sector targets 50 GW by 2030, with about 14.6 GW operational at end-2023; demand keeps surging. They sit at the center of virtually every major project, with connection queues far outstripping current capacity. Growth is hot and share is dominant; sustaining ~£6–7bn regulated capex run-rate in 2024 will let hookups mature into a thick-margin engine.
Electrification is lifting load growth across MA, NY and RI as EV registrations rose ~45% YoY through 2024 and heat pump installations accelerated, while data center demand in NY expanded double digits. National Grid already owns the wires, permits and ~8 million U.S. customer relationships, positioning it as a market leader. Heavy investment — >$10 billion planned through 2026 in the region — converts scale into durable advantage.
Cross-border interconnectors such as NSL (1.4 GW), IFA2 (1 GW) and the soon-to-complete Viking Link (1.4 GW) are strategic, scarce assets that capture price spreads and system-balancing value. Their placement at the intersection of arbitrage and grid stability gives them outsized revenue potential. Europe’s push for supply resilience bodes well for further utilization. National Grid’s high share in this niche drives significant strategic value.
Advanced control rooms, real-time visibility and DER orchestration form the spine of the future grid; National Grid is deploying these capabilities at scale on both sides of the Atlantic. They serve roughly 20 million customers and are integrating ADMS/VPP tools to manage rapidly rising distributed renewables. As renewables climb, modernization is mandatory and the market is fast-growing, where National Grid is a clear leader.
Developers need timely interconnections and National Grid controls that choke point, making queue reform, faster studies and smarter planning critical; the US interconnection backlog exceeded 1,100 GW in 2024 (DOE/SEIA), underscoring the scale challenge. It’s a scale game where incumbency wins—high growth, high relevance, National Grid is in the driver’s seat.
National Grid is a Star: 14.6 GW offshore (end‑2023), 50 GW UK target by 2030, and £6–7bn regulated capex run‑rate in 2024 fueling growth. US EV registrations +45% YoY through 2024 and >$10bn planned 2024–26 bolster demand; US interconnection queue >1,100 GW (2024).
| Metric | 2024/2023 |
|---|---|
| Offshore | 14.6 GW (end‑2023) |
| Capex | £6–7bn (2024) |
| US queue | >1,100 GW (2024) |
 Detailed Word Document
In-depth BCG Matrix review of National Grid’s units, showing Stars, Cash Cows, Question Marks, Dogs with investment, hold, divest guidance.

 Customizable Excel Spreadsheet
One-page BCG matrix placing each National Grid unit in a quadrant, printable and C-level ready to ease portfolio decisions
UK HV transmission RAB for England & Wales is a mature, entrenched asset class — RAB exceeds £15bn as reported in 2024 — delivering stable, low-volatility cashflows and high market share by design. Opex and capex are predictable under RIIO controls with efficiency incentives, supporting ~regulated returns that reliably fund dividends and investment. This cash engine underwrites National Grid’s new-growth bets.
GB gas transmission backbone is large, regulated and essential under RIIO-2, handling the bulk of GB pipeline flows with UK gas demand around 74 billion cubic metres in 2024; utilization remains solid and pricing is formula-driven by Ofgem mechanisms. It delivers low growth but high share and dependable cash, supporting stable returns and strong cash generation. Strategy: milk it, maintain it, don’t overspend.
In the Northeast, National Grids US gas distribution is a mature, sticky cash cow with long asset lives (distribution mains often 50+ years) and replacement cycles that smooth capex. Stable volumes and regulated allowed ROEs in the mid-to-high single digits (around 8–10%) underpin predictable returns. Not high growth, but reliable cash generation supporting dividends and reinvestment; keep operations efficient and forecastable.
US electric distribution core sits in Cash Cows: outside storm and electrification hotspots the delivery business is steady-state with territory control and regulatory rate recovery anchoring cash flow; low organic demand growth but predictable returns if O&M and capital are tightly managed.
Grain LNG long-term regas capacity underpins stable, contract-backed cash flows for National Grid, with long-term contracts smoothing revenue volatility.
As regulated infrastructure with high barriers to entry and limited direct competition, Grain exhibits classic cash cow characteristics: modest growth but resilient utilization through market cycles.
Steady throughput and predictable tariff frameworks support strong free cash generation and margin stability within the BCG Matrix cash cow quadrant.
UK HV transmission RAB >£15bn (2024) yields stable, low-volatility cashflows; GB gas transmission handles ~74 bcm (2024) with formulaic tariffs; US gas distribution delivers regulated ROEs ~8–10% and long asset lives; Grain LNG provides contract-backed regas revenues—low growth, high cash generation funding new investments.
| Asset | 2024 metric | Role |
|---|---|---|
| UK HV transmission | RAB >£15bn | Core cash generator |
| GB gas transmission | Demand ~74 bcm | Stable regulated cash |
| US gas distribution | Allowed ROE ~8–10% | Predictable returns |
| Grain LNG | Long-term contracts | Contracted cashflows |
The file you're previewing is the exact National Grid BCG Matrix report you'll receive after purchase—no watermarks, no placeholders. It's a fully formatted, analysis-ready document crafted for strategic clarity and quick decision-making. Once purchased, the identical file is yours to download, edit, print, or present to stakeholders. Simple: what you see is what you get, ready for immediate use.
Leak‑prone legacy gas mains are capital sinks—consuming over £1bn of annual capex in 2024 while generating no growth and attracting heightened Ofgem scrutiny; you spend to stand still. Necessary for safety and network integrity, they are value‑dilutive rather than accretive. Prioritize footprint minimization and accelerate targeted retire/replace programs to cut operating risk and free capital for growth areas.
Paper-heavy customer ops cost ~£1.50–2.00 per mailed bill versus ~£0.10 for e-billing and push call-center unit costs of ~£4–6 per contact, dragging margins by roughly 1–2 percentage points while delivering poor CX; with no addressable market share to capture in this segment, scale benefits are limited. Digitize or sunset.
Dogs:
Scattered legacy sites and depots in National Grid's non-core property portfolio remain maintenance drains and operational risk as of 2024, with no clear growth pathway or strategic differentiation; capital allocation is better directed to regulated network investment and decarbonisation projects. Prune and recycle proceeds to reduce opex and fund higher-return core assets.
Minor legacy telecom and dark-fiber leases at National Grid are low-share, low-growth Dogs—contributing under 1% of group revenue and under 2% of operating profit in 2024, while market demand for core grid digitization outpaces these odds-and-ends.
Administrative burden and maintenance capex routinely exceed net returns, creating distraction without strategic upside; recommended action is divestiture or folding viable assets into core fiber/telecom platforms to extract value.
Dogs are low‑share, low‑growth liabilities: under 1% of group revenue and under 2% of operating profit in 2024, tying up maintenance capex and O&M with no growth pathway. Legacy metering, small telecom leases and scattered depots drain cash and management focus; decommission, divest or integrate into core platforms to free ~£1bn+ capex for regulated decarbonisation.
| Metric | 2024 | Action |
|---|---|---|
| Revenue share | <1% | Divest/prune |
| Op profit | <2% | Integrate/sell |
| Capex drag | £1bn+ (legacy mains) | Retire/replace |
Hydrogen blending pilots remain Question Marks for National Grid: policy tailwinds in 2024 support trials across the UK and Europe, but the commercial model is not yet locked.
Technical studies allow blends up to 20% by volume for many appliances, so scale success could give gas networks a second life.
If pilots fail to prove economics, investments risk becoming sunk costs, so decide quickly where to double down and where to bow out.
Load growth from EVs is accelerating — global EV sales reached roughly 14 million in 2024 (BNEF) and US NEVI directs 5 billion USD for charging; utility roles vary by jurisdiction. If National Grid owns make-ready and grid upgrades it can capture installation, operations and customer value and expand addressable market. Market share is still being defined; push where regulators reward speed with cost recovery and incentives.
Batteries unlock network flexibility but face merchant risk as rules and revenue stacks evolve rapidly; UK grid battery capacity reached about 3 GW in 2024. National Grid can win with co‑location and system know‑how, leveraging site control to reduce dispatch risk. Today these ventures consume cash; tomorrow they could anchor balancing revenues. Place targeted bets, not blanket ones.
Heat pump and demand response sit as Question Marks for National Grid: electrification is sprinting—UK heat pump installs rose ~40% in 2024 to ~140,000 units—yet utility monetization remains patchy. Owning orchestration of distributed heat and DR could convert peak shaving into revenue streams via capacity markets and V2G-style tariffs. Market share is early and fragmented; test, learn, and scale where tariffs and capacity payments align.
Operational data can be monetized into products—planning, forecasting and interconnection insights—offering high-growth upside but currently low share for National Grid; competitive tech firms are accelerating in utilities analytics, with the utility analytics market estimated to begin 2024 at a meaningful growth trajectory (CAGR ~16% 2024–2030), so invest selectively with clear use cases and partners.
Question Marks: hydrogen blending pilots gain 2024 policy support but commercial case unclear; technical feasibility ~20% blend. EV load and NEVI (US $5bn) open network services as global EV sales ~14m (2024). Batteries (~3 GW UK 2024) and heat pumps (+40% to ~140k UK 2024) need targeted pilots where tariffs enable returns.
| Segment | 2024 metric | Implication |
|---|---|---|
| Hydrogen | up to 20% blend | pilot risk |
| EVs | 14m sales; $5bn NEVI | grid opportunity |
| Batteries | ~3 GW UK | flex value |
| Heat pumps | ~140k (+40%) | monetize DR |


