
Digital download
Access the files immediately after checkout.
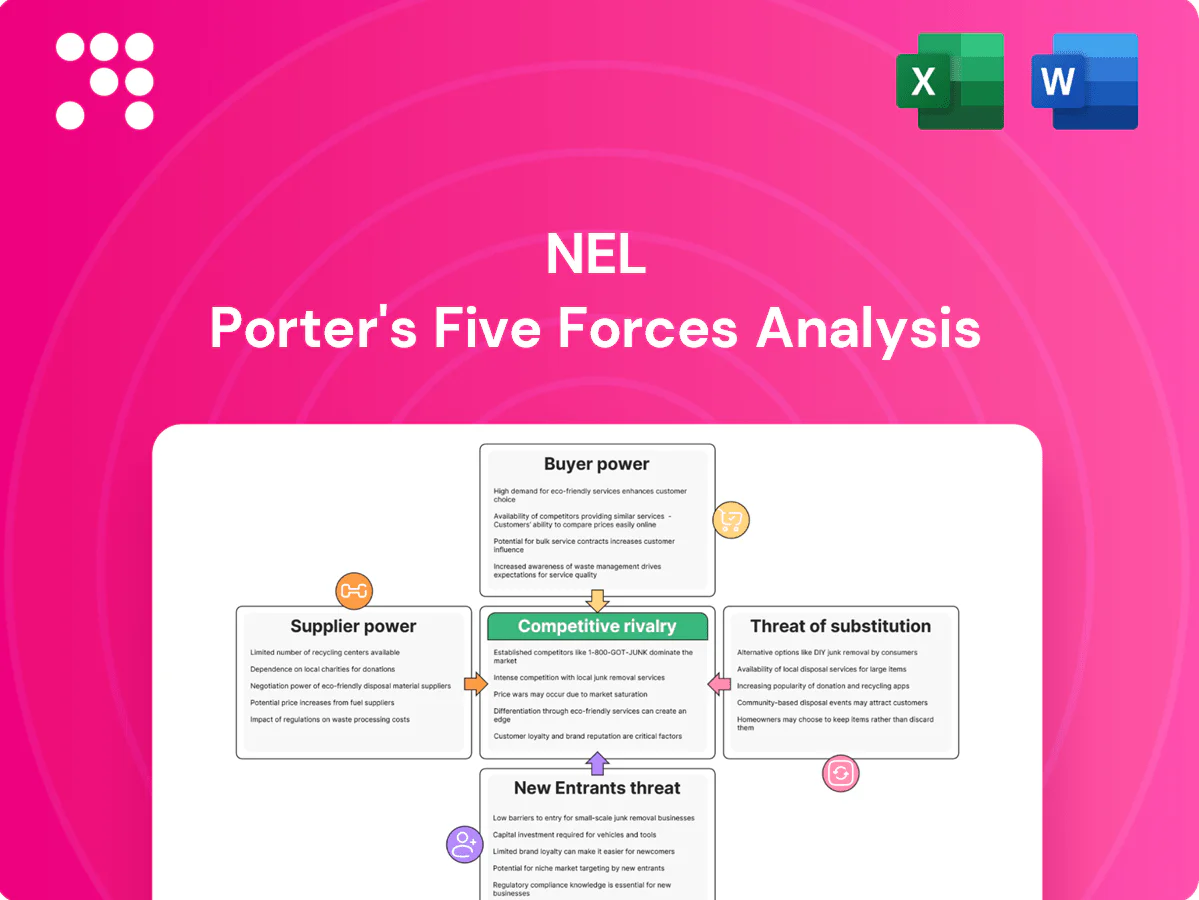
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
NEL’s Porter's Five Forces snapshot highlights supplier leverage, buyer sensitivity, rivalry intensity and substitute threats shaping margins and growth. We assess barriers to entry, technology risks and partner dependency. This brief snapshot only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore NEL’s competitive dynamics, market pressures, and strategic advantages in detail.
PEM stacks rely on scarce iridium and platinum, with South Africa supplying roughly 75–80% of global PGM mine output in 2024, concentrating supplier power. Price spikes and allocation risks can squeeze margins and delay deliveries; Nel reduces exposure via thrifting, recycling and dual-sourcing, though supplier leverage remains high. Long-term offtakes and hedging have partially stabilized input costs in 2024.
High-performance membranes and coated stack components are concentrated among a few suppliers (eg Gore, 3M), creating supplier power; qualification and system integration often require 12–24 months, raising switching costs and CAPEX. Suppliers have exerted leverage via price increases and 6–12 month lead times during 2021–24 supply strains. Vertical integration or co-development agreements materially reduce this exposure.
Rectifiers, inverters and high-pressure compressors are specialized, capital-intensive items with global power electronics market ≈ $40 billion in 2024 and compressor lead times often 12–24 months; limited qualified suppliers can push prices and delivery schedules. Standardization and design-for-supply expand vendor options and reduce unit cost. Strategic inventory buffers and multi-sourcing smooth project execution and cut schedule risk.
Renewable electricity availability is a de facto supplier power for Nel: project viability and LCOH depend on cheap green power, so curtailment or constrained renewables raise LCOH and can defer orders. Developers and utilities therefore indirectly shape Nel’s demand and timing; IEA 2024 noted renewables accounted for roughly 90% of net power capacity additions, concentrating influence. Structuring EPC and power agreements with customers can align incentives and de-risk timing.
Experienced hydrogen engineers, installers and EPCs remain scarce, and 2024 saw over 200 GW of announced electrolyzer projects that intensify demand; labor bottlenecks give service partners leverage on pricing and schedules. Nel can reduce dependency by building internal capabilities and preferred EPC networks, while training programs and standardized modules cut on-site complexity and cycle time.
Nel faces high supplier power: PEM catalysts are PGM‑dependent with South Africa ~75–80% of PGM mine output in 2024, creating price/allocation risk. Key membranes/coatings (eg Gore, 3M) and power electronics (~$40B market in 2024) have long qualification and 12–24 month lead times. Renewables drove ~90% of net power additions in 2024, making developers/utilities de facto suppliers. Nel mitigates via thrifting, recycling, dual‑sourcing and long‑term offtakes.
| Supplier type | 2024 metric | Impact | Mitigation |
|---|---|---|---|
| PGMs | SA ~75–80% output | Price/allocation risk | Thrifting,recycle,offtakes |
| Membranes | Few vendors | High switching cost | Co‑dev/vertical integration |
| Power eqpt | $40B market | 12–24m lead times | Standardization, multi‑sourcing |
| Labor/Power | ~200GW announced electrolyzers | Schedule bottlenecks; renewables influence | Preferred EPCs, PPA/EPC contracts |
 Detailed Word Document
Uncovers key competitive drivers, supplier and buyer power, entry barriers, substitutes, and rivalry shaping NEL’s market position—identifies disruptive threats, pricing levers, and strategic defenses; fully editable for investor decks, business plans, or academic use.

 Customizable Excel Spreadsheet
Compact one-sheet NEL Porter's Five Forces analysis that pinpoints competitive pressures, supplier/buyer leverage and regulatory risks—ready to paste into decks, update instantly with new hydrogen-market data, and clarify strategic priorities for faster decision-making.
Refiners, ammonia producers and industrial gas firms place large, infrequent orders that concentrate buying power, enabling aggressive price negotiation and strict performance guarantees.
Selection hinges on bankability and total cost of ownership—customers favor suppliers with proven uptime, financing track records and low lifecycle costs.
Long-term framework agreements are used to lock in volumes and share while preserving reasonable margins for suppliers.
Many projects rely on grants and auctions that emphasize lowest cost, and public procurement represents about 14% of EU GDP (Eurostat), amplifying buyer leverage across vendors. Transparent bidding forces Nel to balance win rates with margin discipline in competitive tenders. Strict compliance and local-content rules—increasingly used in 2024 subsidy frameworks—can be differentiators beyond price.
By 2024 buyers demand precise footprints, duty cycles and seamless renewable integration, forcing NEL to offer tailored electrolyzer configurations. Customization raises switching costs and lock-in but risks scope creep and margin erosion. Clear modular product lines mitigate bespoke risk while meeting performance targets. Service-level agreements monetize reliability through uptime guarantees and tiered maintenance fees.
Hydrogen projects face long development and financing timelines, often 3–7 years, lengthening sales cycles. Buyers demand milestone-linked payments and penalties that pressure cash flow and working capital. Strong references and warranties are key negotiation chips, while Nel’s standardized electrolyser platforms reduce diligence time and conversion risk.
Buyers (refiners, ammonia, industrial gas) concentrate volume, push price/penalties and favor bankable suppliers with low TCO; public procurement (~14% of EU GDP in 2024, Eurostat) amplifies price pressure. Long sales cycles (3–7 yrs) and milestone payments strain Nel’s cash flow; standardised electrolyzers, >95% uptime KPIs and 5–15% bundle discounts with 3–7% premiums for guaranteed output shape negotiations.
| Metric | Value |
|---|---|
| EU public procurement | ~14% GDP (2024) |
| Sales cycle | 3–7 yrs |
| Uptime KPI | >95% |
| Bundle discounts | 5–15% |
| Premiums for guarantees | 3–7% |
This preview shows the exact NEL Porter's Five Forces analysis you'll receive immediately after purchase—no placeholders or samples. The file is fully formatted and contains complete assessments of competitive rivalry, supplier and buyer power, threat of new entrants, and substitute products, ready for download. Purchase grants instant access to this identical, professionally written document for immediate use.
Global electrolyzer competitors—Cummins, Siemens Energy, ITM Power, Plug Power, Thyssenkrupp Nucera and numerous Chinese vendors—compete mainly on cost per kW, stack efficiency and delivery reliability; global shipments reached about 1.5 GW in 2024, intensifying price pressure as new capacity comes online. Capacity expansions and aggressive pricing compress margins, making bankability, long-term service contracts and project-level warranties key differentiation points.
Each pathway trades cost, dynamics and efficiency: 2024 CAPEX ranges roughly alkaline 250–450 USD/kW, PEM 400–800 USD/kW, while SOEC remains higher but can reach electrical+heat efficiencies >80–90% (LHV) when integrated with high‑grade heat. PEM offers sub‑second dynamic response vs alkaline minutes, so cross‑technology competition pushes project bids by application and duty cycle. Nel must align platform choice to specific use‑cases to win contracts.
Gigafactory-scale output drives costs down the learning curve: industry learning rates for electrolysers are estimated around 18–20% per cumulative capacity doubling, materially reducing unit costs; players with automation and high yields can undercut rivals. Yield, stack life and throughput decide tenders, and continuous improvement plus supplier co-location create durable edge.
Aftermarket networks and spare-parts availability directly shape lifetime economics; leading service providers in 2024 commonly promise 98–99% uptime and bundled spare coverage that materially reduces total cost of ownership. Competitors now offer performance guarantees, remote monitoring and predictive maintenance, with downtime penalties often structured as 1–3% of contract value, raising pressure on reliability. Data-driven maintenance creates customer stickiness through fleet-level insights and service renewals.
Geopolitics and localization fragment markets as 2024 saw the US and EU tighten local-content and procurement rules for clean energy, favoring regional incumbents with domestic manufacturing. Nel faces intensified localized rivalry and must adapt its manufacturing and service footprint to retain contracts. Partnerships, licensing and local JV models are pivotal to accelerate market entry and meet procurement clauses.
Intense price and capacity competition: 1.5 GW global electrolyzer shipments in 2024 compressed margins and prioritized bankability, service contracts and warranties. Technology split drives bids—alkaline CAPEX ~250–450 USD/kW, PEM 400–800 USD/kW; SOEC higher but >80% LHV possible with heat integration. Localization and uptime guarantees (98–99%) are decisive for tenders.
| Metric | 2024 | Implication |
|---|---|---|
| Shipments | 1.5 GW | Price pressure |
| Alkaline CAPEX | 250–450 USD/kW | Lowest cost |
| PEM CAPEX | 400–800 USD/kW | Flexibility premium |
| Uptime guarantees | 98–99% | Contract win |
Heat pumps (COP 3–4) and BEVs (well-to-wheel ~70–80% round-trip) can bypass hydrogen in transport and heat, versus hydrogen paths at ~30–40% efficiency, cutting addressable electrolyzer demand notably in buildings and passenger transport. Nel must prioritize hard-to-electrify segments: shipping, aviation, heavy industry and chemicals.
Blue hydrogen (SMR/ATR with CCS) can undercut green in gas-rich regions at roughly 1–2 USD/kg delivered in 2024, but competitiveness hinges on CO2 storage access and policy credits (EU carbon price ~100 EUR/t in 2024). Regulators scrutinize methane leakage and require high capture rates (typically >90%) for low-carbon claims. Falling renewable and electrolyzer costs (green LCOH approaching 2–4 USD/kg) erode blue’s near-term edge.
Sustainable biofuels and biogas can decarbonize existing assets, but global biofuel supply covers only about 3–4% of transport energy (IEA 2023), so feedstock limits cap scale and leave gaps in mobility and heat sectors. Regional subsidy regimes (EU RED, US RFS) strongly sway uptake. Nel can target markets and applications where bio supply is constrained, offering hydrogen as a scalable complement.
Regions can import low-cost hydrogen carriers; global ammonia production was about 180 Mt in 2024 and ammonia contains 17.6% hydrogen by mass, so cheap imported ammonia/hydrogen can undercut local electrolysis if shipping and conversion losses are offset by price spreads. Port infrastructure, bunkering standards and hydrogen/ammonia cracking efficiency are pivotal to realized costs. Long-term PPAs and capacity payments can keep local electrolysis viable by securing revenue and financing.
Onsite fossil solutions coupled with purchased offsets remain a lower-capex, short-term substitute for electrification, letting companies defer plant upgrades; the voluntary carbon market was about $2.4 billion in 2023, underpinning this pathway.
Integrity concerns—numerous studies flag large portions of credits as low-quality—and tightening regulations (e.g., EU Green Deal/ETS reforms and rising corporate disclosure rules) are reducing this option's long-term appeal.
Heat pumps/BEVs (COP 3–4; BEV round-trip ~70–80%) displace hydrogen in buildings/passenger transport. Blue H2 ~1–2 USD/kg delivered in 2024; EU carbon ~100 EUR/t pressures low-carbon claims. Ammonia 180 Mt (2024), 17.6% H2 by mass enables imports; voluntary offsets market ~$2.4bn (2023) offer short-term fossil deferral.
| Substitute | Key stat | Impact on Nel |
|---|---|---|
| Heat/BEV | COP 3–4; 70–80% | Reduces electrolyzer demand |
| Blue H2 | 1–2 USD/kg (2024) | Price pressure |
| Ammonia | 180 Mt; 17.6% H2 | Import competition |
Building stack factories and test infrastructure requires heavy capex, often in the hundreds of millions (typical electrolysers factory projects in 2024 ranged roughly $100m–$500m), creating a high entry-ticket.
New entrants face steep learning curves and bankability hurdles—lenders in 2024 preferred proven suppliers with track records—so without references winning tenders is difficult.
Scale procurement advantages for incumbents further deter entry by compressing margins and raising required volumes to compete.
Coatings, membranes and stack designs at NEL are protected by extensive patents and specialized materials know-how, making replication difficult for new entrants. Process expertise in managing durability and degradation is highly specialized, so newcomers risk producing stacks with inferior lifetime performance. As a result, market entry typically requires partnerships, licensing or acquisition of IP to achieve competitive reliability.
Hydrogen equipment must meet stringent standards such as ISO 14687 and EN 17124 and secure permits, with certification processes commonly taking more than a year. Lengthy validation slows new entrants and raises development costs. Insurers and lenders increasingly weigh multi‑year safety track records before underwriting projects, tightening finance for unproven vendors. Established players gain advantage from validated designs and existing type approvals.
Securing iridium, specialized membranes and high‑pressure compressors at scale is difficult due to limited suppliers and concentrated capacity; incumbents often lock supply via long‑term contracts (typically 3–10 years), forcing newcomers to pay premium prices and accept extended lead times, frequently exceeding 12 months. Vertical integration by industry leaders further raises entry costs and technical barriers.
High capex ($100m–$500m typical electrolyser factory in 2024) and protected IP create steep entry costs; bankability and 3–5 reference projects are often required. Lenders/insurers favor proven suppliers, supply constraints (iridium, membranes) and >12‑month lead times raise costs. Incumbents use 3–10 year contracts, vertical integration and 99.99% SLA expectations to deter entrants.
| Metric | 2024 Value |
|---|---|
| Factory capex | $100m–$500m |
| Lead times | >12 months |
| Contract terms | 3–10 years |
| Reference projects | 3–5 |
| Build cost to scale | >$50m |


