
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Quick look: NFI Group’s BCG Matrix previews where buses and services sit—stars driving growth, cash cows funding the fleet, question marks that need betting, and dogs you might cut. Want the full picture with quadrant-level data, actionable moves, and clear ROI priorities? Purchase the complete BCG Matrix for a ready-to-use Word report plus an Excel summary so you can present, decide, and allocate capital with confidence.
New Flyer BEV buses hold a dominant North American heavy‑duty transit share, and the push to zero‑emission fleets—backed by the IIJA’s US$5 billion Low‑No grant program—keeps demand climbing. They lead procurement bids but scaling deliveries, depot charging and technician training continue to consume cash. Maintaining share relies on proven reliability and alignment with grant timing, maturing into steady cash generators. Invest to stay ahead on specs, secure grants and maximize uptime.
Alexander Dennis EV line, part of NFI since 2019, is a Star in the BCG matrix with a strong double-decker EV footprint as cities accelerate electrification; deployments and homologation remain capital intensive. Growth is hot in 2024, but supply‑chain and deployment capex weigh on margins—keeping the lead converts into durable cash as routes standardize. Strategy: push volume, deepen OEM/operator partnerships, and scale service readiness to lock in recurring revenue.
NFI Infrastructure Solutions rides the ZEB wave with turnkey charging and depot integration, where projects are complex, margins improve with scale and working capital becomes tied up. Nail execution and platform loyalty locks in repeat fleet contracts. Management highlighted 2024 ramp activity across North American transit agencies. Worth feeding now to cement long‑run advantage.
Integrated ZEB platform positioned as a Star in NFI Groups BCG matrix: selling vehicle, software and charging as a bundled solution wins large public procurements and was central to NFIs 2024 North American fleet orders and contracts.
Market growth in 2024 accelerated adoption but integration, performance guarantees and depot charging support require heavy aftersales and engineering resources to deliver end-to-end reliability.
Protecting share and driving standardization flips integration complexity into higher margins; continued investment in system reliability and warranty support preserves procurement leadership.
MCI electric coaches are a Stars as intercity and commuter electrification gains momentum in 2024, supported by pilot corridors and growing operator interest; MCI's long-standing brand strength aids early adoption. Early deployments demand engineering support and extensive customer hand‑holding, making near-term cash use tangible. Retain leadership as corridors electrify and operations scale to repeatable fleets; prioritize range, TCO, and service coverage to win volume.
Stars: NFI's New Flyer, Alexander Dennis EVs, Infrastructure Solutions and MCI coaches lead 2024 ZEB procurements as IIJA US$5 billion Low‑No grants drive demand; deployment and depot charging keep cash burn high. Scaling service, securing grants and standardizing specs convert growth into durable cash. Invest to lock procurement pipelines and uptime.
| Asset | 2024 signal | Capex/Impact |
|---|---|---|
| New Flyer BEV | Procurement leader | High depot capex |
| ADL EV | Double-decker demand | Engineering spend |
 Detailed Word Document
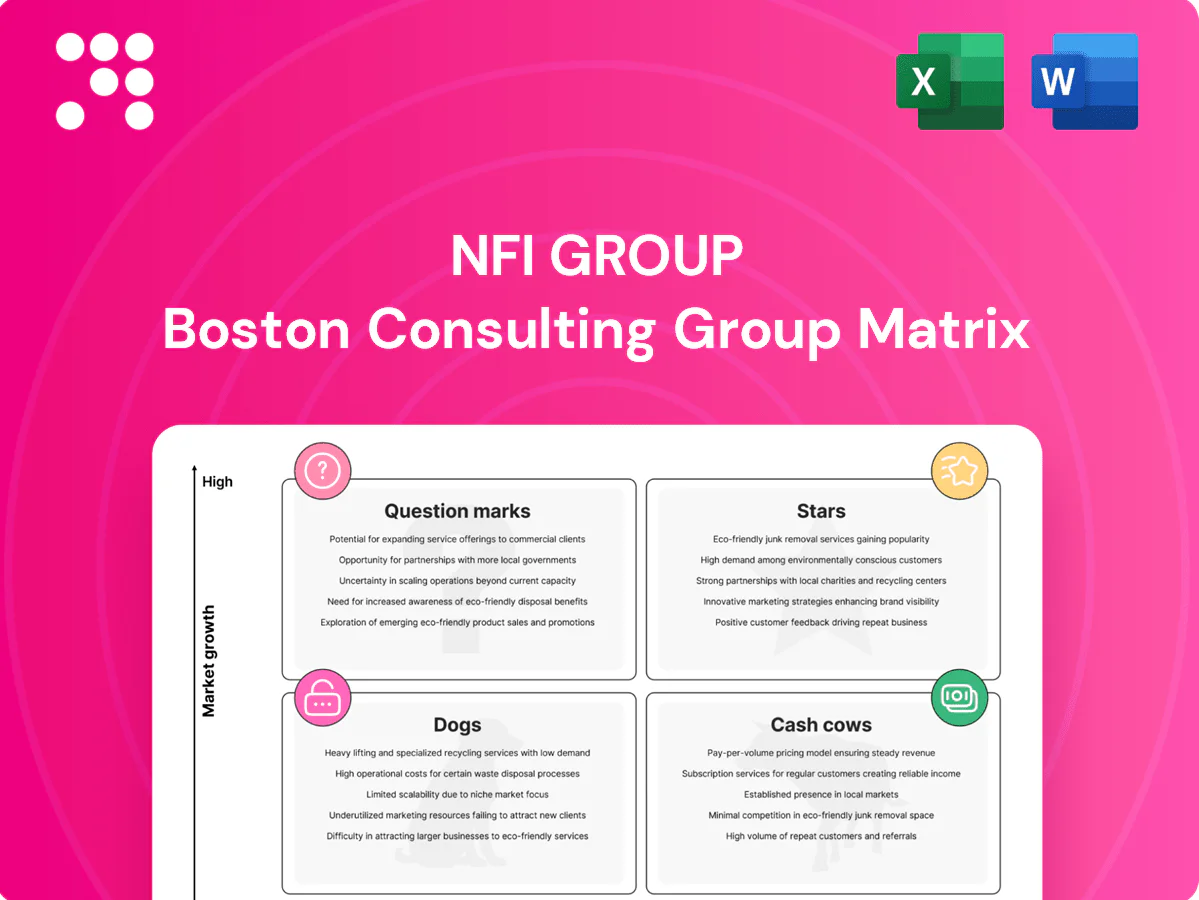
In-depth BCG Matrix of NFI Group showing Stars, Cash Cows, Question Marks and Dogs, with clear invest, hold or divest guidance.

 Customizable Excel Spreadsheet
One-page NFI Group BCG Matrix pinpoints underperformers and stars, easing strategy debates for execs.
Aftermarket parts and service is a classic cash cow for NFI Group, supported by a large installed fleet and steady orders that generate predictable margins and sticky customer relationships.
With low market growth but high share, aftermarket revenue funds R&D, covers fixed costs, and smooths production cycles while management focuses on optimizing inventory turns.
Expanding service bundles and preventive maintenance contracts increases lifetime value and cash generation from a stable, recurring revenue base.
MCI maintenance contracts provide steady, long‑term service revenue with low promotional spend, supporting margin stability in a mature coach market with consistently high renewal behavior. They deliver reliable cash flow that covers fixed costs and debt service, enabling reinvestment into parts and R&D. Maintain tight SLAs and prioritize upselling inspections and overhauls to boost lifetime value and reduce churn.
Alexander Dennis parts and support underpin recurring revenue within NFI Group, contributing to the company that reported CAD 6.7 billion in FY2024 revenue. Growth in AD24 aftermarket is modest but market share is strong, making it a dependable margin engine for NFI. Management should lean harder into e-parts, prebuilt kits and digital ordering to boost attach rates and lifecycle margins.
Legacy hybrid/diesel parts remain a cash cow for NFI: despite fleet electrification, the 2024 North American installed base of legacy buses exceeds 250,000 units, driving low growth but high utilization parts demand and steady margins with minimal marketing spend.
Refurbishment & overhauls are a Cash Cow for NFI Group: fleet life‑extension demand in mature markets is steady, capacity and skilled workforce are in place, and standardized overhaul packages speed throughput; 2024 refurbishment margins reported industry‑wide near 12% with cash conversion around 80–85%, underpinning strong free cash generation.
Aftermarket parts, MCI contracts, AD parts and refurbishments are NFI cash cows: high share, low growth, predictable margins that funded CAD 6.7bn FY2024 revenue. Legacy fleet >250,000 units (NA 2024) sustains parts demand; refurbishment margins ~12% and cash conversion 80–85% in 2024. Focus: improve availability, reman, digital ordering to lift attach rates.
| Segment | 2024 metric | Role |
|---|---|---|
| Aftermarket/AD | CAD 6.7bn revenue contribution (group) | Stable cash generator |
| Legacy parts | >250,000 NA installed base | Low growth, high utilisation |
| Refurbishment | ~12% margin; 80–85% cash conv. | Reliable free cash |
The file you're previewing is the exact NFI Group BCG Matrix you'll receive after purchase. No watermarks, no demo content—just the fully formatted, ready-to-use strategic matrix. It’s crafted by strategy pros for clarity and immediate implementation. Once bought, the full document is yours to download, edit, print or present without surprises. Simple, professional, and market-ready.
Procurement trends shifted decisively in 2024, with zero-emission buses capturing about 70% of new city bus orders, leaving diesel-only new builds in a low-growth, shrinking-share category that acts as a cash trap; slim margins and declining orders make large turnarounds hard to justify. Wind down diesel SKUs and redeploy 20–30% of production capacity toward zero-emission platforms and retrofit services.
Dogs: niche trolley platforms face a small, stagnant market with sporadic orders and limited pipeline in 2024. Engineering effort and customization drive unit costs above achievable margins, leaving projects at best break-even and tying up capital in low-turnover inventory. Given comparable opportunity cost versus core transit bus programs, consider exit or licensing partnerships to recoup R&D and free up manufacturing capacity.
Low-volume export models show fragmented specs, limited scale and thin margins, with market growth effectively flat and market share patchy across regions; resources get diluted across variants. Prune low-volume variants, consolidate platforms and redirect investment toward core regions where fleet orders and aftersales density maximize ROI.
NFI Group (TSX:NFI, NYSE:NFI) older hybrid generations are legacy tech with declining demand and rising support complexity; volumes fell into low-single-digit growth markets in 2024 as transit agencies shift to zero-emission buses (ZEB).
Market share is falling; aftermarket and service costs creep up, squeezing margins—plan to sunset these platforms gracefully and migrate customers to NFI ZEB offerings and retrofit programs in 2024.
Custom one-off coaches are a Dogs for NFI in 2024: they demand disproportionate engineering time, produce tiny volumes with little repeatability, and tie up skilled talent for limited commercial payoff.
2024: ZEBs ~70% of city bus orders; diesel-only and legacy hybrids in low-single-digit growth, tight margins and rising support costs. Trolley and custom one-off coaches are stagnant Dogs with sporadic orders and high engineering intensity. Recommend wind-down/licensing and redeploy 20–30% capacity toward ZEBs and retrofits to free capital.
| Segment | 2024 status | Action |
|---|---|---|
| Diesel | Low-growth; cash trap | Wind down; redeploy 20–30% |
| Trolley | Sporadic orders; high cost | Exit or license |
| One-off coaches | Tiny volumes | Discontinue/prune |
| Hybrids | Declining demand | Sunset; migrate to ZEB |
Fuel-cell electric buses sit in the Question Marks quadrant: growing interest and billions in public and private funding for zero-emission transit in 2024, but NFI’s commercial share in hydrogen buses remains nascent. The technology is capital‑hungry and hydrogen refueling infrastructure is sparse, raising up‑front costs and deployment risk. With material cost and range improvements, FCEBs could graduate to Stars; NFI must choose focused internal bets or partnerships to scale quickly.
Autonomous driver-assist sits as a Question Mark for NFI: safety pressure (WHO: ~1.3 million annual road deaths) and labor shortages push upside, yet market adoption remains early. Certification and liability barriers slow scale and raise unit cost. If NFI—North America’s largest bus manufacturer in 2024—locks a credible stack it could lead; pilot aggressively or pause to avoid drift.
Battery-as-a-Service offers a compelling TCO uplift and recurring revenue for NFI, especially as battery pack prices fell to about $120/kWh in 2024 (BNEF), but contracts are legally and operationally complex. It demands balance-sheet muscle and robust credit/risk models to underwrite multi-year leases. If executed well it can flip into a platform play aggregating charging, swaps and fleet data; test in select municipal and transit fleets before broad roll‑out.
Telematics and uptime analytics are a Question Mark for NFI Group: data services can lift margins and customer stickiness but penetration in commercial fleets remained low in 2024 (roughly 25%), while the competitive field and pricing stay fluid; proven ROI—typical fuel and maintenance savings of 10–20% and uptime gains of 15–30%—drives rapid scaling if integrated effectively.
Lightweight composite bodies can cut vehicle curb weight by 20–30% in 2024 pilots, improving electric range and reducing lifecycle maintenance, but fleet adoption remains cautious. Tooling and manufacturing ramp costs often exceed $5–15M and product validation typically requires 12–24 months, slowing scale-up. If field durability matches targets and reduces maintenance costs by 10–25%, composites become a clear differentiation; run targeted pilot programs with top operators to de-risk rollout.
NFI Question Marks 2024: FCEBs—billions in funding but nascent market; hydrogen infra sparse. FCEB capex risk. Battery-as-service—battery ~$120/kWh (BNEF 2024) needs balance-sheet; telematics penetration ~25% with 10–30% ops savings; composites cut curb weight 20–30% but tooling $5–15M.
| Item | 2024 metric |
|---|---|
| Battery price | $120/kWh |
| Telematics penetration | ~25% |
| Composite weight cut | 20–30% |
| Tooling cost | $5–15M |


