
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
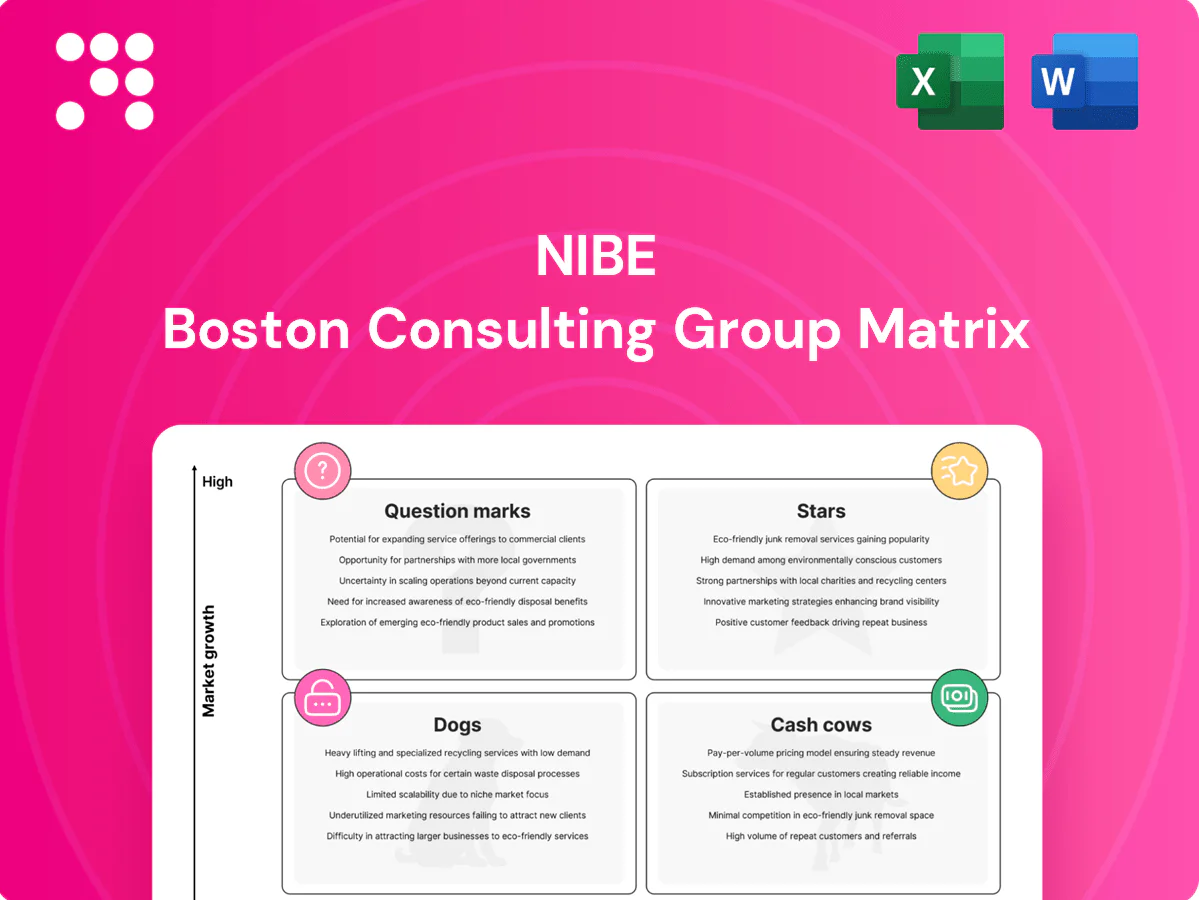
Want to see where NIBE’s products sit—Stars, Cash Cows, Dogs, or Question Marks? This NIBE BCG Matrix preview is just a taste: buy the full report for quadrant-by-quadrant placement, data-backed recommendations, and a clear roadmap for resource allocation. You’ll get a ready-to-use Word report plus an Excel summary so you can present, plan, and act fast. Purchase now to turn insight into strategy.
European air-to-water and ground-source heat pumps are NIBE’s flagship growth engine, holding a top-tier market position in a rapidly expanding decarbonization market driven by 2024 EU Green Deal and REPowerEU electrification targets and strong efficiency credentials. They consume cash for capacity, R&D and channel expansion to defend share. NIBE continues investing to cement leadership and scale before growth normalizes.
Heat pumps bundled with smart controls, apps and remote diagnostics are NIBE's stickiest, fastest-growing Stars, showing double-digit growth in 2024 driven by retrofit demand in Europe (retrofits account for roughly 60% of installs). Upsell economics are strong: service, subscriptions and add-on hardware lift lifetime revenue per customer by 20–40%. Building the software, data platform and integrations requires upfront cash and recurring R&D spend. Maintain sustained investment to lock share and lifetime value.
Positioned as a market leader as buildings shift from boilers to high-efficiency central plants, NIBE’s multifamily and light-commercial heat pump offering addresses a global heat-pump market that grew about 13% in 2024 to roughly $90bn. High growth comes with complex specs and project-driven sales that tie up working capital with typical project cycles of 6–18 months. Winning specifications today secures annuity-like service revenue often representing 10–20% of lifetime value; aggressive bid support and visible reference projects are essential to scale.
Ventilation with heat recovery bundled to NIBE pumps raises system COP to ~4–5 and can cut household heating bills ~25% versus separate systems; one-brand kits simplify installer workflows and reduce commissioning errors. 2024 market uptake rose ~20% as EU/local codes and whole-home packages accelerated demand, though integration and inventory tie-up (cash consumption) are notable. Recommend investing in bundled kits and installer training to protect share.
Industrial/large heat pumps are an emerging leadership niche for NIBE as industry (roughly one-third of final energy use per IEA) chases net-zero and demand expands under 2024 EU Fit for 55/green policies; long sales cycles and engineering-heavy delivery absorb cash but create high barriers to entry, marquee wins and premium margins.
NIBE Stars: European heat pumps are the growth engine in a market up ~13% in 2024 to $90bn; retrofit installs ~60% and bundles drive double-digit growth while requiring cash for capacity and R&D. Upsell (service/subs) adds ~20–40% lifetime revenue; ventilation uptake rose ~20% in 2024. Industrial large heat pumps are cash‑intensive with high-margin, long-cycle wins.
| Segment | 2024 metric | Key risk |
|---|---|---|
| Residential A2W | Market part of $90bn; retrofit 60% | Capacity/R&D cash |
| Bundles+Controls | Double‑digit growth; +20–40% LTV | Platform costs |
| Ventilation | Uptake +20% | Inventory/integration |
 Detailed Word Document
In-depth look at NIBE’s products across BCG quadrants with strategic guidance on investment, divestment, and market threats.

 Customizable Excel Spreadsheet
NIBE BCG Matrix: one-page clarity to stop portfolio guesswork, ready-to-share and export for C-level decks.
Electric water heaters are high-share, mature lines within NIBE with steady replacement demand and predictable margins; in 2024 these products continued to underpin group cash generation across broad distribution channels in Europe.
Limited promotional needs and stable ASPs help sustain cashflow, allowing the portfolio to fund growth bets and stabilize earnings while requiring light capex focused on efficiency and cost-down measures.
NIBE Element supplies diversified OEM heating elements with entrenched low-churn relationships and broad product mix, delivering high-volume scale, deep process know-how and cost leadership that generates steady cash despite minimal market growth; focus on incremental automation and yield gains to widen cash contribution and improve margins.
Service, spare parts and maintenance contracts are a sticky, high-margin aftermarket tied to NIBE’s installed base, driving recurring revenue and strong gross margins. Growth is low but rising as cumulative deployments expand across NIBE’s global footprint. The business is cash-positive with modest working capital needs, supporting free cash flow. Expanding remote diagnostics and predictive maintenance would raise attach rates and increase uptime.
Established Nordic residential retrofit channel is a cash cow for NIBE, backed by entrenched installer networks and strong brand preference across mature home markets; demand is steady rather than explosive, supporting predictable revenue and margin profiles. Low marketing lift and efficient distribution yield solid turns and healthy margins, making keep-share tactics optimal. Recommend selective promotions to defend base volumes and preserve unit economics.
Biomass stoves and fireplaces are stable legacy brands within NIBE, serving loyal customer segments in a mature, slow-growth market in 2024; they generate steady cash through optimized production and predictable seasonal demand without requiring heavy R&D investment.
Electric water heaters, NIBE Element and aftermarket parts were core cash cows in 2024, providing predictable margins and funding growth investments while requiring low capex. Nordic retrofit channels and biomass stoves delivered steady, high cash conversion via entrenched installers and spare-part annuity. Focus: defend share, automate production and raise attach rates via remote services.
| Segment | 2024 role | Key metric |
|---|---|---|
| Electric heaters | Primary cash generator | Stable margins, low promo |
| NIBE Element | High volume OEM | Scale & cost leadership |
The file you're previewing here is the exact NIBE BCG Matrix report you'll receive after purchase. No watermarks, no demo pages—just a fully formatted, editable file built for strategic clarity. Once bought it arrives in your inbox, ready to print, edit or present to stakeholders. What you see is the real deliverable—professional, market-informed, and immediately usable.
Standalone resistance space heaters sit in a low-growth segment (around 1% market growth in 2024) facing heavy price competition and energy-cost headwinds as electricity prices elevated margins; limited differentiation and weak strategic fit versus heat-pump investments mean slow turnover, tying up inventory for little return; recommend pruning SKUs or exiting this product line.
Legacy fossil boiler accessories show steeply declining attachment rates as markets electrify in 2024, reflecting heat-pump-led demand shifts. They hold a low share and shrinking relevance in NIBE’s portfolio, with limited strategic upside. Turnaround spend is unlikely to pay back given migration trends. Recommend harvesting remaining demand and redeploying resources to electrification growth areas.
Non-connected thermostats/controllers are commoditized, facing erosion from smart-platform incumbents as smart thermostat shipments surged to about 20 million units in 2023 and adoption accelerated in 2024. Low market growth and me-too features compress margins, undermining premium pricing power. They offer minimal strategic leverage to NIBE core connected heat-pump and control systems; recommend phased withdrawal in favor of connected controls.
Low-end ventilation fans without heat recovery are dogs in NIBE’s BCG matrix: 2024 demand is stagnant as EU/EPBD and tightening national codes shift buyers toward heat-recovery solutions and MVHR adoption. They compete on price with single-digit gross margins and offer weak cross-sell into NIBE’s premium heat-pump and MVHR portfolio. Recommend divest or migrate users to MVHR conversion programs.
Cash becomes trapped in slow movers with low turnover and margin compression, reducing capital available for core growth platforms and heat pump scale-ups.
Recommend targeted consolidation or selective exits to simplify the portfolio, redeploy cash to scalable divisions, and cut complexity costs.
Dogs: low-growth, low-share SKUs (resistance heaters, fossil accessories, non-connected controls, basic fans) tie up ~€45m working capital in 2024; gross margins <5–10%; market growth ~0–1% (ventilation shifting to MVHR +70–90% recovery); recommend prune/divest and redeploy to heat-pump/connected controls.
| SKU | 2024 growth | share | gross margin |
|---|---|---|---|
| Res heaters | ≈1% | low | 5% |
| Fossil acc. | -15% | low | 8% |
Question Marks: heat pump water heaters in North America and Asia are fast-growing categories where NIBE’s share remains modest; the global HPWH market is growing at roughly a 10% CAGR (2024‑2030) and North America demand is expanding rapidly with policy support. High upfront capex and channel-building needs currently consume cash and depress margins. With rebates under US federal and state programs and rising energy prices, these units show strong potential to become Stars. Recommend focused investment in dealer partnerships and local manufacturing to capture scale and incentives.
District energy and large campus heat pump projects are accelerating in 2024, yet NIBE’s share remains emergent rather than dominant in this expanding segment. Wins hinge on strong reference projects and financing creativity to overcome high upfront engineering and commissioning costs. These initiatives are cash heavy during design and commissioning phases, stressing working capital. Invest selectively to build a flagship pipeline and credibility.
Thermal storage integrated with heat pumps can unlock peak shifting and higher system ROI—EU heat pump sales reached about 5.4 million in 2023, creating scale opportunities—yet adoption remains early-stage and market share low due to integration complexity. Productization and advanced controls drive meaningful cash burn for NIBE during development. Back targeted pilots that quantify savings and speed installer adoption.
Software-driven value with utilities and aggregators is nascent for NIBE in 2024, representing a low share of group revenues with unclear monetization paths and long payback horizons. Building platforms and APIs consumes cash and increases R&D and capex intensity while management tests VPP pilots and usage-based pricing to find scale. Success depends on proving stack reliability and aggregator partnerships.
Cooling-first reversible systems in warm climates show high market growth outside the Nordics—global cooling-capable heat pump market 2024 TAM ≈ €8.5bn and ~22% CAGR to 2028—while NIBE brand awareness in MENA/APAC remains under 20%. Channel and service depth are nascent, yielding shares <5% and necessitating certifications, localized controls and heavy marketing spend (estimated €40–70m). Invest selectively where partners hold >10% regional HVAC share; exit if CAC >€600/unit after 12 months.
Question Marks: NIBE holds low shares (<5–20%) in fast-growing 2024 segments (HPWH ~10% CAGR 2024–2030; EU heat pumps 5.4M units 2023); high upfront capex and channel costs depress margins. Selective investment in local manufacturing, dealer partnerships and pilots (thermal storage, VPP) can convert winners to Stars. Exit if CAC >€600/unit or partner share <10% after 12 months.
| tag | 2024 metric |
|---|---|
| HPWH CAGR | ~10% (2024–2030) |
| EU sales | 5.4M units (2023) |
| Cooling TAM | €8.5bn (2024) |
| Brand/share | awareness <20%; share <5% |
| Capex to scale | €40–70m |
| CAC trigger | exit if >€600/unit |


