
Digital download
Access the files immediately after checkout.
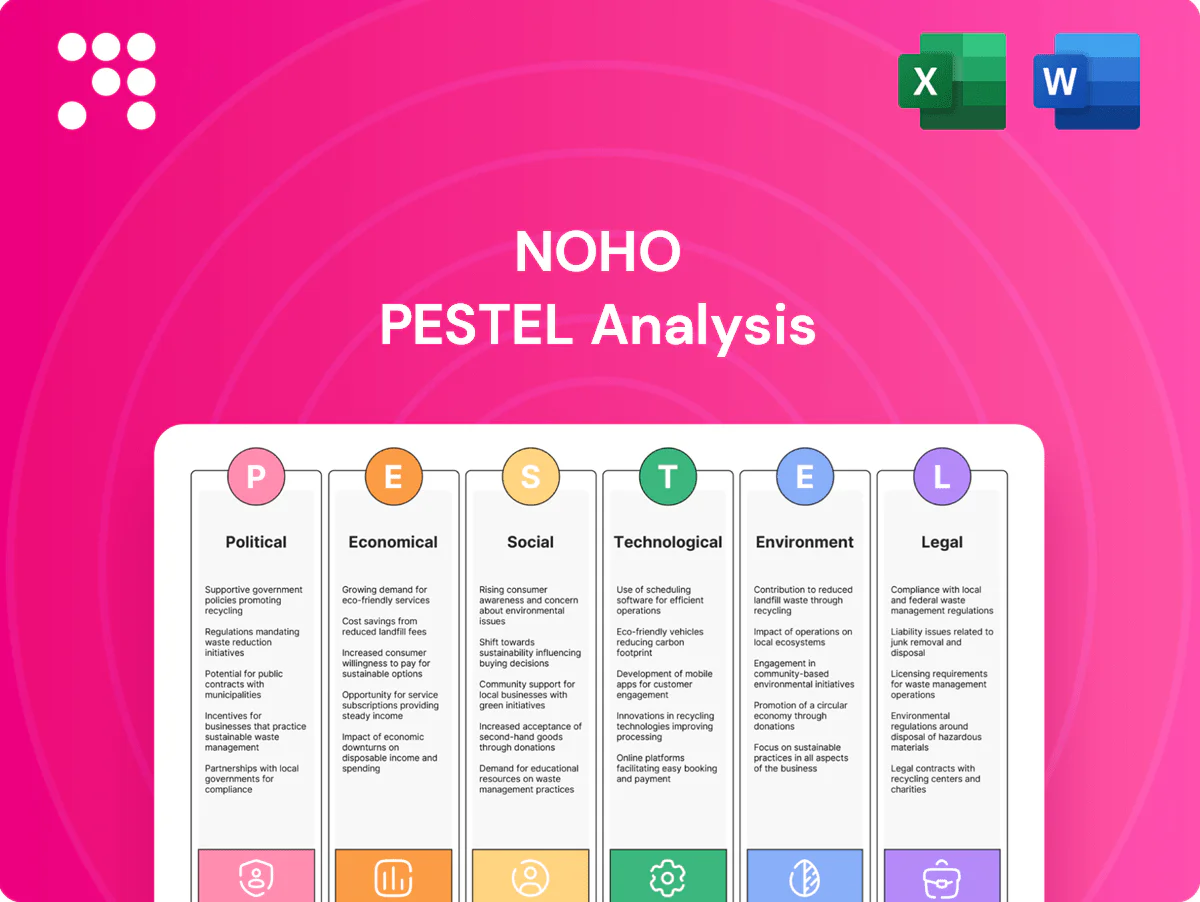
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
Gain strategic clarity with our NoHo PESTLE Analysis—concise, research-backed insights on political, economic, social, technological, legal and environmental forces shaping NoHo’s future. Perfect for investors and strategists seeking actionable intelligence; purchase the full report to access the complete, ready-to-use breakdown instantly.
Finland’s alcohol regime (grocery sales allowed up to 5.5% ABV since 2018 and state retail via Alko) shapes serving hours, beverage mix and venue formats; Alko operated about 350 stores in 2024. Tightening municipal rules or earlier closing times can cut late‑night revenue, while liberalisation typically boosts bar turnover. NoHo must keep compliance agility across municipalities and adapt for varied international alcohol frameworks.
Local councils control terrace permits, noise limits, and late-hour approvals in NoHo, with New York City land-use reviews (ULURP) typically taking 5–7 months and discretionary approvals common. Delays or denials can cap capacity and shave seasonal earnings for hospitality businesses. Strong stakeholder relations help secure favorable terms. Urban development plans may unlock prime sites or force relocations.
Government health campaigns shape nightlife expectations and crowd management after WHO estimated 14.9 million excess deaths during 2020–21, driving ongoing public messaging and compliance checks. Post-pandemic norms keep hygiene and occupancy under scrutiny, with many venues reporting sustained demand for distancing and sanitization. Policy shifts could reintroduce restrictions during shocks, but proactive standards reduce disruption and rebuild consumer trust.
EU food standards, the 2021 VAT e-commerce rules and an average EU standard VAT rate of 21.4% (2024) plus Green Deal targets (Farm to Fork: 50% pesticide reduction by 2030) heighten compliance and capex for NoHo; geopolitical tensions (eg. Russia–Ukraine) pushed Dutch TTF gas to ~€345/MWh in Aug 2022, lifting energy costs and weakening travel demand while UNWTO shows arrivals at ~93% of 2019 in 2023.
Political environment: Finland alcohol regime (grocery sales to 5.5% ABV; Alko ~350 stores in 2024) and varied municipal permits/ULURP (NYC 5–7 months) affect hours, capacity and revenue. Nordic collective bargaining (70–90%) raises labour costs; migrant hires +15–20% (2023–24) eased staffing. EU avg VAT 21.4% (2024) adds cost pressure.
| Indicator | Value (yr) | Impact |
|---|---|---|
| Alko stores | ~350 (2024) | Distribution control |
| ULURP | 5–7 months | Approval delay risk |
| Collective bargaining | 70–90% | Wage pressure |
| Migrant hires | +15–20% (2023–24) | Staffing relief |
| EU VAT | 21.4% (2024) | Price/cost impact |
 Detailed Word Document
Explores how Political, Economic, Social, Technological, Environmental and Legal forces uniquely affect the NoHo, combining data-backed trends and forward-looking insights to identify risks and opportunities; formatted for easy insertion into business plans, decks, and strategy work for executives and investors.

 Customizable Excel Spreadsheet
A concise, shareable NoHo PESTLE summary that’s visually segmented for quick interpretation and team alignment, editable for local context or notes and ready to drop into presentations or planning sessions.
Discretionary dining and nightlife are highly cyclical, with food away from home accounting for roughly 50% of U.S. food spending in 2023–24. Weak consumer confidence shifts demand toward value formats and earlier dayparts as households trade down. Premium concepts capture share when real incomes rise, supported by wage gains and falling inflation in 2024. A dynamic portfolio mix buffers revenue swings across cycles.
FAO Food Price Index averaged 118 in 2024, reflecting continued volatility in proteins, grains and beverages that pressure restaurant margins. Menu engineering and fixed-price supplier contracts are key levers to protect margin while minimizing customer price shock. Passing through price hikes risks traffic declines seen across the sector when food inflation spikes. Centralized procurement can stabilize costs through scale and longer-term hedges.
Labor is a major cost driver in hospitality, typically 25–35% of revenue; tight U.S. labor markets pushed wage growth in leisure and hospitality over 6% y/y in 2023–24 and sustained high turnover (annual rates often 50–70%). Training and tech-enabled workflows can raise throughput per FTE by 15–25%, while flexible scheduling cuts peak-hour overstaffing and can trim labor costs ~5–10%.
Higher policy rates (~5% mid-2025) raise lease, debt and expansion costs for NoHo, squeezing returns as commercial lending spreads remain wide (bank spreads ~150–300bps), so capex must show quick payback to preserve cash flow; sale-leaseback and franchising de-risk the balance sheet, while eventual rate cuts would reopen growth optionality.
Inbound travel (UNWTO: international arrivals ~88% of 2019 in 2023) lifts city-center venues and late-night F&B, while Nordic seasonality (summer peaks) forces event-driven programming; airport and arena locations reflect traffic volatility (IATA: 2023 passenger traffic ~83% of 2019), and international units smooth demand cycles across quarters.
Discretionary dining remains cyclical: food away from home ≈50% of U.S. food spend (2023–24), favoring value formats when confidence falls. FAO Food Price Index averaged 118 in 2024, pressuring margins; passing costs risks traffic loss. Labor = 25–35% revenue with leisure wages +6% y/y (2023–24); tech and training raise FTE productivity. Policy rates ~5% (mid-2025) lift lease/debt costs, prioritizing quick-payback capex.
| Metric | 2023–25 Value | Impact |
|---|---|---|
| Food away from home | ≈50% | Demand shifts, trade-downs |
| FAO Food Price Index | 118 (2024) | Margin pressure |
| Labor cost | 25–35% rev; wages +6% y/y | Higher Opex |
| Policy rates | ~5% (mid-2025) | Higher debt/lease costs |
The preview shown here is the exact NoHo PESTLE Analysis document you’ll receive after purchase—fully formatted and ready to use. The layout, content, and structure are identical to the downloadable file with no placeholders or teasers. After checkout you’ll instantly get this finished, professionally structured report.
Consumers in NoHo increasingly prioritize memorable, themed and social dining: 72% say Instagrammable experiences influence venue choice (2024 industry survey). Live entertainment and curated menus lift dwell time and average check—operators report up to 20% higher spend on event nights. Concepts need refresh cycles every 9–12 months to avoid fatigue. Regular community events raise repeat visits and membership loyalty by double-digit percentages.
Rising demand for low/no-alcohol and healthier dishes reshapes NoHo menus as consumers prioritize wellness; the global functional beverages market was valued at $117.1 billion in 2023 (Grand View Research), signaling strong category growth. Transparency on ingredients and allergens builds trust and supports repeat visits amid broader public-health concerns—noncommunicable diseases caused 74% of global deaths (WHO, 2020). Portion control and functional beverage offerings let operators balance indulgence and wellness occasions within diversified portfolios.
Young adults power NoHo nightlife while families tilt toward casual daytime formats; tailoring offers captures both as urban cores concentrate customers—UN data show 56% of people lived in cities in 2020, rising to 68% by 2050. Aging cohorts favor comfort, accessibility and value: the 65+ share was about 9% globally in 2020 and is projected to reach 16% by 2050, signaling demand for age-friendly concepts. Tailored concepts can target each cohort efficiently within dense urban footfall and local sensitivities.
Patron safety, clear anti-harassment policies, and responsible serving are baseline expectations for NoHo venues, with visible measures such as CCTV and doorstaff increasing customer comfort and repeat visits.
Partnerships with local police and licensing authorities demonstrably reduce incident risk and improve response times, while mandatory staff training ensures consistent application of policies.
Multicultural NoHo, within Los Angeles County where foreign-born residents are about 37% (ACS 2019–2023), broadens demand for authentic global flavors and raises authenticity expectations; rotating kitchens and collaborations, backed by the $49B+ U.S. ghost-kitchen/virtual brand market (2023), keep menus fresh, while seasonal and regional dishes drive novelty and urgency.
NoHo patrons favor themed, social dining (72% say Instagrammable influences choice, 2024), wellness options (functional beverages market $117.1B, 2023) and multicultural authenticity (LA County foreign-born ~37%). Safety, anti-harassment and trained staff are baseline; ghost kitchens ($49B, 2023) enable rotating menus.
| Metric | Value |
|---|---|
| Instagrammable preference | 72% (2024) |
| Functional bev. market | $117.1B (2023) |
| LA foreign-born | ~37% (ACS 2019–2023) |
| Ghost-kitchen | $49B (2023) |
Reservation platforms and waitlist tools smooth peaks, with leading providers reporting 20-40% faster table turnover; dynamic pricing and time-based offers can lift seat utilization 10-25%. Integrated CRM personalizes outreach, driving 15-30% higher repeat bookings. No-shows fall by up to 70% when deposits and automated reminders are used.
Unified POS provides real-time sales, mix, and labor insights across outlets, and chains reporting unified systems saw operational visibility improve by ~30–40% in 2024; SKU-level tracking across hundreds of items enables menu optimization and SKU rationalization that can lift gross margin by 1–3%; interactive dashboards drive swift fixes, cutting incident response times ~40%; strong data governance underpins accuracy and 85%+ adoption rates.
Combi ovens, advanced prep tech and IoT sensors standardize quality and can cut cook times and variability by ~20–30%, while table-ordering and QR pay workflows have accelerated table turns by 15–25% in recent industry surveys. Automation cuts order errors and food waste—sensors often drive 10–30% waste reductions—and vendors report payback windows typically between 12–24 months depending on throughput and labor-savings.
Aggregator partnerships extend NoHo beyond on-premise, with global online food delivery spending ~USD 300B in 2024 and platform reach increasing orders 20–40% vs dine-in; virtual brands convert off-peak capacity into 10–25% incremental revenue; packaging and menu engineering limit quality loss and add ~3–6% to COGS; commissions (15–35%) can cut gross margins by ~10–20 p.p., so channel mix must be optimized.
Card data, loyalty records and staff systems are frequent attack targets; PCI compliance, MFA and network segmentation materially lower breach risk and scope. Payment outages directly cut sales and can halt operations; contactless and mobile wallets, now used in over 50% of card transactions in many markets (2024), speed checkout and raise throughput.
Reservation tools speed table turns 20–40% and dynamic pricing lifts utilization 10–25%. Unified POS raised visibility ~30–40% in 2024; SKU tracking can add 1–3% gross margin. Automation/IoT cuts waste 10–30% with 12–24 month paybacks. Delivery market ~USD300B (2024); commissions 15–35% can shave 10–20 p.p. margin; contactless >50% of card txns (2024).
| Metric | Typical Impact |
|---|---|
| Reservation/platforms | +20–40% turns |
| Unified POS | +30–40% visibility |
| Automation/IoT | Waste -10–30% |
| Delivery market | USD300B (2024) |
| Commissions | 15–35%, -10–20 p.p. |
Under the Licensing Act 2003 strict compliance governs serving times, age checks and promotions, with breaches exposing operators to licence suspension or revocation and unlimited fines. Local council variations in permitted hours and cumulative impact policies complicate multi-site operations across boroughs. Continuous staff training and regular internal audits are essential to mitigate enforcement risk and licence reviews.
HACCP, inspections and traceability are non-negotiable under EU law (Regulation (EC) No 852/2004 and No 178/2002) and require documented controls at all stages. Supplier vetting and cold-chain controls (refrigeration <5°C per WHO guidance) prevent incidents. Violations trigger RASFF notifications and rapid recall protocols that must be executable immediately to limit exposure and protect brand equity.
Working hours, overtime and scheduling are tightly regulated under Finland’s Working Hours Act and collective bargaining, which covers roughly 90% of Finnish employees and sets wage floors and benefits; NoHo, a ~5,000-employee restaurant operator, must follow these rules. Collective agreements pushed hospitality pay higher in recent rounds, raising labor costs. Missteps lead to penalties, back-pay and reputational harm. HR systems must encode legal norms and collective terms.
GDPR governs guest data, CCTV use and marketing consent across NoHo operations; explicit consent and legitimate interest records are required. Data minimization, purpose limitation and clear retention schedules are mandatory, with secure deletion policies. Breaches can trigger fines up to €20 million or 4% of global turnover and average breach costs ~ $4.45M (IBM 2023). Vendor contracts must include GDPR clauses, DPA, and audit rights.
The EU Corporate Sustainability Reporting Directive (CSRD) expands sustainability disclosure to about 50,000 companies with European Sustainability Reporting Standards (ESRS) from 2024–2026, raising transparency demands; the EU Accessibility Act (application from June 2025) requires improved venue accessibility, affecting design and refurbishment planning; non-compliance can restrict permits and audience access; standardized metrics improve investor communication.
Licensing, HACCP and employment law create high compliance burdens across NoHo’s ~5,000 staff and multi-site estate; collective agreements cover ~90% of Finnish workers, raising labour costs. GDPR/CTV rules demand consent, DPAs and can levy €20M or 4% global turnover; avg breach cost $4.45M (IBM 2023). CSRD (~50,000 firms) and EU Accessibility Act (from 28 Jun 2025) add reporting and retrofit obligations.
| Risk | Law | Impact | Penalty |
|---|---|---|---|
| Data breach | GDPR | Operational disruption | €20M/4% turnover |
| Food safety | Reg 852/2004 | Recalls, RASFF | Immediate recall |
Commercial kitchens can drive 30–50% of a venue’s energy load, with energy and tax shifts pushing operating costs substantially; global corporate renewable PPAs hit record ~31 GW in 2023 as firms chase price stability and ESG credentials. LED lighting can cut lighting use by up to 70%, smart HVAC typically trims 10–30% of HVAC demand, and heat-recovery systems can reclaim up to ~80% of exhaust heat. Site energy audits focus on high-ROI measures with paybacks often under 3–5 years to prioritize upgrades that immediately lower fuel and electricity spend and support renewable sourcing for ESG reporting.
NoHo can cut overproduction 10–25% using waste tracking and AI forecasting, addressing part of the 1.3bn tonnes of global food waste (FAO). Partnerships for surplus redistribution can redirect ~5–10% of excess to social programs, while portion and menu design can lower plate waste 20–30% (WRAP), saving roughly 2–5% of food costs and improving margins and footprint.
Local, seasonal and certified inputs can cut supply-chain food-miles and related emissions — studies show farm-to-fork sourcing often lowers Scope 3 emissions by 10–30%. Guests increasingly expect sustainable seafood and meat policies, with industry surveys reporting 60–70% of diners consider sustainability when choosing restaurants. Reusable or recyclable packaging reduces off-premise waste (single-use diversion rates can exceed 50% with reuse schemes). Supplier scorecards drive compliance, cutting audit failures by ~30% within 12 months.
Dishwashing and sanitation are the largest drivers of kitchen water use; replacing old pre-rinse valves with WaterSense-rated models (1.28 gpm) can cut water use ~30–40% versus older valves, lowering utility and heating costs. Low-flow fixtures and process tweaks further trim consumption. Grease-trap management prevents blockages and municipal fines often ranging $500–5,000. Smart metering/leak monitoring can detect leaks and reduce water loss up to 30%.
Extreme weather can disrupt supply chains and suppress demand; 2023 insured losses from natural catastrophes exceeded $120 billion, illustrating potential financial impact. Business continuity plans and diversified suppliers mitigate shocks. Insurance and targeted building upgrades reduce loss severity, while prompt communications keep guests informed during events.
Energy (commercial kitchens 30–50% site load) and 31 GW global corporate PPAs (2023) push NoHo to LEDs (−up to 70%), smart HVAC (−10–30%) and heat-recovery (~80% exhaust). Food waste 1.3bn t globally; AI/waste tracking can cut 10–25% production losses and 2–5% food cost. Water: pre-rinse retrofit saves 30–40%; leak detection −30%. Extreme weather insured losses >$120bn (2023).
| Metric | Value |
|---|---|
| Kitchen energy share | 30–50% |
| PPAs (2023) | ~31 GW |
| Food waste | 1.3bn t |
| Water retrofit | 30–40% |
| Insured losses (2023) | >$120bn |


