
Digital download
Access the files immediately after checkout.
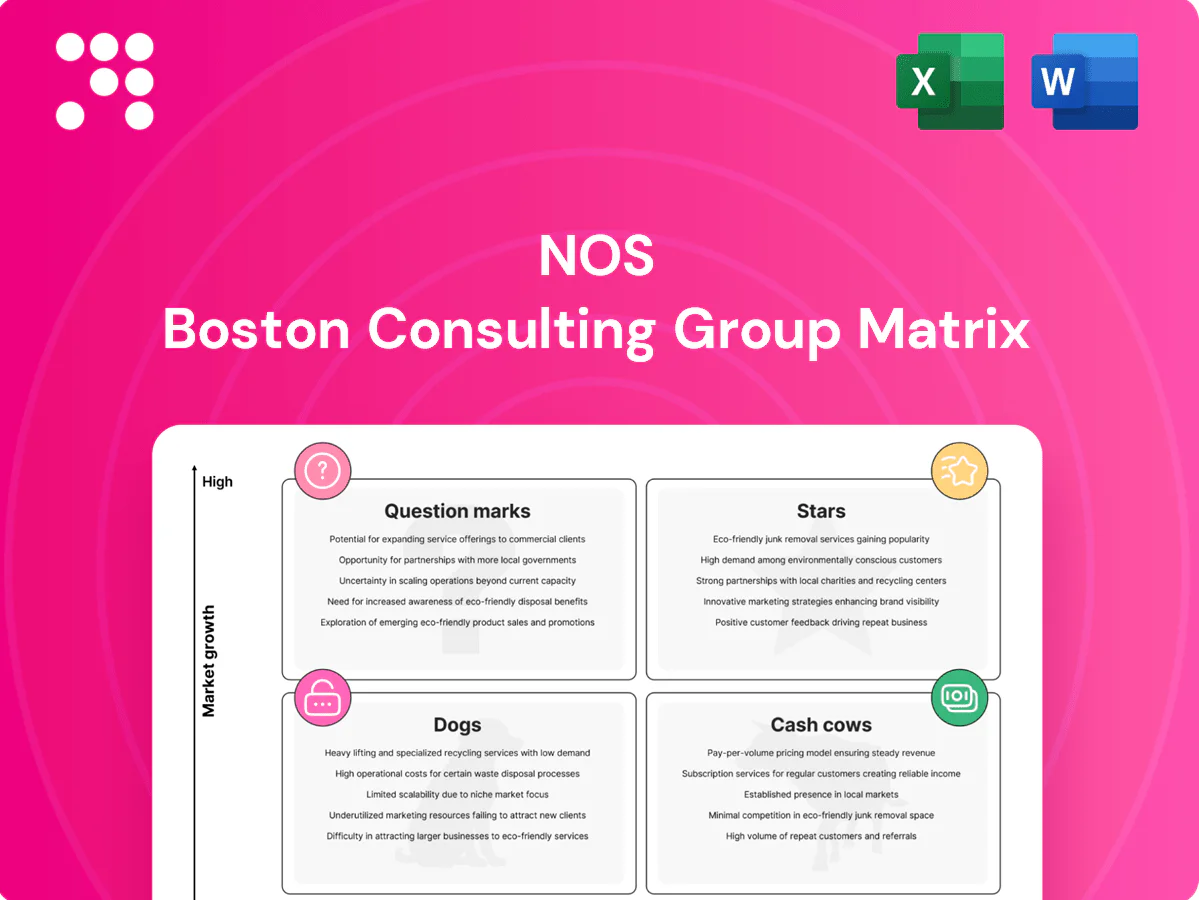
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
This preview shows the shape of the NOS BCG Matrix, but the full report tells you which products are winning, which are bleeding cash, and where to double down. Purchase the complete BCG Matrix for quadrant-by-quadrant analysis, data-backed recommendations, and a clear roadmap to smarter resource allocation. You’ll get ready-to-use Word and Excel files, visual maps, and practical next steps—no fluff, just strategy you can act on. Buy now and skip the guesswork.
5G mobile services are a Stars business for NOS, combining an estimated 35–36% mobile market share in 2024 with surging data demand; leading on network quality, speed and national coverage lets NOS lock premium postpaid customers. Heavy capex (roughly €300–350m in 2024) is required now but positions the company for sustainable ARPU gains. Keep disciplined promotion and targeted placement to protect yield.
Portugal reached over 80% FTTH coverage in 2024 and household fiber subscriptions approached 60% penetration, leaving room for further uptake; NOS is well positioned to capture incremental demand. Fast, reliable home internet behaves like a utility with low churn when experience is excellent. Pushing higher speed tiers and Wi‑Fi 6/7 will protect share; invest now so FTTH matures into a cash cow.
Converged bundles (mobile + TV + internet + fixed) act as a Star by driving FMC share and materially reducing churn, exactly aligning with BCG expectations. Simple bundles and sharp pricing lock in families and SMEs, while add-on perks such as streaming, cloud storage and device financing lift ARPU. Aggressive retention and upsell create a defensive flywheel around NOS’s core customer base.
Enterprise mobility and IoT on 5G is a clear Stars opportunity for NOS as industrial use‑cases (fleet telematics, pervasive sensors, edge video analytics) move from pilots to recurring, sticky service revenue; early 2024 proofs drive references and scalable contracts. Success requires solution selling and partner ecosystems, but market momentum and recurring ARPU uplift justify prioritization.
Customers demand a single gateway for apps, channels and billing; NOS can curate and bundle major streamers with linear TV to deliver a premium experience, leveraging the 1.1 billion+ global paid streaming subscriptions in 2024 and Portugal's rising OTT uptake. High engagement from bundled UX and integrated billing protects share and raises ARPU; maintaining exclusive deals (content and platform) is critical to sustain growth.
5G, FTTH and converged bundles are Stars for NOS: ~35–36% mobile share (2024), FTTH coverage >80% with ~60% household fiber subscriptions (2024), and converged bundles drive ARPU uplift and lower churn. 2024 capex ~€300–350m prioritizes 5G/FTTH and enterprise IoT to secure premium, recurring revenue.
| Metric | 2024 |
|---|---|
| Mobile share | 35–36% |
| FTTH coverage | >80% |
| Fiber households | ~60% |
| Capex | €300–350m |
 Detailed Word Document
Comprehensive BCG Matrix review of NOS products, with quadrant insights, investment recommendations and trend context.

 Customizable Excel Spreadsheet
One-page BCG snapshot that clarifies portfolio pain points and guides quick decisions.
Cash Cows:
NOS’s mature home broadband tiers generate dependable cash from a large installed base—Portugal had about 3.4 million fixed broadband accesses in 2023 (Anacom), concentrating recurring revenue. Incremental capex per additional customer is minimal once the network is built, letting upgrades and modem rental fees materially lift margins. Maintaining tight service quality is critical to protect pricing and churn in a saturated market.
In 2024 NOSs set‑top box and equipment rentals sit in the BCG Cash Cow quadrant: low growth but high revenue predictability. Hardware is largely amortized and rental fees are sticky, driving steady ARPU contribution. Incremental features like voice remote and cloud DVR justify modest price points. Strategy: maintain service levels and cap investment; optimize costs rather than scale capex.
Business fixed connectivity (legacy contracts) remains a cash cow for NOS, with legacy lines and MPLS/VPNs accounting for roughly 18% of enterprise fixed revenue in 2024, delivering steady EBITDA margins as clients rarely churn. High switching costs and bundled services protect margin in mature accounts, while onboarding and provisioning efficiency gains trim OPEX and boost cash conversion.
NOS holds a leading share in Portuguese cinema distribution and exhibition with a stable slate that yields dependable cashflow; predictable release windows and merchandising underpin steady concession and ticket revenue. Optimize screen allocation, dynamic scheduling, and higher-margin concessions to expand operating margin while keeping capex disciplined to protect free cash flow.
Cash Cows: Pay TV ~1.5M subs (2023), fixed broadband ~3.4M accesses (2023), hardware rentals and legacy enterprise contracts deliver steady EBITDA; prioritize retention, ARPU uplift, cost optimization and limited capex to maximize FCF.
| Segment | 2023/24 | Metric |
|---|---|---|
| Pay TV | 1.5M subs | Predictable cash |
| Broadband | 3.4M accesses | Recurring revenue |
| Hardware/Enterprise | 2024 steady | High margin |
The file you're previewing is the exact BCG Matrix report you'll receive after purchase—no watermarks, no placeholders, just the finished, fully formatted document. It’s crafted for immediate use in strategy sessions, decks, or client work and arrives ready to edit, print, or present. Purchase unlocks the same file shown here—clean, professional, and exactly as previewed.
Legacy fixed voice (PSTN) is a BCG Dog: near-zero growth and sharply shrinking usage—fixed-voice revenue fell double digits across many European operators in 2023–24. Maintenance, OSS and CPE support eat cash with minimal ARPU upside. Keep for bundle completeness but minimize exposure and sunset where feasible.
Satellite TV (DTH) is a Dogs quadrant play as cord‑cutting and expanding FTTH have eroded demand, with pay‑TV household penetration down over 10% since 2019 and continuing declines into 2024. Equipment and service margins are thin, making large capex or marketing pushes unjustified. Focus only on rural niche pockets where DTH still outperforms OTT; avoid turnaround spend and prioritize cash preservation.
OTT messaging — WhatsApp with 2+ billion users in 2024 — effectively killed standalone SMS/MMS demand; consumer revenues are now a trickle while operational complexity and legacy costs persist. Bundle SMS/MMS quietly inside plans without marketing emphasis, and divert sales and product focus to high-growth data, fiber and value-added B2B services.
Legacy copper/DSL assets are obsolete versus fiber, often delivering under 30 Mbps on ADSL-era lines and showing higher fault rates as metallic pairs age; upkeep becomes a cash trap as OPEX per line grows while subscribers decline. Decommission with a clear migration plan to FTTx aligned with the EU Digital Decade 1 Gbps by 2030 goal, and salvage ducts, cabinets and recyclable metals fast.
Dogs: Physical media tie-ins (DVD/merch) sit as low-growth, low-share items in the NOS BCG matrix; digital accounted for over 80% of home entertainment revenue by 2024, swallowing traditional sell-through. Inventory risk is high with poor turns and SKU obsolescence; maintain physicals only as niche add-ons at cinema windows and licensed merch; otherwise plan an exit to free working capital.
Legacy PSTN, DTH, SMS/MMS and copper DSL are NOS BCG Dogs: double‑digit fixed‑voice revenue declines in 2023–24, pay‑TV penetration down >10% since 2019, WhatsApp 2+bn users (2024), ADSL <30 Mbps; low margins, rising OPEX, urgent FTTx migration and decommissioning to free cash.
| Asset | 2024 metric | action |
|---|---|---|
| PSTN | double‑digit decline | sunset |
| DTH | pay‑TV -10%+ since 2019 | rural niche only |
| DSL | <30 Mbps | FTTx migrate |
Private 5G is a high-growth market, with industry forecasts projecting roughly 35–40% CAGR through 2028, but current operator shares remain early and fragmented; NOS can scale rapidly if it secures lighthouse projects. Success requires certified ecosystem partners and strict SLAs for industrial-grade uptime. NOS must either invest decisively or exit—straddling will waste cash.
Demand for smart home and security bundles is rising—the global smart home market reached roughly USD 96 billion in 2024—yet competition is crowded with global players. NOS can win on superior install, local support, and simplified consolidated billing. Cross‑sell into its ~1.6 million fiber household base to drive initial traction. Use test‑and‑learn pilots and double down where uptake and ARPU lift are proven.
Cloud security and managed services for SMEs are a Question Mark: around 65% of SMEs prefer a single vendor for connectivity, endpoint, SASE and backups but awareness of SASE and integrated bundles remains uneven in 2024. Bundling connectivity with endpoint protection, SASE and backups raises stickiness and can lift ARPU. Margins can be attractive if delivery scales; prove unit economics (CAC payback, gross margin >40%) before broad rollout.
Gaming and low-latency 5G/edge is a Question Mark: compelling market story but uncertain willingness to pay. Global gaming audience ~3.2 billion (2024) and ~1.3 billion 5G connections (2024) signal scale, yet monetization is unproven. Partner with platforms to unlock demand; run trial cities and measure churn and ARPU uplift. If it moves ARPU, lean in—if not, cut.
Question Marks: original NOS productions face rising production costs and hit risk in 2024, but offer strong upside via differentiation—exclusive local content can anchor TV bundles and justify higher ARPU if it drives lower churn (European SVOD churn ~8–10% in 2024). Start targeted with genres proven to convert to subs; if titles fail to lift retention, pivot to smarter licensing and IP partnerships.
Question Marks: invest decisively in private 5G (35–40% CAGR to 2028) and smart home (USD96B 2024) where NOS can scale via 1.6M fiber homes; validate cloud security bundles (SME single‑vendor 65%) and gaming edge pilots (3.2B gamers, 1.3B 5G connections 2024); cut if CAC payback fails or ARPU/churn targets miss.
| Item | 2024 metric | Decision trigger |
|---|---|---|
| Private 5G | 35–40% CAGR | lighthouse wins |
| Smart home | USD96B | cross‑sell to 1.6M |
| SME bundles | 65% single vendor | gross margin >40% |
| Gaming/edge | 3.2B gamers;1.3B 5G | ARPU uplift |


