
Digital download
Access the files immediately after checkout.
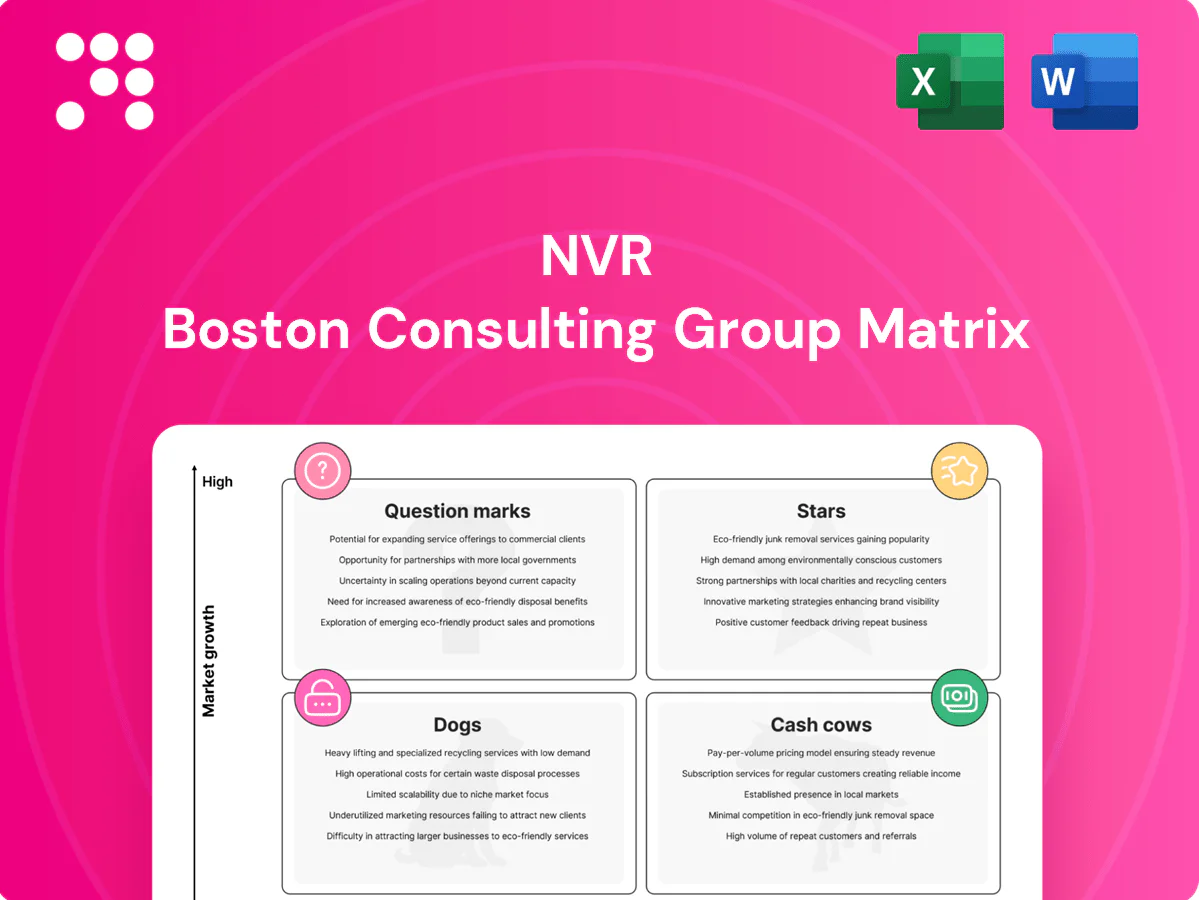
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Quick peek: the NVR BCG Matrix shows which products are scaling, bleeding cash, or just... there. Want the full map—quadrant placements, data-backed recommendations and where to double down? Buy the full report for Word + Excel deliverables and strategic next steps you can act on today.
Ryan Homes holds high share in fast‑growing suburbs where households continue migrating for space and schools, and the lot pipeline remains actively replenished. These communities turn quickly, absorbing promotional spend but repaying it through elevated volume and velocity. Continue feeding lots, sales agents, and digital leads to defend share now; as local growth cools, positions mature into a Cash Cow.
Strong brand recognition in the DC and Mid‑Atlantic townhome segment combined with persistent commuter demand positions NVR as a Star in this market. Absorption remains brisk, yet targeted incentives and marketing accelerate sales velocity and reduce holding costs. Cash in equals cash out on most months, reflecting classic Star operating cash flow dynamics. Continue investing in spec cadence and turnkey quick move‑ins to defend leadership.
High mortgage attach rates inside hot-selling NVR communities drive share and velocity, with purchase-capture programs boosting closed-loan volumes and home-sale economics. It requires ongoing underwriting muscle and rate-buydown spend, so operating costs rise even as every closed loan reinforces the sales-finance flywheel and lifts margin per home. Maintain investment while volumes are elevated; 30-year fixed averaged about 6.9% in 2024, shaping buy-down economics.
Popular elevations and kitchen/bath packages sell themselves when traffic is strong; NVR leverages curated options to accelerate selection and protect margins. Doing so requires showroom staffing, vendor coordination, and tight cycle times to avoid build delays and cancellations. Upsell dollars per contract are material in 2024 and justify the operational investment. Keep the assortment limited and the process fast to maximize conversion.
Optioned‑lot engine lets NVR scale in high‑demand corridors (Sun Belt emphasis) by controlling lots without heavy land ownership; in 2024 NVR delivered about 16,000 homes, demonstrating throughput advantage while keeping capital light.
It demands constant lot sourcing and negotiations—operationally hungry—but yields faster starts and higher capital efficiency; keeping the pipeline full is critical to lock share before rivals expand.
NVR is a Star in fast‑growing suburban and DC townhome markets, converting strong traffic into volume while absorbing promotional and mortgage buy‑down costs; 2024 throughput ~16,000 homes and 30‑yr fixed ~6.9%. Continue funding lots, spec cadence, sales agents and digital leads to sustain velocity; mature markets will shift toward Cash Cow as growth slows.
| Metric | 2024 |
|---|---|
| Homes delivered | ~16,000 |
| 30‑yr fixed rate | ~6.9% |
| Model | Optioned lots, high velocity |
 Detailed Word Document
Comprehensive NVR BCG Matrix analysis: strategic guidance on Stars, Cash Cows, Question Marks, and Dogs with investment recommendations.

 Customizable Excel Spreadsheet
One-page NVR BCG Matrix that maps units into quadrants, easing portfolio decisions and executive alignment.
Ryan Homes' large installed base in Mid‑Atlantic suburbs and strong realtor mindshare drive high repeat‑buyer rates; NVR's FY2024 backlog (~$5.1B) and stable margins let these communities generate dependable cash. Growth has slowed, but share remains solid, so marketing spend is lighter. Milk gently while keeping build quality tight to protect resale velocity and margins.
Established NVHomes premium enclaves feature well-known neighborhoods with only limited remaining phases, driving scarcity value and steady demand. Buyers in 2024 arrive largely pre-qualified and expect a smooth, concierge-like buying experience, reducing sales friction. Promotional spend is minimal, margins remain resilient, and proceeds are deployed to fund newer growth bets within NVR’s development pipeline.
Heartland Homes, NVRs recognized regional brand in core Pittsburgh areas, delivers steady, loyal local demand with consistent traffic and referral-driven sales rather than high growth. It requires low incremental marketing and operational spend to maintain throughput, supporting free cash flow generation. In FY2024 NVR reported about $9.1 billion in revenue and $2.24 billion in net income, with Heartland contributing stable cash to corporate needs.
Service, warranty, and closing efficiencies are a process play for NVR that quietly prints cash via scale, turning routine post-sale work into recurring margin. Predictable volumes enable tighter scheduling, fewer callbacks, and stronger vendor terms, lowering cost per home. Continued investment in operations and IT squeezes incremental margin, and the cash flow underwrites bolder land and product moves.
Standardized plans and repeatable elevations drive high reuse and low redesign at NVR, cutting cycle times roughly 25% and reducing material waste about 15% in repeat-build communities; marketing becomes plug-and-play and trades operate with consistent routings, making this a steady-margin engine in stable markets.
NVR's cash cows—Ryan Homes, NVHomes, Heartland—produce steady free cash via scale, low marketing, and repeat SKUs; FY2024 backlog ~$5.1B, company revenue $9.1B, net income $2.24B underpin liquidity. Operational efficiencies (≈25% faster cycles, ≈15% less waste) and service/warranty leverage compress costs and boost margins. Cash funds land buys and selective growth while marketing stays light.
| Segment | Role | FY2024 metric |
|---|---|---|
| Ryan Homes | High-repeat cash generator | Backlog ~$5.1B |
| NVHomes | Premium steady cash | Low promo, resilient margins |
| Heartland | Local steady cash | Supports corporate FCF |
The file you're previewing here is the exact NVR BCG Matrix you'll receive after purchase. No watermarks, no demo text — just a fully formatted, professional report ready for editing, printing, or presenting. It was built for strategic clarity and immediate use. Once bought, the final file is delivered instantly to your inbox.
Urban condo one‑offs face fragmented demand and thin absorption; 2024 condo sales represented a small single-digit share of new-home closings, raising vacancy and resale risk. HOA constraints and assessment exposure (median HOA dues ~$380/month in 2024) add operating friction. NVR lacks scale in small infill towers, so cash is tied up while returns lag; exit or avoid unless scale economics can be achieved.
Outlier markets with thin trade base show low share and no clear path to density, often flagged in NVR's FY2024 portfolio reviews as candidates for exit.
Vendor pricing is higher, schedules slip and customer complaints rise, pushing many such markets to break-even or negative contribution margins in FY2024 operating results.
Recommend divest or consolidate operations into nearby strongholds to cut overhead and redeploy capital to higher-density regions.
Niche customizations with take rates below 5% jam NVR production lines, increasing throughput time by roughly 10–20% and reducing scheduling slack. They force trade reschedules and raise labor variance without delivering clear pricing power or brand lift, often yielding under a 1% price premium in comparable 2024 housing studies. These options trap working capital and should be cut to restore flow and cash conversion.
Standalone spec communities in stagnant towns face weak population growth (US population rose ~0.4% year-over-year into 2024) and tepid job formation (roughly 180,000 average monthly payroll gains in 2024), keeping absorption slow.
Incentives creep up while gross margins erode as builders increase concessions and carry higher land/holding costs, compressing profitability in 2024.
Inventory risk rises, prompting wind-down phases and redeployment of capital to stronger markets and products.
Refi volumes are scarce and costly to chase in 2024, with refinance share of mortgage applications hovering around 20% per MBA and national 30‑yr rates near 7%, making unit economics poor; effort diverts sales teams and capital from purchase loans tied to home closings where NVR captures primary margin. Low share, low growth — not worth the burn; prioritize purchase capture.
Urban condo one‑offs show low share of new-home closings (~single-digit in 2024), HOA dues median ~$380/mo and thin absorption, driving margin compression and inventory risk. Vendor/schedule issues pushed several markets to break-even in FY2024; recommend divest or consolidate to redeploy capital. Refi effort low ROI (refi ~20%, 30-yr ~7% in 2024).
| Metric | 2024 |
|---|---|
| Condo share | <10% |
| Median HOA | $380/mo |
| Refi share | ~20% |
| 30-yr rate | ~7% |
New Southeast metro entries are Question Marks: big population inflows to the Sun Belt continue per 2024 U.S. Census estimates, but NVR is still building local share and scale. Early sales velocity and absorption look promising, yet expanded marketing and land-partnership investment will require meaningful cash. With the right lot pipeline this could tip into Star territory; without scale it risks stalling toward Dog.
Institutional demand for build‑to‑rent is material, but fit with NVR’s for‑sale model is unproven; pilots of 50–150 units can test different underwriting, longer turn times, and new property‑management partners. Track unit economics closely—target stabilized NOI margins that exceed NVR’s homebuilding threshold before scaling. Invest selectively to learn costs per occupied unit and lease‑up velocity, then expand only if margins clear the bar.
Buyer interest in energy‑efficient/net‑zero bundles is rising as 2024 federal incentives like the Residential Clean Energy Credit now cover roughly 30% of eligible costs, but upfront capex and supply‑chain price volatility keep margins bumpy. If attach rates climb from pilot levels to >20–30%, this offering becomes a brand‑differentiating Star; if not, it stays an expensive nice‑to‑have. Test pricing, simplify packages, and track conversion daily to pivot quickly.
Digital lead gen is robust: in 2024 about 68% of buyer interactions begin online, yet full click-to-close remains rare, estimated at ~12% of closings; investing in UX, 3D/virtual tours and financing pre-approvals can shorten cycle times and lower CAC. If those investments reduce CAC and accelerate velocity, the segment can migrate from Question Mark to Star; if adoption stalls, concentrate on core digital tools and cut spend.
Newtown-home series targets entry buyers where affordability is the unlock but margins are thin; with U.S. mortgage rates around 7% in 2024 demand is price‑sensitive. If vendor costs and standardized plans hold, share can ramp quickly, but success requires a marketing push and strict spec discipline. Invest with guardrails and be ready to pivot fast if absorption misses.
Question Marks: Sun Belt entries show promising early velocity amid strong 2024 population inflows, but require cash to scale; pilots (BTR, net‑zero, digital, entry series) must clear CAC, cycle and margin hurdles or risk becoming Dogs.
| Metric | 2024 |
|---|---|
| Digital starts | 68% |
| Click-to-close | ~12% |
| Mortgage rate | ~7% |
| Clean Energy credit | ~30% |


