
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
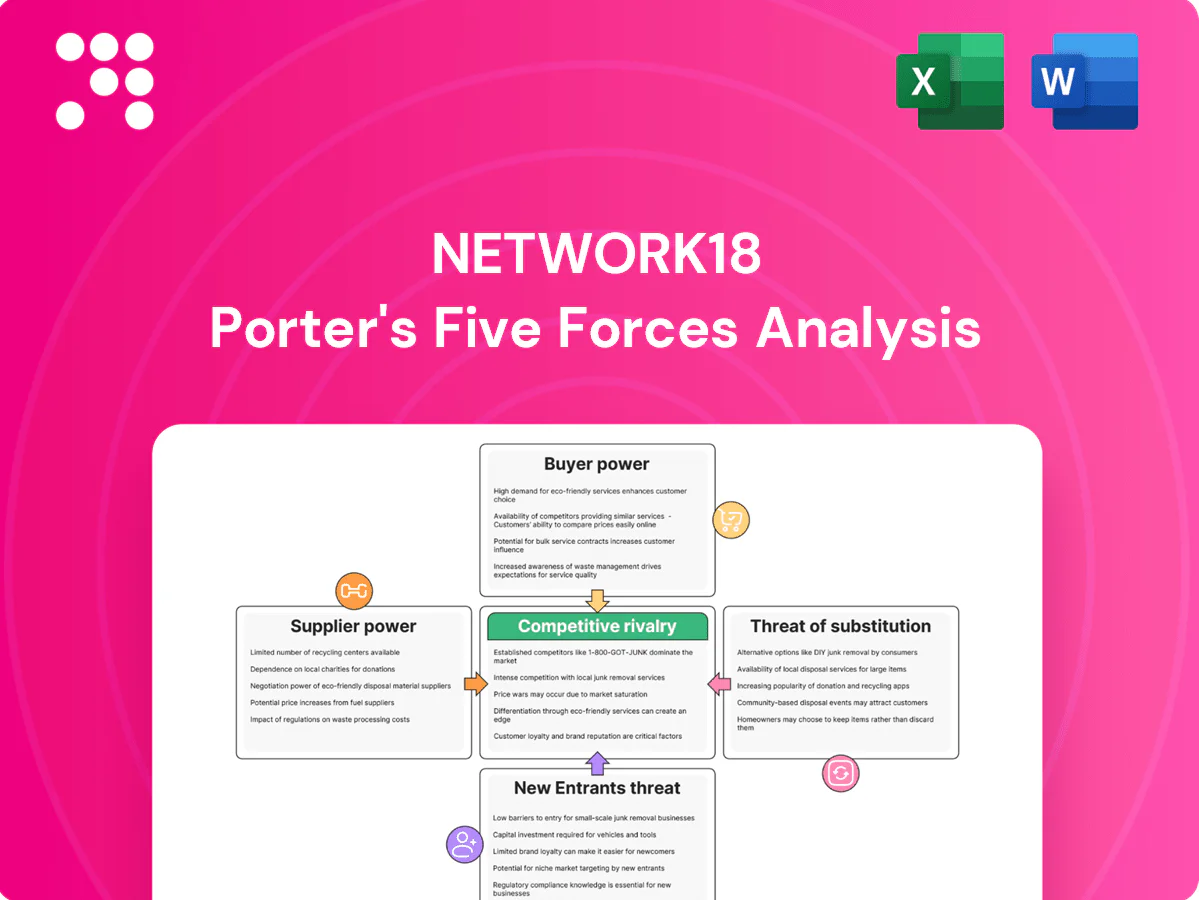
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Network18 faces substantial competitive intensity from digital rivals and shifting advertiser power, while content costs and platform dependency heighten supplier influence; substitutes from streaming and social channels increase disruption risk. This snapshot highlights key pressures and strategic levers. Unlock the full Porter's Five Forces Analysis to access force-by-force ratings, visuals, and actionable recommendations.
Disney Star, Sony, Zee, Sun TV and India Today fiercely compete across genres and languages, with BARC 2024 data showing regional-language channels account for over 60% of TV viewership, intensifying overlap. Ratings battles drive cyclic programming spends and ad-rate volatility, pressuring margins. Regional expansion and local content depth have become decisive brand differentiators as national reach alone no longer ensures dominance.
Global platforms like YouTube (≈2.5B monthly users) and TikTok (≈1.6B) plus Netflix (≈260M subs) siphon attention and ad rupees from Network18 in India (≈760M internet users in 2024), forcing competition on UX, originals and sports that inflate content costs; combined IPL TV+digital rights for 2023–27 totaled INR 48,390 crore. Cross-platform windowing and data-driven commissioning are essential competitive levers.
Strong regional broadcasters command loyal audiences and local advertising, with BARC India 2024 reporting regional language viewership at about 63% of total TV consumption.
Fragmentation raises bidding complexity for national buys, forcing advertisers to manage multiple regional rate cards and higher planning costs.
Hyperlocal content often outcompetes national feeds on engagement, so Network18 counters by offering tailored regional slates to protect share.
Economic slowdowns push broadcasters into discounting and offering bonus inventory, creating excess spots that depress effective yields; dynamic pricing and active sell-through management are therefore critical to protect margins. Premium events and marquee sports/special programming remain key levers to preserve rate integrity and limit spillover into lower-yield inventory.
Disney Star, Sony, Zee, Sun TV and India Today compete fiercely; BARC 2024 shows regional languages ≈63% of TV viewership, intensifying overlap and ad-rate pressure.
Global platforms (YouTube ≈2.5B users, TikTok ≈1.6B, Netflix ≈260M subs) plus India's ≈760M internet users (2024) siphon ad revenues; IPL 2023–27 rights = INR 48,390 crore.
Economic slowdowns spark discounting; Reliance consolidated revenue INR 10.78 lakh crore FY2024 provides Network18 defensive scale.
| Metric | Value |
|---|---|
| Regional TV share (BARC 2024) | ≈63% |
| India internet users (2024) | ≈760M |
| YouTube users | ≈2.5B |
| Netflix subs | ≈260M |
| IPL rights (2023–27) | INR 48,390 Cr |
| Reliance revenue FY2024 | INR 10.78 Lakh Cr |
User-generated short-form platforms like TikTok (≈1.6 billion MAUs in 2024) capture attention at near-zero cost to users, pulling ad dollars and engagement. Brands redirected budgets to creators as influencer marketing reached $21.1 billion in 2023, driven by measurable ROI. Strong editorial authority—e.g., The New York Times 9.8 million subscribers in 2024—can counter pure entertainment, and hybrid creator-news formats are reclaiming share.
Interactive gaming now competes directly for prime-time hours and ad budgets as the global games market surpassed $200 billion by 2024, drawing audiences away from passive TV. High engagement in games and live streams reduces passive viewing, with esports and competitive titles reaching over 500 million viewers in 2024 and enabling sponsorship tie-ins that bridge audiences. Network18 can use second-screen and in-game ad strategies to mitigate time displacement and recapture ad spend.
Podcasts and audio streaming pose a strong substitute as they fit commute and multitask consumption, with India’s internet audio audience reaching about 430 million in 2024, expanding habitual listening. Lower production costs yield abundant choice and niche shows. Cross-publishing audio with video increases reach across platforms. Native audio ads provide incremental monetization for publishers.
Brands build owned media and commerce, bypassing traditional publishers; influencer channels captured an estimated $21 billion global spend in 2024, redirecting bottom-funnel dollars to performance marketing. Co-created content preserves relevance and engagement. Brand-lift studies report average lifts of about 10–15%, defending premium placements.
Social news via WhatsApp (over 2 billion users) and X (about 550 million MAU in 2024) plus news aggregators have reduced direct visits as 36% of adults often get news from social platforms (Pew Research). Headlines commoditize unless paired with depth; push alerts and explainers help publishers regain engagement. Trust and verification matter: 64% of users are concerned about misinformation, creating a premium for verified sources.
User-generated short-form (TikTok ≈1.6B MAUs 2024) and influencer spend ($21.1B 2023) divert ad dollars; gaming (> $200B market 2024) and esports (500M+ viewers 2024) eat viewing time. Audio (India ≈430M listeners 2024) and brand-owned channels capture intent and performance budgets. Social news (WhatsApp >2B, X ≈550M; 36% get news via social) commoditizes headlines; trust premiums (64% worry about misinformation) favor verified publishers.
| Metric | 2023/24 | Implication |
|---|---|---|
| TikTok MAU | ≈1.6B (2024) | Attention diversion |
| Influencer spend | $21.1B (2023) | Ad budget shift |
| Games market | >$200B (2024) | Time displacement |
| India audio | ≈430M (2024) | Habitual reach |
Low setup costs and cloud tools let digital-native publishers enter niches rapidly, with cloud services supporting lean startups and pay-as-you-go models; programmatic and subscriptions enable quick scaling, with programmatic accounting for about 80% of display ad spend in recent years. SEO and social mastery can build audiences fast given Google’s ~92% global search share in 2024. Incumbents’ brand equity and distribution remain a meaningful moat for Network18.
Creators are converting communities into media brands, supported by a creator base of over 50 million globally and influencer marketing spend reaching about $21 billion in 2023, enabling direct sponsorships that bypass traditional intermediaries. Network18 can partner with or invest in creator-led studios to turn threats into supply, and equity deals align incentives for sustained content output and IP development.
Ad-supported FAST channels lower carriage barriers and by 2024 had expanded to over 2,000 global channels, intensifying entrant pressure. Content acquisition remains the primary cost hurdle, with licensed library spends accounting for the majority of upfront capex. Smart TV penetration (roughly half of global TV shipments in 2024) creates instant reach. Library depth and curation determine long-term stickiness and ARPU retention.
Regulatory and compliance barriers—driven by licensing requirements, newsroom norms and prescribed content codes—raise the operational effort for entrants into Network18’s segment, reinforced by India’s IT Rules 2021 and related broadcast regulations that mandate fast takedown and grievance timelines (commonly cited 36 hours for actionable orders).
Enforcement variability across states still deters national scale; established players like Network18 benefit from mature legal teams and processes that reduce exposure to fines and takedowns, while newcomers face disproportionate risk and compliance costs.
Securing sports, originals and top-tier talent requires deep pockets—IPL 2023–27 media rights fetched INR 48,390 crore (~$6.2bn), illustrating scale incumbents can command. Multi-year deals and long-standing distributor relationships lock supply. New entrants often overpay to gain relevance; disciplined ROI filters (CPV, ARPU thresholds) protect incumbents from irrational bids.
Low setup costs, cloud tools and programmatic (≈80% display ad spend) make niche entry easy; Google held ≈92% search share in 2024 aiding rapid audience build. Creators (≈50M) and $21B influencer spend (2023) create direct competition. FAST growth (2,000+ channels) and 50% Smart TV penetration lower carriage barriers. High rights costs (IPL INR 48,390 crore ≈$6.2bn) and regulatory IT Rules 2021 raise scale barriers.
| Metric | Value |
|---|---|
| Programmatic share | ~80% |
| Google search share (2024) | ~92% |
| Creator base | ~50M |
| Influencer spend (2023) | $21B |
| FAST channels (2024) | 2,000+ |
| Smart TV penetration (2024) | ~50% |
| IPL rights (2023–27) | INR 48,390 crore (~$6.2bn) |


