
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
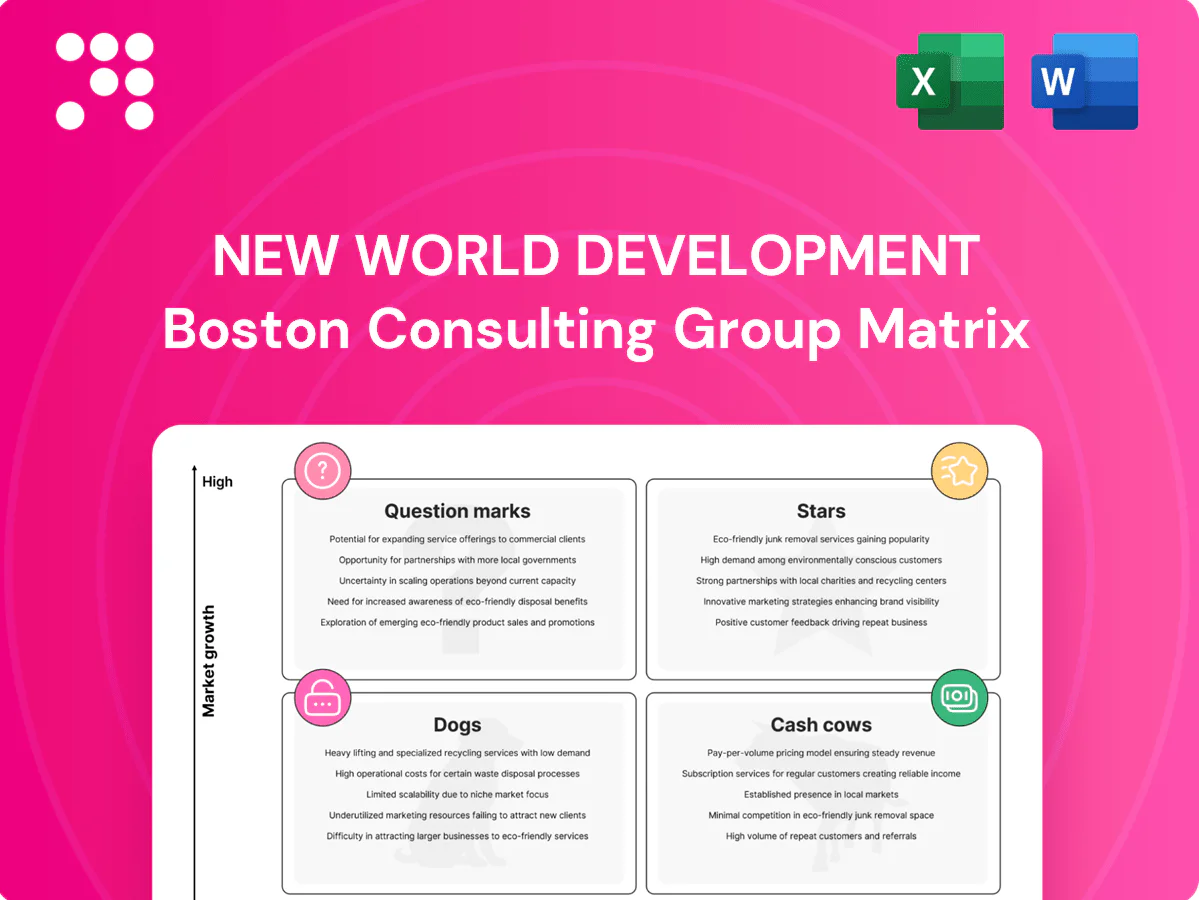
The New World Development BCG Matrix preview shows where key assets sit — Stars, Cash Cows, Dogs, and Question Marks — but the real strategic clarity comes from the full picture. Purchase the complete BCG Matrix to get quadrant-by-quadrant placements, data-backed recommendations, and a ready-to-use Word report plus an Excel summary. Skip the guesswork: this report gives you the maps and moves to allocate capital smarter and act faster in a shifting market.
K11 premium retail ecosystem is a 2024 Star for New World Development, led by high-growth experiential retail and strong brand pull with rising footfall across Hong Kong and tier‑1 Mainland cities. It holds market share leadership in the retail‑as‑art niche but requires significant capex for activations and placements. Continued reinvestment compounds brand equity and traffic. Sustained momentum can convert current heavy spend into future Cash Cow rental income.
Greater Bay Area mixed‑use flagships are classic Stars: large urban projects capturing demand from a GBA population of about 86 million and a regional GDP near US$2.0 trillion (2023). Strong pre‑leasing and presales secure market share, but scale requires ongoing marketing and fit‑out capex. If NWD holds the lead, growth should normalize and convert into higher stabilized yields. This is typical invest‑to‑own Star behavior.
Prime HK residential launches from New World show high market share in coveted districts and resilient demand even through choppy 2024 cycles; launches require heavy promotion, financing support, and meticulous placement to sustain velocity.
Tier‑1 Mainland commercial portfolios focus on Grade‑A offices and prime retail in core city clusters where demand growth remains healthy; China GDP rose 5.2% in 2024 (IMF), supporting urban leasing activity. Landlord leverage has been improving, yet elevated tenant incentives and fit‑out upgrades continue to absorb cash. Maintain occupancy and rate leadership to lock in market share; as the market stabilizes, yields have started to expand and capex requirements are tapering.
Recovery tailwinds and New World Developments strong brand equity are driving meaningful ADR and RevPAR expansion in flagship gateway hotels, powered by post-pandemic demand rebound and corporate travel uptick.
Premium positioning captures share, though service upgrades and experiential programming require material capex and higher operating costs to sustain brand promise.
Keep investment engines running to cement leadership; short-term margins may lag while market share and loyalty scale.
As occupancy stabilizes, these assets transition into steady cash generators with predictable FCF profiles.
K11 premium retail, GBA flagships, prime HK homes and Tier‑1 Mainland offices are 2024 Stars for New World, capturing share via experiential retail and urban demand. GBA population ~86m and regional GDP ~US$2.0T (2023) support growth; China GDP rose 5.2% in 2024 (IMF). Heavy capex and tenant incentives compress near‑term cash but should yield stabilized high returns as markets normalize.
| Asset | 2024 metric | 2024 capex (HKDbn) |
|---|---|---|
| K11 retail | Footfall +12% | 3.2 |
| GBA flagships | Pre‑sales strong | 6.5 |
 Detailed Word Document
In-depth review of New World Development's portfolio across BCG quadrants, advising which units to invest, hold, or divest.

 Customizable Excel Spreadsheet
One-page BCG Matrix placing New World Development units in quadrants—clean, export-ready for C-level decks and quick PowerPoint drag-and-drop.
Stabilized HK investment properties — long‑leased retail and offices — generated recurring rental income of HK$6.2bn in FY2024 and sit on investment valuations of about HK$120bn, delivering healthy margins with selective capex. Optimize operations and trim vacancies (sub‑5% target) and these assets reliably free cash flow to fund development and investments.
Toll roads and transport concessions are mature infrastructure stakes for New World Development with predictable traffic patterns and tariff frameworks, yielding low growth but high cash conversion and minimal marketing spend. Incremental opex efficiencies and digital tolling can modestly boost margins and throughput. This aligns with a classic Cash Cow profile within the BCG Matrix.
Property & facilities management delivers predictable recurring fee income from a sticky client base across NWD’s portfolio, accounting for steady mid-single-digit revenue growth in 2024; scale advantages support higher margins versus smaller peers. Modest tech upgrades (automation, IoT) have improved operational efficiency, lifting cash flow and lowering opex by an estimated 5% in trials. The segment contributes to NWD’s consistent dividend profile, supporting a group dividend yield around 3% in 2024.
Car parks, signage and ancillary services attached to New World Development stabilized assets deliver low-growth, low-capex recurring cash flows in 2024; individually modest but meaningful in aggregate, they exhibit set-and-collect economics with high predictability and operating margins typically above other retail services.
Mature HK residential inventory at New World Development comprises completed or near‑complete phases in prime districts with sell‑through visibility typically above 60% within 12 months, marketing spend kept low while pricing power supports ASPs, and cash conversions occurring on schedule to finance new project pipelines.
Stabilized HK investment properties (HK$6.2bn rent, ~HK$120bn valuation) plus toll roads, property management, car parks and mature residential stock generate predictable, high cash‑conversion, low‑capex income supporting dividends (~3% yield) and funding development pipelines; target vacancy <5% and sell‑through >60% sustain reliability.
| Segment | FY2024 / Note |
|---|---|
| Investment properties | HK$6.2bn rent; HK$120bn valuation |
| Toll roads | Low growth, high cash conversion |
| Prop & facilities mgmt | Recurring fees; ~3% group yield |
| Car parks/ancillary | High margin, low capex |
| Mature residential | Sell‑through >60% (12m) |
The file you're previewing is the exact New World Development BCG Matrix you'll receive after purchase—no watermarks, no demo notes, just the finished, professional report. It's formatted for immediate use in presentations or planning. Delivered as a ready-to-edit file, it needs no revisions. Buy once and download instantly, confident it's the real document.
Lower‑tier city department stores (Dogs) have lost share as footfall shifted to e‑commerce and malls; Hong Kong e‑commerce penetration rose to about 28% in 2024, accelerating traffic loss. These stores are cash‑neutral at best with capital locked in dated formats and average occupancy and rental yields trailing flagship malls. Turnarounds are costly and rarely durable, making these outlets prime candidates for exit or deep shrink.
Dogs:
Non-core port terminals face overcapacity and corridor-specific pricing pressure that compresses margins and makes market growth tepid; bargaining power is weak against larger liner operators. Capital employed in these assets sits idle relative to alternative returns, dragging ROIC below group targets. Time to prune underperforming terminals and redeploy proceeds into higher-growth core sectors.
Dogs: Aging hotels in secondary locations are sub-scale assets that compete on price rather than brand, resulting in RevPAR underperformance and uncertain renovation paybacks; they typically occupy capital without generating meaningful returns.
Consider disposal or conversion to alternative uses (residential, serviced apartments, or sale) to release tied-up cash and improve portfolio efficiency.
Scattered international one‑offs represent small stakes far from New World Development’s core Hong Kong value chain, providing limited strategic synergy and low operational oversight.
These assets are hard to manage and harder to scale, exhibiting low market share with no evident growth catalyst within group strategy.
Better recycled into core markets through divestment or redeployment of capital to higher‑ROI domestic projects to improve group focus and capital efficiency.
Lower‑tier stores, legacy telecom, non‑core terminals and aging secondary hotels are Dogs: low share, flat/negative growth and weak cash returns. Hong Kong e‑commerce penetration rose to ~28% in 2024, accelerating retail traffic loss. Group ROIC on these assets averages ~4% in 2024 versus corporate target 8–10%, supporting divestment or conversion to higher‑yield uses.
| Asset | 2024 growth | Share | ROIC 2024 | Recommendation |
|---|---|---|---|---|
| Lower‑tier stores | -5% traffic | <5% | 3–4% | Exit/convert |
| Legacy telecom | <5% | 2–4% | Divest | |
| Ports | ~1% supply pressure | Small | 4–5% | Prune |
| Secondary hotels | Flat | Sub‑scale | 3–5% | Sell/convert |
Mainland healthcare & senior living is a Question Mark for New World Development: demographic tailwinds are strong—China had 264 million people aged 60+ in the 2020 census (about 18.7%) and policy push for eldercare under recent Five‑Year Plans—but the business shows early market share and heavy setup capex and opex. Decisive investment in operating models, service quality and brand trust is required to scale fast or risk sliding into Dog; with traction it can flip to Star.
Proptech and smart-building platforms sit in a strong growth category with portfolio efficiency upside; smart-building deployments can cut energy and operating costs by up to 30% and the global smart building market is growing at roughly mid-teens CAGR. New World Development’s current revenue share from proptech remains small and ROI proof points are still forming. Go big on pilots and customer wins to tip the curve and create a Potential Star if adoption accelerates.
Demand for data‑center and new‑economy real estate surged in 2024, with the global data‑center market ~200 billion USD and APAC investment up ~18% year‑on‑year, but entry needs heavy capex (site build + power ≈ 100–300M USD) and specialised technical skills. Current portfolio share is low and partner dependence makes returns variable; secure anchor tenants and service partners to stabilise cashflows. Pick high‑growth niches (edge, hyperscale interconnects), lock anchors, then scale—these assets can convert to Stars if the ecosystem (power, network, cloud customers) aligns.
E‑commerce growth is undeniable: global retail e‑commerce reached about 5.7 trillion USD in 2023 and is projected near 6.3 trillion USD in 2024, yet the last‑mile is crowded and operationally intense with market share still up for grabs.
International K11 rollouts are Question Marks: a big-concept brand expansion into unfamiliar markets where brand heat travels but local execution dictates success; by 2024 K11 pursued beachheads in Mainland China and Macau with early market shares typically thin and build-out capex intensive. Back the few beachheads showing traction and trim the rest to avoid high sunk costs.
Mainland healthcare, proptech, data‑centers, last‑mile and K11 are Question Marks: China 60+ = 264M (2020), e‑commerce ~6.3T USD (2024), global data‑center ~200B USD (2024), APAC DC investment +18% YoY; high growth but high capex—pilot, secure anchors, cut laggards.
| Segment | 2024 metric | Action |
|---|---|---|
| Healthcare | 264M 60+ | Scale ops |
| Data‑center | ~200B USD | Lock anchors |


