
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
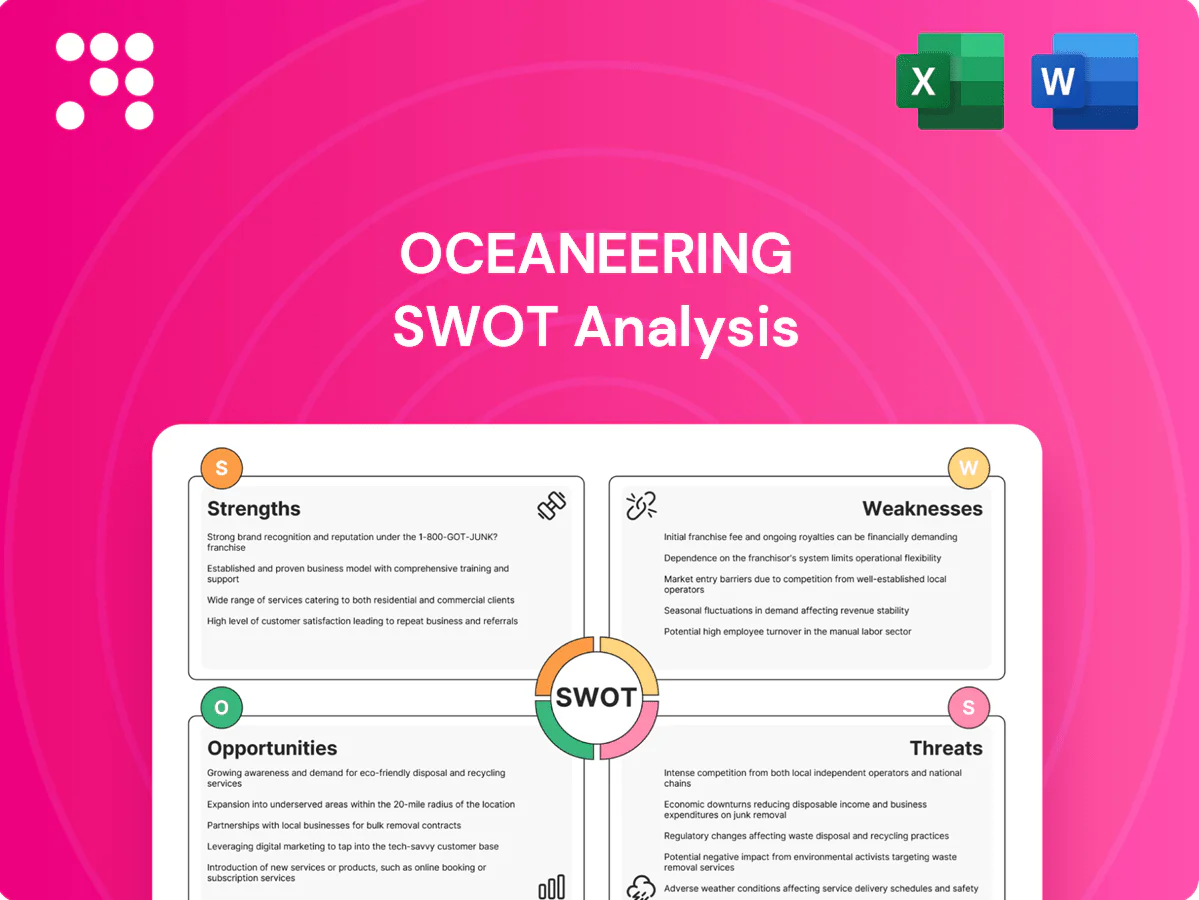
Explore our Oceaneering SWOT Analysis for a concise view of strengths, vulnerabilities, market opportunities, and competitive threats. This snapshot highlights technical expertise, offshore exposure, and regulatory risks to inform quick decisions. Want the full, research-backed report with editable Word and Excel deliverables? Purchase the complete SWOT to plan, pitch, and invest with confidence.
Oceaneering's deepwater robotics leadership rests on a modern fleet of over 200 ROVs and more than 60 years of offshore experience, supporting complex deepwater operations. High utilization and mission-critical uptime create material switching costs for operators. Decades of know-how enable faster intervention cycles and reliable availability, letting brand credibility support premium pricing in the toughest environments.
Oceaneering’s exposure beyond oil and gas into defense, aerospace and entertainment smooths revenue swings by linking to less cyclical end markets. Cross-industry robotics and automation work—deployed across ROVs, space actuators and live-event systems—bolster revenue resilience. Large, long-cycle government programs benefit from a US defense budget of about 858 billion in FY2024, widening funded opportunities and customer pipelines.
Oceaneering's proprietary subsea hardware, umbilicals and tooling form a differentiated product suite supported by systems-integration expertise that has reduced project incidents and improved HSE metrics; the company reported roughly $1.6B revenue in 2023 while ROV and tooling contracts underpin a multi-hundred-million-dollar backlog, and ongoing investment in autonomy and remote operations preserves technical barriers and margin resilience.
Oceaneering leverages a global footprint of bases, vessels and logistics to mobilize quickly in key basins, improving bid competitiveness and execution reliability. Local presence aids regulatory compliance and access to skilled talent, while high asset density delivers operating leverage during upcycles.
Inspection, maintenance, and asset integrity provide Oceaneering predictable, repeatable revenue streams and reduce reliance on one-off projects.
Data-rich services and digital monitoring increase customer stickiness across asset lifecycles and enable cross-sell of hardware and services.
Long-term integrity frameworks smooth cash flows and enhance margin visibility versus lump-sum contracts.
Oceaneering leads deepwater robotics with 200+ ROVs and 60+ years of offshore expertise, supporting premium pricing and high uptime. Diversified end markets (defense, aerospace, entertainment) and a ~multi-hundred‑million backlog underpin revenue resilience; 2023 revenue ~1.6B. Global bases and data-driven services create recurring, cross‑sellable cash flows.
| Metric | Value |
|---|---|
| ROV fleet | 200+ |
| Years offshore | 60+ |
| 2023 revenue | $1.6B |
| FY2024 US defense | $858B |
 Detailed Word Document
Delivers a strategic overview of Oceaneering’s internal and external business factors, outlining strengths, weaknesses, opportunities and threats to assess competitive position and guide strategic decisions.

 Customizable Excel Spreadsheet
Provides a concise, visual SWOT matrix tailored to Oceaneering for fast strategy alignment and stakeholder updates, enabling quick identification of tactical priorities.
Oceaneering’s revenue remains closely tied to offshore capex, leaving earnings sensitive to oil-price swings; Brent averaged about $86/bbl in 2024, and price dips have historically led to rapid project deferrals. Project postponements quickly hit utilization and margins, with day-rate-dependent segments showing pronounced volatility. Planning complexity rises as customer budgets fluctuate, and diversification into non-oil markets helps but does not remove exposure.
Oceaneering (NYSE: OII) is capital intensive—ROV fleets, support vessels and manufacturing assets require ongoing capex and maintenance, often totaling hundreds of millions annually. Working capital can expand sharply during growth phases and large project ramps. Return on invested capital often lags in industry downcycles. Balance-sheet flexibility therefore must be actively managed to weather volatility.
Long‑lead subsea hardware and umbilicals expose Oceaneering to schedule and cost overrun risk, particularly given a backlog exceeding $1 billion and component lead times often surpassing 12 months. Supply‑chain volatility has compressed margins on fixed‑price projects, contributing to margin variability in recent quarters. Cross‑border integration adds coordination complexity across engineering, fabrication and logistics. Warranty claims and rework have periodically pressured profitability and cash flow.
Dependence on a handful of major oil and gas operators concentrates bargaining power, leaving Oceaneering exposed when those operators prioritize cost reductions.
Pricing pressure tends to intensify during operator cost-down cycles, compressing service margins and freighting returns toward contractors.
Contract renewals carry utilization risk if key operator contracts are lost, and negotiation leverage can vary significantly by basin and asset class.
Association with fossil projects limits access to sustainability-focused capital as global sustainable assets reached 41.1 trillion USD in 2023 (GSIA), narrowing investor pools; rising disclosure and compliance (eg EU CSRD phasing 2024–25) increase reporting costs; recruiting sustainability-first talent is tougher; management must clearly articulate credible transition alignment and timelines.
Revenue tied to offshore capex; Brent averaged about $86/bbl in 2024, making earnings oil‑price sensitive. Capital intensity (capex/maintenance in the hundreds of millions) and >$1bn backlog with component lead times >12 months raise schedule and cash risks. Concentrated major-operator mix and fossil association constrain pricing, renewals and ESG capital access.
| Metric | Value |
|---|---|
| Brent (2024) | $86/bbl |
| Backlog | > $1bn |
| Lead times | > 12 months |
| Sustainable assets (2023, GSIA) | $41.1 trillion |
This is the actual SWOT analysis document for Oceaneering you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report and reflects the complete structure and findings. Purchase unlocks the editable, detailed version.
Improving offshore project economics and a rebound in multi-year FIDs are driving renewed demand for deepwater services, favoring Oceaneering’s ROV and IMR capabilities as longer tiebacks and brownfield campaigns increase scope intensity. Higher fleet utilization can expand margins through operating leverage while backlog growth from awarded deepwater contracts enhances near‑term revenue visibility. Recent industry sanctioning momentum through 2024–2025 underpins sustained tendering activity.
Offshore wind, carbon capture and subsea power distribution share cable-lay, trenching and inspection needs that mirror Oceaneering core competencies; global offshore wind reached about 64 GW installed by end-2023 (GWEC). Carbon capture has 27 commercial facilities capturing roughly 50 MtCO2/year (Global CCS Institute, 2023). Decommissioning demand for robotics and integrity services and low-carbon project diversification broaden growth paths and revenue mix.
Resident ROVs, AUVs and remote operations enable Oceaneering (ticker OII) to lower offshore headcount and operating cost through persistent asset presence and remote monitoring.
Data analytics and AI for predictive maintenance cut unplanned downtime and enhance value-add across subsea fleets.
Remote command centers boost fleet productivity and, combined with software and services, shift revenue mix toward higher-margin, scalable offerings.
Undersea defense robotics and specialized manufacturing can expand as US defense spending reached $858 billion in FY2024, supporting procurement and R&D. Long-duration government contracts provide multi-year revenue stability and backlog visibility. Energy-derived technology transfer strengthens competitive bids for complex subsea and space systems. Export demand taps a global space economy estimated at about $469 billion (2022).
Strategic partnerships with EPCs, operators, and OEMs position Oceaneering to secure integrated awards by bundling engineering, procurement and field services into single-source contracts, reducing procurement friction and bid cycles.
Co-development agreements accelerate technology adoption and market access, enabling faster commercialization of robotics and subsea systems while sharing R&D risk and IP upside.
Outcome-based contracts and alliance structures can capture shared savings and de-risk entry into new geographies and verticals through local partners, lowering capex and market entry costs.
Renewed deepwater FIDs and higher fleet utilization boost ROV/IMR demand and margins; backlog growth improves near-term visibility.
Offshore wind (64 GW end-2023) CCS (27 facilities) and decommissioning expand addressable markets for cable-lay, trenching and robotics.
Defense spend (US $858B FY2024) and space exports (~$469B 2022) enable long-duration contracts and tech-transfer opportunities.
| Opportunity | Metric | Impact |
|---|---|---|
| Deepwater | Backlog↑ | Revenue visibility |
| Renewables/CCS | 64 GW / 27 sites | Service growth |
| Defense/Space | $858B / $469B | Stable contracts |
Sustained low oil and gas prices can halt offshore investments; after the 2014–16 price collapse offshore E&P capex fell about 30%, illustrating vulnerability to prolonged weakness. Rapid price swings disrupt project planning and utilization, forcing idle fleet and compressing utilization. Budget cuts cascade into pricing and day rates, while currency movements—notably a stronger US dollar—add cross-border revenue uncertainty.
Oceaneering (NYSE: OII) faces intense pricing pressure from large global subsea contractors and nimble niche specialists competing for the same ROV, IMR and engineering contracts. Rapid technology catch-up by rivals — including modular tooling and digital monitoring — narrows product differentiation and compresses margins. Industry consolidation increases rivals’ scale and bid capacity, enabling more aggressive low-cost bids. Persistent talent poaching of offshore, R&D and project staff erodes execution quality and project delivery consistency.
Material cost spikes and component shortages have compressed project margins for Oceaneering, with steel and electronic component costs notably elevated while U.S. CPI ran 3.4% in 2024. Logistics delays raise the risk of liquidated damages on tight subsea installation timelines as port congestion and vessel delays persist. A limited supplier base for specialty ROV and subsea parts heightens vulnerability to single-source disruptions. Fixed-price contract structures may not fully pass through inflation, squeezing profitability.
Regulatory and geopolitical risks raise execution costs for Oceaneering as sanctions, export controls, and local content rules complicate cross-border project delivery and supplier chains; environmental permitting delays can stall or cancel offshore projects, increasing idle vessel and asset costs. Geopolitical tensions disrupt trade routes and raise insurance premiums, while compliance failures risk fines and reputational damage.
Offshore operations carry significant safety and environmental risk; a major incident can halt projects and trigger large penalties—Deepwater Horizon led to roughly 65 billion dollars in payouts and costs for BP. Major incidents also drive insurance and reinsurance market hardening observed in 2022–24, increasing coverage costs and retention. Reputation damage from incidents materially reduces award win rates and partner trust.
Prolonged low oil prices threaten offshore capex (offshore E&P capex fell ~30% after 2014–16). Intense price competition and consolidation compress ROV/IMR margins and utilization. Material cost inflation (U.S. CPI 3.4% in 2024), supply shortages and insurance/regulatory shocks (Deepwater Horizon ~$65bn) raise execution and compliance costs.
| Threat | Key metric |
|---|---|
| Capex exposure | Offshore E&P capex -30% (2014–16) |
| Inflation & supply | U.S. CPI 3.4% (2024) |
| Catastrophic risk | Deepwater Horizon ~$65bn |


