
Digital download
Access the files immediately after checkout.
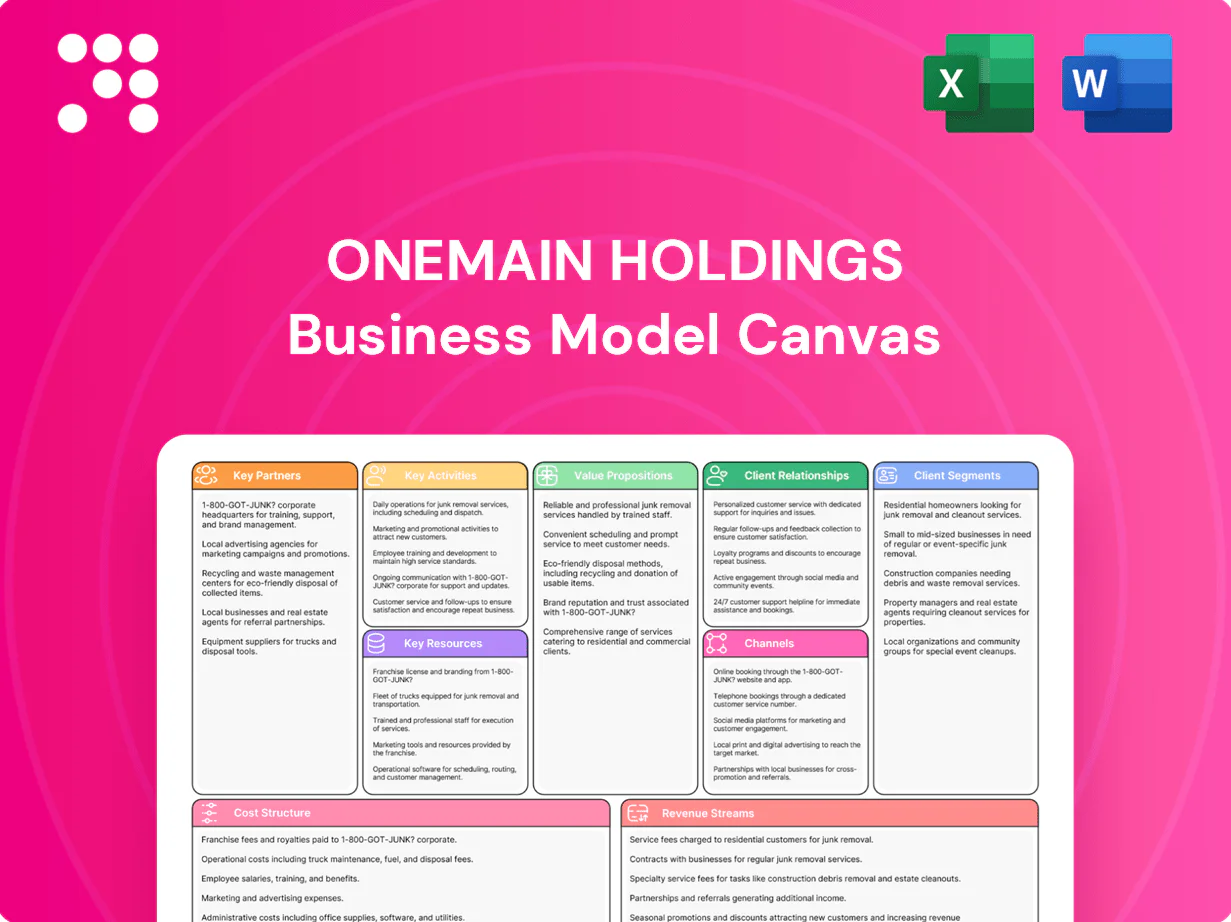
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
Explore OneMain Holdings’s Business Model Canvas to see how its customer-focused lending, branch network, and risk-adjusted pricing drive steady revenue and growth. This concise analysis uncovers key partnerships, cost drivers, and revenue streams. Purchase the full Canvas for a downloadable, editable breakdown—ideal for investors, advisors, and strategists seeking actionable insights.
Local branches enable face-to-face service for nonprime customers, supported by about 1,500 branches nationwide in 2024. In-person verification and counseling improve credit outcomes and support secured lending processes such as vehicle title loans and collateral inspections. Community presence builds trust and drives referrals, reinforcing repeat business and local market penetration.
OneMain Holdings (OMF) digital lending platform delivers online application, decisioning, and servicing to streamline personal loan access, with platform upgrades rolled out in 2024 to reduce decision times and increase digital completions. APIs integrate third-party data, verification, and payments for faster KYC and funding. Scalable cloud infrastructure supports peak demand and rapid elasticity. Security controls and high availability underpin operational reliability.
Proprietary scorecards and ML models tailor credit decisions to nonprime risk profiles, deployed across OneMain's 2024 underwriting stack to balance approvals and loss rates. Continuous learning pipelines update risk parameters from live performance data, improving approval–loss trade-offs over time. Regular champion–challenger testing refines strategy, while governance frameworks enforce fairness, documentation, and model explainability.
OneMain funds originations through securitization shelves, warehouse facilities and equity capital, with 2024 securitization capacity reported at about $3.5 billion supporting borrower loans and reducing funding cost pressure.
Diversified liquidity in 2024 lowered single-channel dependency, while active hedging and terming-out of funding mitigated rate risk; investor trust remains a strategic asset driving favorable pricing and access.
Credit, operations, and compliance teams execute the full loan lifecycle, supporting underwriting, servicing, and regulatory controls; in 2024 OneMain operated roughly 1,500 branches with about 6,000 employees.
OneMain's key resources: ~1,500 branches and ~6,000 employees in 2024 providing in-person origination and servicing. Digital lending platform and cloud infrastructure reduced decision times after 2024 upgrades. Proprietary scorecards/ML and governance support tailored underwriting. Funding via securitization (~$3.5B 2024), warehouses and equity underpin liquidity.
| Resource | 2024 |
|---|---|
| Branches | ~1,500 |
| Employees | ~6,000 |
| Securitization | ~$3.5B |
Personal loans for nonprime consumers address an underserved market segment where 17.9% of U.S. households were classified as underbanked by the FDIC, creating demand for transparent credit. Predictable payments and clear terms reduce default risk and build borrower confidence. Credit-building features can improve long-term financial health, while underwriting blends inclusion with prudence to manage portfolio performance.
OMF (NYSE: OMF) delivers fast, convenient funding with streamlined digital and branch processes that enable same-day or next-day funding for many applicants; e-sign and instant verification minimize friction, cutting turnaround to hours in approved cases. Customers save time and effort, supporting OneMain's 2024 focus on rapid access to credit across its national network.
Personalized solutions deliver tailored loan amounts, terms, and secured options to fit varied situations, supported by OneMain’s 1,300+ branch network for in-person consultations. Offerings include debt consolidation, auto-secured loans, and credit-card alternatives to increase borrower flexibility. Branch consultations provide human guidance and hardship-adjustment options to stabilize repayment. These choices aim to reduce default risk and improve customer retention.
Transparent pricing with clear disclosures and fixed-rate installments reduces payment surprises; OneMain served about 1.3 million customers and held roughly $22 billion in loans outstanding in 2024, supporting predictable cash flows and lower default risk.
No-hassle servicing, multiple payment options and proactive outreach improve experience and on-time payments, strengthening trust that drives loyalty and referrals.
Complementary credit card products extend ongoing credit access tied to OneMain installment loans, creating repeat engagement and fee/interest revenue streams.
Optional protection products such as payment protection and insurance add resilience for consumers and reduce credit losses for OneMain.
Rewards and digital tools encourage responsible use and increase retention through behaviorally designed incentives and app-based account management.
Cross-product analytics generate insights that improve pricing, credit decisions, and personalized offers.
OneMain delivers accessible personal loans for nonprime consumers (served ~1.3M customers in 2024) with transparent fixed-rate terms, rapid funding, and branch/digital options across 1,300+ branches; this reduces friction and supports portfolio stability. Cross-product credit cards, protection products, and analytics drive retention, fee income, and risk mitigation on ~$22B loans outstanding (2024).
| Metric | 2024 |
|---|---|
| Customers | ~1.3M |
| Loans outstanding | $22B |
| Branches | 1,300+ |
| Key benefits | access, predictability, retention |
In-person branch advisory helps customers select suitable products tailored to credit profiles. Staff walk clients through terms, budgets and repayment plans to reduce defaults and improve affordability. Trust built face-to-face boosts retention and recovery outcomes. OneMain maintained over 1,000 branches in the US and served millions of customers as of 2024.
Apps and portals let OneMain customers complete credit applications, make payments, and update accounts online, supporting over 2 million customers. 24/7 access reduces dependence on calls and branches, lowering service costs and wait times. Proactive push and SMS notifications keep borrowers informed on balances and due dates. Continuous UX improvements have driven higher satisfaction and digital engagement.
Onboarding, automated payment reminders and timed renewal offers are sequenced across channels to lift activation and reduce missed payments; OneMain serves roughly 1.5 million customers and manages about $16 billion in loan receivables (2023). Behavioral messaging tailors touchpoints to credit behaviors, boosting repayment success. Loyalty programs and credit-education modules increase retention and product take-up. Proactive alerts and hardship interventions cut churn risk.
Hardship assistance provides temporary relief and restructures to manage borrower shocks, with flexible plans designed to reduce charge-offs and stabilize receivables. Empathetic treatment preserves customer relationships and repeat business while compliance frameworks ensure fair, documented and consistent options across accounts.
Phone, chat, and email channels resolve customer issues rapidly, routed to trained agents who handle disputes and servicing needs; knowledge bases and internal FAQs cut average handle time while quality monitoring and scorecards drive continuous improvement.
In-person branches (over 1,000 in 2024) and trained advisors drive retention and recovery through tailored product guidance and hardship options. Digital channels serve 2,000,000+ users for applications, payments and notifications, lowering costs and wait times. Sequenced onboarding, behavioral messaging and omnichannel service support ~1.5M customers and $16B loan receivables (2023).
| Metric | Value | Year |
|---|---|---|
| Branches | >1,000 | 2024 |
| Digital users | >2,000,000 | 2024 |
| Active customers | ~1,500,000 | 2023 |
| Loan receivables | $16,000,000,000 | 2023 |
OneMain operates about 1,500 branches nationwide as of 2024, with walk‑in and appointment traffic forming a core origination channel. Local marketing and community partnerships increase branch visibility and customer acquisition. Branch staff perform verification and enable secured lending processes on site. Post‑funding, branches act as service hubs for payments, modifications and in‑person support.
Website and mobile app capture broad demand efficiently, with digital intake handling 45% of new applications in 2024 and reducing time-to-apply by 60%. Prequalification and instant decisions raised online conversion by 20% year-over-year. Self-service tools cut servicing costs by an estimated 15%, while secure payments and electronic statements improved retention, lowering churn by 8% in 2024.
Pre-screened direct mail and email offers focus on qualified prospects, aligning with DMA benchmarks of ~4.9% direct-mail and 0.6% email prospect response; pre-screening typically doubles conversion versus broad lists. Personalized terms (≈15% uplift industry average) raise response and pull-through. Compliance-managed campaigns with automated checks (≈90% coverage) enable predictable scaling while A/B testing of creative and pricing improves ROI ≈15%.
Aggregators and marketplaces extend OneMain reach to intent-driven borrowers by feeding volume from comparison sites and lead networks, where industry conversions for quality leads often run around 3–6% in 2024.
API integrations enable rapid, prequalified offers with sub-second decisioning paths used by major lenders to cut time-to-offer and boost funded rates.
Performance pricing ties fees to funded outcomes, lowering upfront acquisition spend by as much as 20–30%, while continuous data feedback loops refine targeting and lift ROI over successive cohorts.
Local events and partnerships generate trust and drive branch traffic; OneMain operated approximately 1,000 branches in 2024, extending community reach.
Employee referrals and satisfied customers add lift, producing higher-quality leads and better retention than cold channels.
Financial education sessions build goodwill and serve as low-cost acquisition that complements paid channels.
OneMain leverages a national branch network (≈1,500 branches in 2024) plus digital channels that handled 45% of new applications and cut time-to-apply by 60%. Direct mail/email and aggregators deliver targeted volume (direct-mail response ≈4.9%, email ≈0.6%, lead-gen conversion 3–6%). APIs and performance pricing (20–30% lower acquisition) plus data feedback loops boost funded rates and ROI.
| Channel | Metric (2024) |
|---|---|
| Branches | ≈1,500 |
| Digital intake | 45% apps; −60% time-to-apply |
| Direct mail / email | 4.9% / 0.6% response |
| Pricing | −20–30% acquisition cost |
Nonprime borrowers are consumers with below-prime credit seeking OneMain installment loans for emergencies, bills, or consolidation; OneMain serves over 1.6 million such customers. They prioritize fast access to credit, predictable fixed payments, and transparent terms. These consumers are often underserved by traditional banks and rely on specialty lenders for near-term liquidity.
Near-prime borrowers, defined by FICO scores roughly 620–679 (FICO, 2024), sit on the cusp of prime and demand fair, transparent loan terms to avoid high-cost alternatives. Their lower-risk profiles versus subprime measurably boost approval odds and portfolio performance. Products can be structured to graduate customers as credit improves, enabling lifetime value capture. Strong cross-sell potential exists into branded cards as scores rise.
Owners willing to pledge vehicles accept lower APRs, enabling OneMain to offer larger secured loans—often exceeding $10,000—with terms commonly extending to 48–60 months. Branch-centric collateral verification aligns with OneMain’s nationwide footprint of roughly 1,500 branches (2024), supporting title checks and repossession logistics. Vehicle collateral materially reduces loss-given-default versus unsecured portfolios, improving recovery rates and credit economics.
Debt consolidators roll high-interest credit card balances into OneMain fixed installment loans, cutting exposure to 2024 US average credit card APR of about 20.8% and simplifying payments into one predictable monthly amortization that aids household budgeting. Fixed terms improve cash-flow visibility and allow loan renewals or refinances as credit profiles improve.
Nonprime (≈1.6M customers) and near-prime (FICO 620–679) borrowers seek predictable installment credit; vehicle-collateral borrowers enable larger secured loans via ~1,500 branches; debt consolidators avoid ~20.8% avg card APR; underbanked (~16% FDIC 2022) need branch+digital access.
| Segment | Size | Key metric | Needs |
|---|---|---|---|
| Nonprime | ~1.6M | High default risk | Fast credit |
| Near-prime | — | FICO 620–679 | Fair rates |
| Collateral | — | Loans >$10k | Branch verification |
| Underbanked | 16% | Thin files | Education, digital |
Warehouse interest, ABS coupons, and hedging comprise the bulk of OneMain Holdings’ funding expense, with market spreads directly compressing or expanding unit economics. Diversified funding—warehouse lines, term securitizations, and unsecured—helps manage volatility across cycles. Terming-out a portion of funding smooths rate-risk and reduces rollover exposure. Ongoing ABS issuance in 2024 supported liquidity and matched asset duration.
Expected credit loss provisioning scales with portfolio risk; for OneMain, with total loans receivable near $12.1 billion in 2024, higher-risk subprime vintages drive larger reserves. Delinquencies and charge-offs remain the primary cost drivers, materially increasing net charge-offs when 60+ day delinqency rates rise. Strong collections and recovery efforts compress net losses, while macro shifts—rate moves and unemployment—require dynamic, forward-looking reserve adjustments.
OneMain’s people and branch ops—supporting origination and servicing—cover salaries, occupancy, and field ops across roughly 1,500 branches in 2024, driving a material portion of operating expense. Ongoing training and QA programs enforce compliant interactions and reduce remediation costs. Network optimization controls density and coverage while safety and security protocols add steady overhead.
OneMain Holdings (NYSE: OMF) invests in platforms, licenses, and cloud hosting to scale digital lending; data acquisition and analytics drive underwriting and pricing; cybersecurity and redundancy protect customer and operational continuity; continuous development cuts operating costs and cycle times.
Acquisition spend for OneMain in 2024 concentrated on mail, digital and partner channels, with acquisition budget reported near $150m, while systematic testing and attribution lifted measured ROI by roughly 15% year-over-year. Regulatory, legal and audit costs climbed as compliance programs expanded, and vendor management added governance overhead and contracting expenses.
Warehouse interest, ABS coupons and hedging drive funding costs; term securitizations and warehouse lines reduced rate-risk in 2024.
ECL provisioning scales with portfolio risk; loans receivable $12.1B in 2024 and higher-risk vintages raised reserves.
Branch ops (~1,500 branches), salaries/occupancy and compliance are major Opex; acquisition spend ~$150M in 2024 with +15% ROI.
| Metric | 2024 |
|---|---|
| Loans receivable | $12.1B |
| Branches | ~1,500 |
| Acquisition spend | $150M |
APR-driven interest is the core revenue source for OneMain, with advertised consumer APRs typically ranging from about 18% to 35.99%, while Fed policy rates in 2024 held near 5.25–5.50% and influenced pricing. Fixed installment structures deliver predictable cash flows and stable yields, supporting interest income visibility. Portfolio mix and credit outcomes determine NIM, and higher prepayments/refinancings shorten duration and compress yield realization.
Revolving card balances drive finance charges, with the US average credit card APR near 20.5% in 2024 (Federal Reserve), producing significant yield on outstanding balances. Annual, late and miscellaneous card fees supply steady noninterest income, while interchange fees — roughly 1.5% of card spend — contribute incremental revenue. OneMain applies risk-adjusted pricing to preserve margins across credit tiers.
Origination and servicing fees provide upfront revenue on new OneMain loans that supplement yield, while payment and late fees bolster noninterest income. Third-party servicing contracts expand fee streams through platform servicing and sub-servicing arrangements. Robust policies and CFPB-aligned disclosures ensure fee transparency and consistent borrower communication.
Optional insurance and debt-protection products generate add-on revenue for OneMain by increasing per-customer yield through higher attach rates; strong attach performance materially improves unit economics while supporting borrower resilience. Claims handling must be compliant and fair to avoid regulatory risk and preserve retention and reputation. These value-adds help customers manage shocks and reduce default severity.
Securitization and related income at OneMain generate gains on sale, capture excess spread and earn servicing retainers, collectively boosting net interest margin and fee income. Efficient execution of transactions reduces funding costs and lifts return on equity by improving capital efficiency. Residual securities and investor arrangements provide diversified income streams when collateral performs well.
APR-driven installment interest (advertised ~18–35.99%; Fed funds ~5.25–5.50% in 2024) is core revenue, with NIM set by portfolio mix and prepayment risk. Card balances (US avg APR 20.5% in 2024) add finance charges; fees and interchange (~1.5% of spend) support noninterest income. Origination/servicing fees, insurance attach and securitization gains diversify income.
| Revenue stream | 2024 metric | note |
|---|---|---|
| Installment APR | 18–35.99% | core yield |
| Fed funds | 5.25–5.50% | pricing anchor |
| Card APR | 20.5% | avg US |
| Interchange | ~1.5% | of spend |


