
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
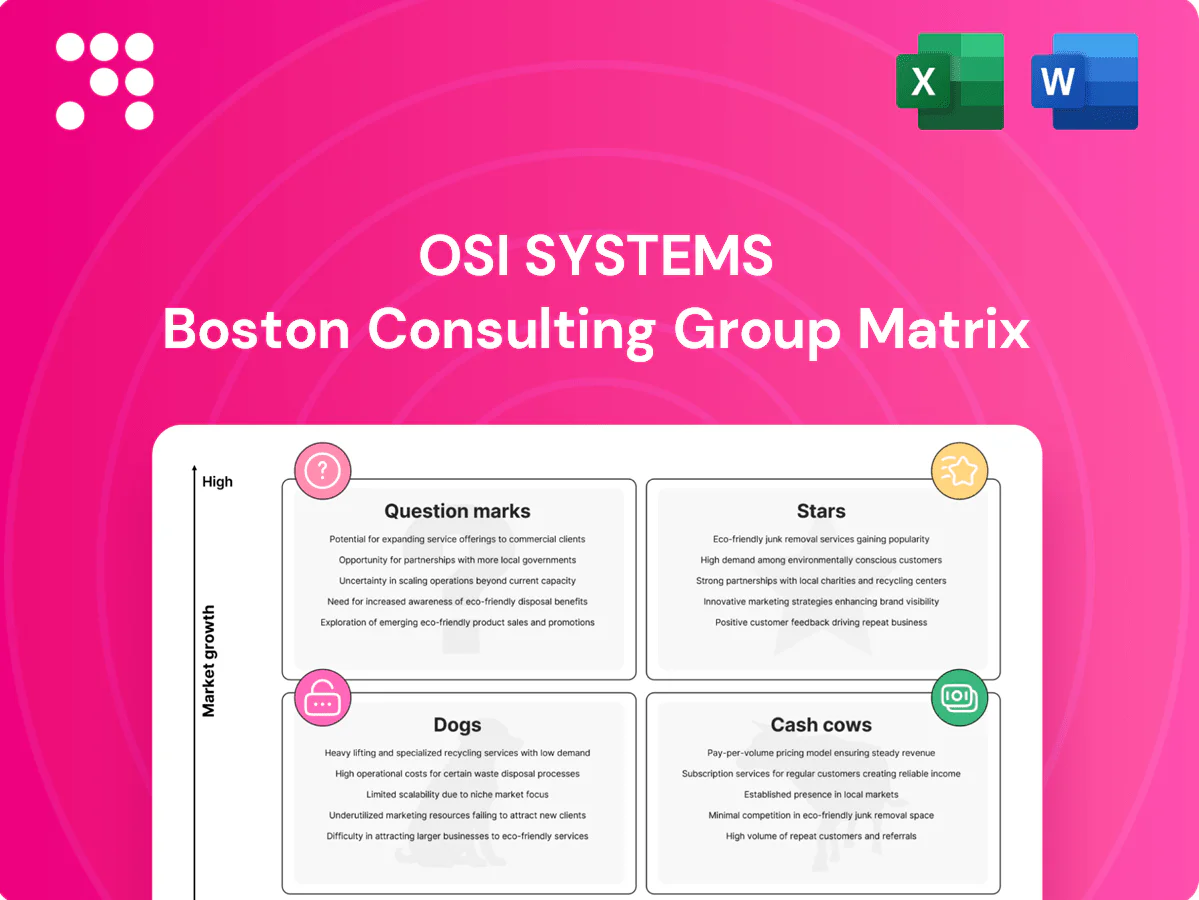
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Peek under the hood of OSI Systems with our concise BCG Matrix—see which product lines are scaling fast, which fund the business, and which drag returns. This snapshot points you where to focus, but the full BCG Matrix gives quadrant-by-quadrant placements, data-backed recommendations, and a ready-to-use strategic roadmap. Buy the complete report for Word and Excel files that save you hours and turn insight into action.
Airport security scanners sit in OSI Systems flagship baggage and checkpoint portfolio within a fast-growing global aviation security market projected at ~7% CAGR; OSI reported roughly $1.6B revenue in FY2024 and holds strong share at major airports, consistently winning upgrade cycles. These systems consume significant capex and service resources today, but the expanding installed base creates a recurring-service flywheel that can mature into stable, high-margin cash flows.
In 2024 countries continue scaling cargo throughput and tightening customs, and OSI Systems’ high-energy X-ray/CT lines remain market-leading in spec and adoption. Projects are large, politically backed and sticky, producing lumpy but growthy revenues with repeatable follow-on service streams. Maintain investment to outpace rivals on image quality and automation to defend star positioning.
AI analytics layered on OSI Systems scanners raises detection rates and operator productivity, and adoption is accelerating as agencies push for automation—Gartner forecasts 30% of organizations will use AI-driven security tools by 2025. The software is high-margin and subscription-friendly, compounding revenue with each hardware win and recurring ARR lift. Prioritizing roadmap and integrations can lock in de facto standard status.
Turnkey security programs bundle equipment, systems integration and lifecycle service for full airport and port deployments; projects are execution-heavy but lock in multi-year revenue via 3–7 year contracts and typical ticket sizes of $3M–$25M. High barriers to entry and complex certifications create defensibility, while the global aviation and maritime security market was roughly $9B in 2024, supporting scale replication.
Defense-grade optoelectronic subsystems supply high-spec sensors for aerospace and defense that ride FY2024 U.S. defense budget tailwinds (~858 billion) and rising global military spend (SIPRI 2023: 2.24 trillion). OSI holds ITAR, AS9100 and ISO 9001 credentials few rivals match, supporting steady production volumes and multi-year tech-refresh cycles (~7–10 years). Strategy: double down where performance trumps price.
Airport/CT scanner portfolio is a Star: FY2024 revenue contribution major (OSI Systems ~$1.6B total), market ~ $9B (2024) with ~7% CAGR, large $3M–$25M contracts and recurring high-margin service/AI SaaS tailwinds. Strong share at major airports, certification-driven defense sensor sales add stickiness and multi-year refresh cycles. Prioritize capex and software roadmap to cement leadership.
| Metric | Value (2024) |
|---|---|
| OSI FY2024 rev | $1.6B |
| Market size | $9B |
| CAGR | ~7% |
| Contract size | $3M–$25M |
 Detailed Word Document
Concise BCG assessment of OSI Systems' units: stars to dogs, investment, hold or divest guidance with competitive and trend context.

 Customizable Excel Spreadsheet
One-page OSI Systems BCG Matrix that pinpoints underperformers and growth bets—clear, export-ready, C-level polished.
Thousands of deployed scanners and bedside monitors require regular calibration, parts replacement and compliance checks, creating a recurring installed-base service cash cow for OSI Systems in 2024. Low churn and predictable margins mean minimal promotional spend, with uptime and SLAs driving renewals. Focus on efficient milkings while digitizing workflows and remote diagnostics to reduce truck rolls and lower service cost per unit.
Legacy checkpoint X-ray lines remain cash cows for OSI Systems, selling into cost-sensitive markets where 2024 demand kept volumes steady and the Security segment saw roughly 8–10% of revenue from mature models. Engineering costs are fully amortized and parts are standardized, lowering incremental COGS and preserving gross margins. Tight price discipline has delivered dependable cash flow, so OSI maintains just enough support to keep the line profitable.
Hospital monitoring is stable, spec-driven and replacement-cycled, with OSI’s installed base generating recurring disposables and service revenue; the global patient monitoring market was about USD 20 billion in 2023 and is forecast to grow ~6% annually through 2030. OSI’s core platforms deliver modest top-line growth but solid margins, so prioritize manufacturing optimization and maintaining tight regulatory approvals to protect share and recurring revenue.
Industrial opto components for OEMs generate steady repeat orders across medical, industrial and instrumentation channels, with designs commonly locked for 3–5 years, stabilizing throughput and revenue. Margin drivers are mix management and yield optimization rather than marketing spend; protecting key accounts and keeping lead times under 8 weeks preserves profitability and share.
Electronics manufacturing for long-life programs at OSI Systems focuses on contract builds of mature assemblies with predictable volumes and low NRE (typically under 5% of program value in 2024), delivering stable routing and ~90% capacity utilization; lines running full are reliable cash generators and lean upgrades in 2024 squeezed roughly 2–3 percentage points of margin.
OSI’s cash cows in 2024: installed-base service for scanners/monitors, legacy checkpoint X-rays, hospital monitoring and industrial opto/electronics deliver steady margins and recurring cash, with Security legacy = ~8–10% revenue and electronics NRE ≈5% (2024). Focus on uptime, yield and lead-times (<8 weeks) to sustain free cash flow.
| Asset | 2024 KPI |
|---|---|
| Security legacy | 8–10% rev |
| Patient monitoring | Global market 2023 USD20B, CAGR ~6% |
| Electronics | NRE ≈5%, util ≈90% |
The file you're previewing is the exact OSI Systems BCG Matrix you'll receive after purchase. No watermarks or placeholders—just the finished, professionally formatted report. Built from market-backed analysis, it's ready to edit, print, or present. Purchase unlocks the full file delivered straight to your inbox. No surprises, no revisions needed.
One-off bespoke government builds lock engineering and spare-part inventories into a single program, often creating lifecycle obligations that outlast revenue; with the US FY2024 defense budget at $858B, program-specific demand can still vanish when funding stops and gross margins evaporate. These designs are hard to scale and costly to service; sunset or spin down to avoid ongoing drag on cash and capacity.
Low-end commodity patient devices in OSI Systems face a race-to-the-bottom as no-name vendors drive prices down and erode margins. Limited product differentiation and weak brand pull leave these units with thin margins and high support costs that often consume profits. Divestiture is preferable to continuing to chase low-margin volume.
Legacy non-networked monitors fail current hospital IT interoperability expectations and conflict with HIPAA-secure telemetry trends; by 2024 hospital IT procurement favors networked replacements, driving replacement demand but often at 20–30% discount to list price. Keeping units in the field raises service and parts costs with negligible revenue upside. Push structured upgrade programs and trade-in incentives to retire remaining stock.
Standalone walk-through metal detectors face saturated, undifferentiated basic gates; procurement is tender-driven and typically awarded to the lowest bidder, compressing margins while aftermarket revenue is thin. Given limited upsell and commoditization, OSI Systems should shift emphasis toward integrated checkpoint solutions that bundle screening, analytics, and service contracts to restore margin and drive recurring revenue.
Low-margin EMS spot buys tie up OSI Systems' lines in short-run builds with volatile specs, cutting line efficiency by as much as 20–25% in industry benchmarks and turning every batch into a fire drill; margins on such jobs often fall below 5% and customer repeatability is typically under 20%, so prune aggressively and reallocate capacity to higher-margin, repeatable programs.
Dogs: low-growth, low-share products (legacy gates, basic EMS builds, commodity patient devices) drag margins below 5% and tie capacity; FY2024 US defense budget 858B offers patchy program demand but funding stops erase revenue; recommend divest, sunset, or bundle into integrated solutions to recover margin and free capacity for core growth areas.
| Item | 2024 Metric | Action |
|---|---|---|
| Basic gates | procurement lowest-bid; aftermarket thin | shift to integrated checkpoints |
| EMS spot buys | margins <5%; line hit 20–25% | prune; redeploy capacity |
Integrated automated checkpoint lanes and orchestration show measurable throughput gains in pilots, but overall commercial share remains nascent as airports continue pilot programs rather than universal adoption.
Regulators such as TSA and EASA are accelerating CT mandates for checked baggage, driving a reported 35% increase in global CT deployments in 2023–24 while procurement cycles remain uneven—US and Middle East faster, APAC and LATAM slower. OSI Systems has proven CT technology but market share varies by region; security segment contributed roughly one-third of OSI revenue in recent filings. Prioritize certifications, IEC/EN interoperability and airline/airport integrations; execute land-convert-expand through airline alliances and ground-handling partners to scale deployment.
Connected care is a high-growth segment but incumbents (Epic/Cerner and large medtech partners) cover about 70% of US hospital beds, locking big IDNs into integrated stacks. OSI can wedge in on price-performance and open APIs, leveraging OSI Systems’ device experience to offer lower-cost telemetry gateways and integration. Success requires partnerships with payers/IDNs and proof of outcome savings in pilots; without rapid scale it risks drifting to Dog.
Applying imaging to NDT and quality control is attractive but nascent for OSI, with the global NDT market ~9.0B in 2024 and adoption still concentrated in aerospace and energy; pilots typically run 12–24 months and buyers are highly fragmented. Target verticals where regulation favors imaging (aerospace, medical device, energy) to shorten sales cycles; early wins will set scale and valuation trajectory.
Sensors for semiconductor and EV equipment are a Question Mark: demand swings with capex but secular trends rose in 2024 as wafer fab equipment spending rebounded to roughly $83B and global EV sales topped about 14M units, underpinning long-term upside. Fit and qualification cycles create high entry friction, but successful design-ins can compound volumes for years. OSI should target a focused push on a few anchor accounts to convert this into a Star.
Integrated lanes, CT baggage, connected care, NDT and sensors are Question Marks: pilots prove tech but commercial share is nascent; CT deployments +35% (2023–24) while security ≈33% of OSI revenue; NDT ≈ $9.0B (2024); WFE ~$83B and EV sales ~14M (2024) offer upside if anchor design-ins scale.
| Metric | 2024 Value | Note |
|---|---|---|
| Security rev share | ≈33% | OSI filings |
| NDT | $9.0B | 2024 market |
| WFE | $83B | 2024 |
| EV sales | 14M | 2024 global |


