
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
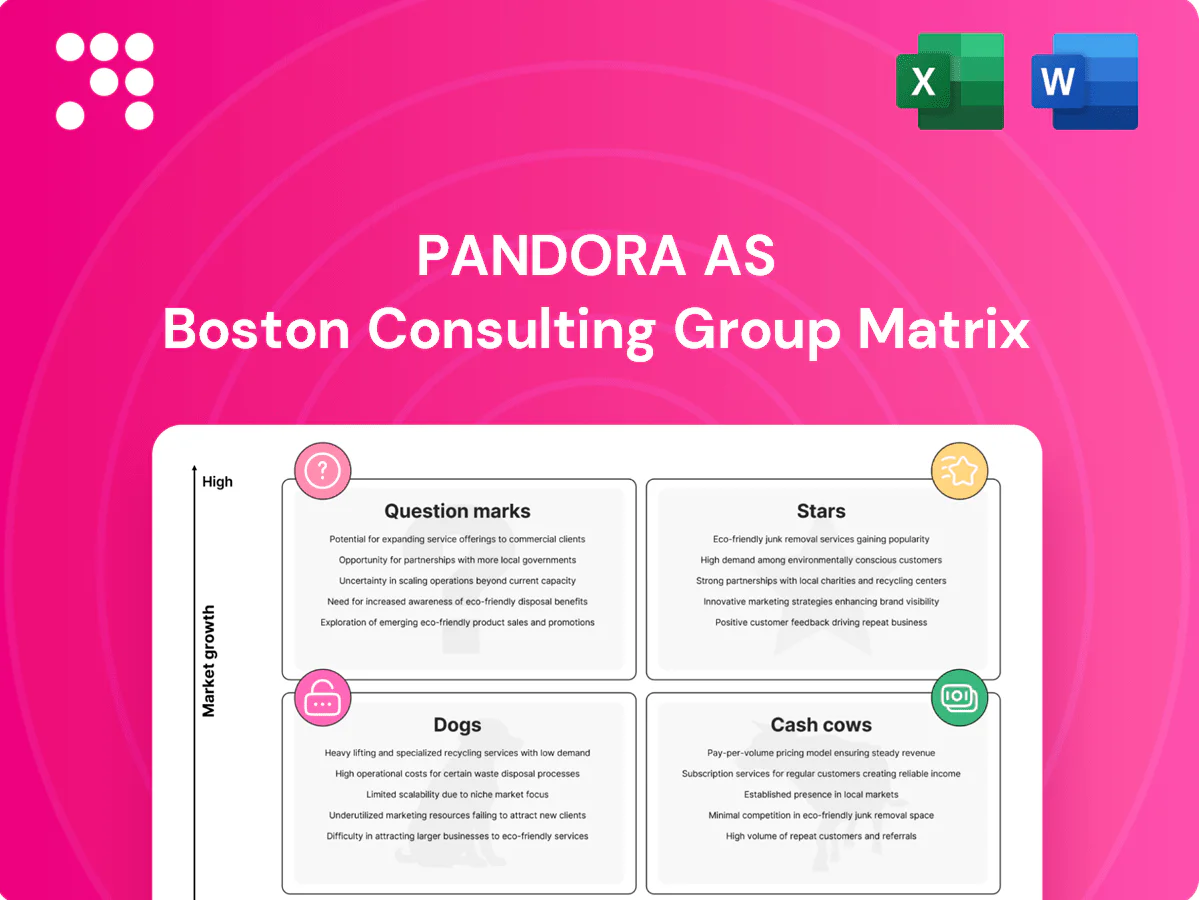
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
The Pandora AS BCG Matrix preview shows where key products sit today — which are driving growth, which fund the business, and which need tough calls. Want the full picture? Purchase the complete BCG Matrix for quadrant-by-quadrant placements, data-backed recommendations, and ready-to-use Word and Excel files that let you act fast and present with confidence.
High-growth collab drops with major IPs pull new fans fast, driving online traffic spikes often 30–50% and in-store sell-through rates that can exceed 60% during launch windows; these drops lead category conversation and secure premium digital and retail placement. Keep fueling collabs and marketing or momentum slips; hold share now and these can mature into steady revenue engines with higher lifetime value per customer.
DTC e-commerce grew double-digit in 2024 versus flat-to-moderate store sales, giving Pandora full margin control and improving gross margins. Strong site conversion, first-party data and CRM lift repeat rates and AOV, keeping the digital flywheel spinning. Continued investment in UX, personalization and paid performance is recommended to protect online share. If maintained, DTC can evolve into a long-term profit pillar.
Pandora’s personalization and engraving sits in the BCG Matrix quadrant where demand is rising and Pandora already leads; personalized products drive higher attachment rates and lift AOV, consistent with Epsilon’s finding that 80% of consumers are more likely to buy when experiences are personalized. McKinsey estimates personalization can boost revenue by up to 15%, but scaling requires operational investment and smart merchandising to keep fulfillment smooth. With share defended through quality and platform integration, personalization is positioned to graduate to cash cow status.
As China digital retail rebounded in 2024 (e-commerce GMV up ~9% to c. RMB 15tn), Pandora’s digital-first channels can capture outsized share given strong brand awareness; execution—local collabs, social commerce, rapid fulfillment—will determine success. Nail omnichannel logistics and KOL-driven drops and this market becomes a compounder for Pandora’s growth and margin expansion.
Social-led product drops harness urgency in a social commerce market estimated at about 1.2 trillion USD in 2024 and growing ~20% YoY, driving rapid sell-through but demanding high upfront spend on content and inventory. Regular micro-releases and creator collaborations keep Pandora’s community engaged and conversion rates elevated, and if cadence is sustained these drops can evolve from cash-hungry experiments into steady profit streams.
Stars: high-growth collab drops drive traffic spikes of 30–50% and launch sell-throughs >60%, DTC grew ~12% in 2024 improving gross margins; personalization can boost revenue up to 15% and 80% of consumers prefer personalized offers. Social commerce (~USD 1.2tn, +20% YoY) and China e‑commerce (RMB 15tn, +9% in 2024) are key scaling levers; sustain cadence to convert stars into long-term profit engines.
| Metric | 2024/Impact |
|---|---|
| Traffic spike | 30–50% |
| Launch sell-through | >60% |
| DTC growth | ~12% |
| Personalization uplift | up to 15% |
| Social commerce | USD 1.2tn, +20% YoY |
| China e‑com GMV | RMB 15tn, +9% |
 Detailed Word Document
In-depth BCG Matrix review of Pandora AS, mapping Stars, Cash Cows, Question Marks, and Dogs with investment recommendations.

 Customizable Excel Spreadsheet
One-page BCG matrix for Pandora AS that clarifies portfolio choices, reduces decision friction and exports cleanly to slides.
Core charm bracelets hold a high market share in a mature global category (global jewellery market ~US$300bn in 2024), delivering strong gross margins and predictable replenishment cycles for Pandora. Low promotional need and steady in-store and online traffic make them reliable cash generators. Management treats them as cash cows, milking profits while gently refreshing designs to sustain demand.
Bestselling silver charms are Pandora AS cash cows: evergreen, year-round themes delivering high-volume, low-complexity sales and dependable cash flow. In 2024 these core charm ranges underpinned Pandora’s retail velocity while requiring minimal media spend, helping sustain gross margins and fund new growth bets. Their steady unit sales and predictable replenishment financed product and channel expansion throughout 2024.
Occasion-based gifting (Valentine’s, Mother’s Day, year-end holidays) remains Pandora AS cash cows, delivering predictable peaks in sales and high repeat purchase behavior; in 2024 these seasonal windows continued to drive the bulk of promotional volume while preserving strong margin mixes. Modest marketing refreshes sustain awareness without eroding profitability, so bank the gains and avoid overspending on broad campaigns.
Charm refills and add-ons drive repeat purchases as existing owners expand bracelets, showing classic cash cow behavior with low acquisition cost and high lifetime value; simple merchandising and standardized SKUs keep gross margins and inventory turns efficient.
Core charm bracelets and bestselling silver charms are Pandora AS cash cows: high share in a mature global jewellery market (~US$300bn in 2024), delivering predictable replenishment and strong gross margins. Over 2,000 Pandora concept stores across 100+ markets provide stable retail throughput and fund growth. Occasion-based gifting windows (Valentine’s, Mother’s Day, year-end) deliver predictable seasonal peaks and high repeat purchases.
| Metric | 2024 Fact |
|---|---|
| Global jewellery market | ~US$300bn |
| Pandora concept stores | >2,000 |
| Markets | 100+ |
The file you're previewing here is the exact Pandora AS BCG Matrix you'll receive after purchase. No watermarks, no demo text—just a fully formatted, analysis-ready report built for decision-makers. After buying, the final document is sent straight to your inbox and is immediately editable, printable, and presentable. Use it in planning, investor meetings, or internal strategy without any tweaks.
Full-gold luxury line: low share in a slow segment, misaligned with Pandora’s affordable-luxury positioning and yielding high costs with sluggish inventory turns. Turnaround spend on premium gold rarely pays back given channel and price-position mismatch. Consider exit or severe pruning to cut capex and recover working capital.
Low-traffic wholesale doors sit in saturated retail with weak sell-through and limited brand control. They tie up inventory and management attention and typically reach break-even at best. Pandora's 2024 strategy accelerates rationalization of wholesale points and redeployment of stock and marketing toward DTC channels.
Over-assorted legacy SKUs clog Pandora’s shelves, dragging working capital and confusing shoppers across 100+ markets in 2024. Excess styles force frequent markdown cycles that erode gross margin and increase inventory days. Prune the tail, retire slow SKUs and accelerate turnover to free cash and improve shelf clarity.
Legacy packaging upsells are add-on items with minimal attachment rates and negligible lift; Pandora reported roughly 25 billion DKK revenue in 2024, and these upsells do not materially move top-line or margin. They create operational hassle, inventory complexity and occupy valuable shelf space in flagship and wholesale channels. Recommendation: sunset and simplify SKUs to improve fulfilment efficiency and gross margin.
Stale seasonal collections sit as Dogs in Pandora A/S BCG matrix: out-of-season stock that lingers, driving markdowns and tying up working capital with low growth, low excitement and low market share; recurring discount traps compress gross margins and erode brand premium.
Dogs: low-share, low-growth SKUs (full-gold luxury, stale seasonals, legacy upsells, low-traffic wholesale) drain working capital and compress margins; Pandora reported ~25 billion DKK revenue in 2024 but these segments offer negligible ROI and operational drag. Recommend prune/exit, redeploy inventory to DTC, tighten SKUs and shift to limited runs/pre-orders to restore turns.
| Metric | 2024 |
|---|---|
| Company revenue | ~25 billion DKK |
Lab-grown diamonds are a high-growth market (global value about USD 16.6bn in 2023, projected CAGR ~6.5% to 2030), but Pandora’s share remains small after 2023–24 rollouts. Brand permission looks promising; unit economics require scale to reach comparable margins. Invest in design, storytelling and sharpen distribution to capture volume. If traction stalls, reallocate capital quickly to higher-return categories.
Men’s jewelry is a Question Mark for Pandora: consumer interest has risen sharply (search interest up ~25% YoY in 2023–24) while Pandora’s penetration remains under 5% of its global customer base, so product-market fit is still forming. Pandora should run test capsules, influencer-led drops and bundled offers to refine assortment and price ladders. Scale only in markets where CAC/LTV meets Pandora’s acquisition economics and break-even unit economics. Monitor cohort LTV and CAC monthly before doubling down.
India (population 1.428 billion in 2024) and SE Asia (approx. 679 million) are fast-growing markets—IMF 2024 GDP forecasts: India ~6.8%, ASEAN ~4.5%—but Pandora faces uneven brand awareness; store economics and online partnerships remain in test mode. Localized designs could drive step-changes; scale depends on early cohort payback and unit-level profitability.
Virtual try-on and app ecosystem sit as Question Marks: engagement rising (pilot MAU +45% in 2024) but monetization remains early; potential to lift conversion 10–15% and enable deeper personalization if tech polish and content investment are funded. Greenlight only if experiments show sustained basket size (+20%) and repeat purchase rate uplift (≥15%).
Sustainability-led collections tap younger buyers: surveys in 2024 show Gen Z and Millennials drive demand for recycled metals, and Pandora reports using recycled silver at scale and increasing recycled gold sourcing as part of its 2023–24 sustainability push.
Category growth is real but still a small share of Pandora sales; overall group revenue was DKK 23.6bn in 2023, so even a 3–5% sustainable-collection share implies modest current contribution but clear growth runway.
Success requires certification rigor (chain-of-custody, responsible sourcing) and smart pricing to avoid margin erosion; premium pricing is possible but only with verified credentials and transparent value communication.
Strategically, back proven winners with investment in certification and marketing, and exit laggards quickly to protect margins and brand clarity.
Question Marks: high-growth adjacencies (lab-grown diamonds, men’s, India/SEA, virtual try-on, sustainable collections) show demand signals but low share; require tight cohort CAC/LTV, unit-economics tests and quick reallocation if metrics fail (use DKK 23.6bn 2023 revenue base).
| Adjacency | Signal | Trigger |
|---|---|---|
| Lab-grown | USD16.6bn (2023) | Scale margins |
| Men’s | Search +25% (2023–24) | CAC/LTV fit |


