
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
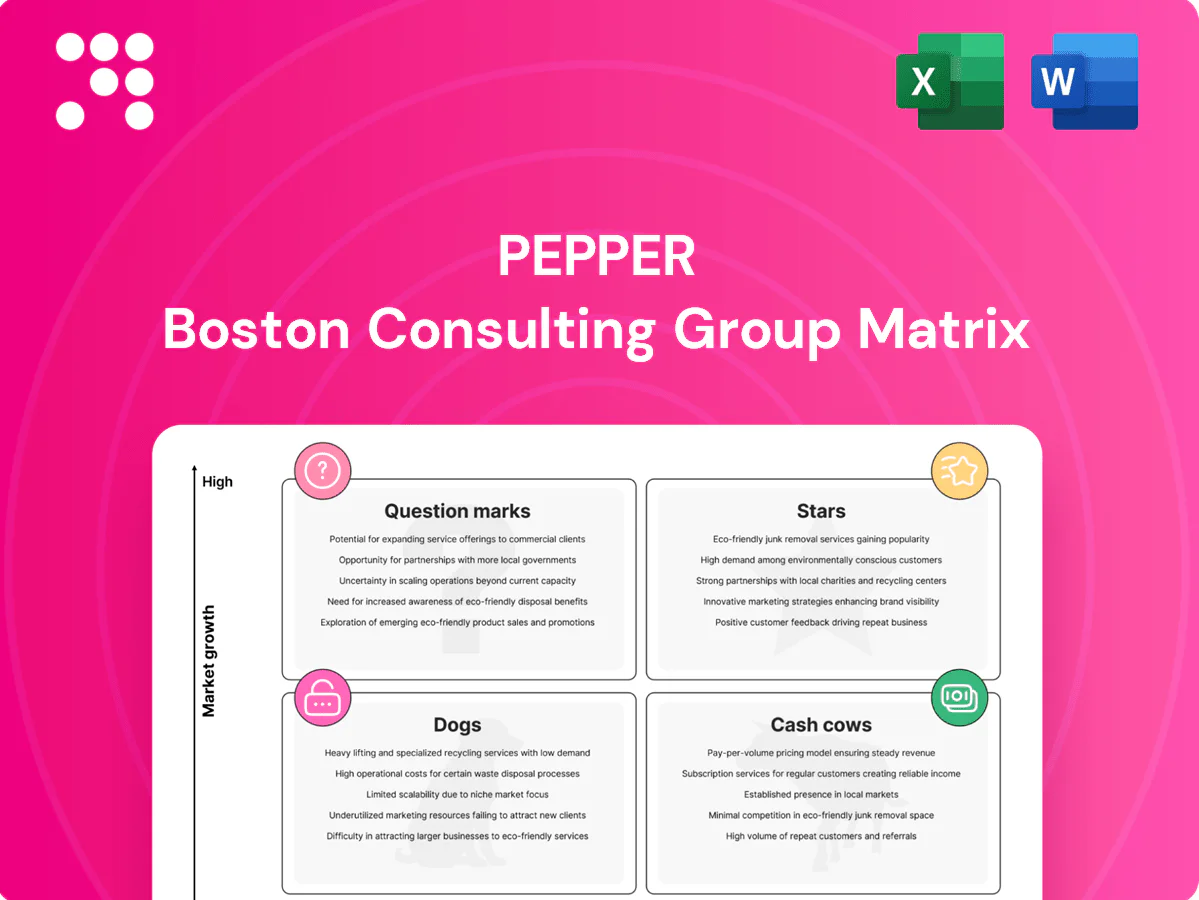
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
The BCG Matrix is a powerful tool for understanding your product portfolio, categorizing them as Stars, Cash Cows, Dogs, or Question Marks based on market share and growth. This initial glimpse highlights the core concepts, but to truly leverage its strategic power, you need the full picture.
Unlock a comprehensive analysis that delves into each product's specific placement within the matrix, offering data-driven insights and actionable recommendations for optimizing your investments and resource allocation. Purchase the full BCG Matrix to transform this foundational knowledge into a concrete strategy for growth and profitability.
Pepper Money's mortgage originations experienced a robust 5% expansion in 2024, hitting $4.1 billion. This growth was particularly strong in the latter half of the year, with a significant 27% increase compared to the first six months.
This upward trend firmly places their mortgage business as a frontrunner within the non-bank lending sector. The company's strategic emphasis on cultivating strong broker partnerships and ensuring swift loan processing times has been a key driver of this impressive performance.
Self-Managed Super Fund (SMSF) mortgages, launched in Q4 2023, represent a promising growth area for Pepper Money. By the end of 2024, these products accounted for 6% of the company's total mortgage originations. This early success highlights a significant uptake in a specialized market segment.
The strong initial performance of SMSF mortgages suggests a high growth potential within the Australian financial landscape. Pepper Money's strategic focus on this niche is designed to capture a growing demand from individuals seeking to utilize their superannuation funds for property investment.
Continued investment and product development in SMSF mortgages are anticipated to strengthen Pepper Money's competitive position. This strategic emphasis is key to solidifying its market share and capitalizing on the evolving needs of SMSF investors.
Pepper Money launched its Sharia lending solution in June 2024, targeting a significant underserved market segment. This innovative offering quickly captured 2% of mortgage originations in its first year, demonstrating strong initial adoption.
This strategic move allows Pepper Money to tap into a distinct and growing customer base seeking compliant financing options. The company anticipates continued growth as it expands its partner network and further promotes this specialized product.
High Loan-to-Value (LTV) residential mortgages represent a significant growth opportunity within the Pepper BCG Matrix, often categorized as Stars due to their potential for high market share gains in a rapidly expanding sector. Pepper Money's strategic introduction of 90% LTV options in July 2025 directly addresses the growing demand from first-time buyers and individuals with limited savings, a demographic increasingly active in the property market.
This product expansion is designed to capitalize on the upward trend in property values and the persistent need for accessible homeownership solutions. By offering these higher LTV products, Pepper Money is positioning itself to capture a larger portion of this dynamic and expanding market segment.
Commercial Real Estate (CRE) loans represent a significant growth area for Pepper Money, reflecting a robust performance in this sector. The company is strategically positioned to leverage the increasing participation of non-bank lenders in the CRE market.
This segment is crucial for Pepper Money's diversification and profitability. For instance, in 2024, the CRE lending market saw continued activity, with many non-bank lenders expanding their portfolios to meet demand from businesses seeking flexible financing solutions.
Key aspects of CRE loans within Pepper Money's portfolio include:
Stars in the BCG Matrix represent business units or products with high market share in a high-growth industry. For Pepper Money, their expanding mortgage origination volume and strategic product launches in high-demand segments align with the characteristics of Stars. The company's ability to capture market share in growing areas like SMSF and Sharia lending, alongside their high LTV offerings, positions these as potential Stars.
The 90% LTV residential mortgages, introduced in mid-2025, are a prime example of a Star product. This segment is experiencing robust growth driven by first-time buyers, and Pepper Money's proactive offering aims to secure a significant market share. Similarly, the strong initial uptake of Sharia lending, capturing 2% of originations within its first year, highlights its Star potential in an underserved but growing market.
| Product Segment | 2024 Originations (AUD Billions) | Growth Rate (YoY) | Market Growth Potential | Pepper's Market Share Potential |
| Total Mortgages | 4.1 | 5% | High | Increasing |
| SMSF Mortgages | 0.25 (6% of total) | N/A (Launched Q4 2023) | Very High | Growing |
| Sharia Lending | 0.08 (2% of total) | N/A (Launched June 2024) | High | Growing |
| 90% LTV Mortgages | Emerging (Launched mid-2025) | N/A | High | Targeting High Share |
 Detailed Word Document
Strategic overview of product portfolio performance, guiding investment decisions based on market share and growth.

 Customizable Excel Spreadsheet
A clear visual representation of your portfolio, simplifying strategic decisions.
Pepper Money's established Australian non-conforming residential mortgages are a classic cash cow. This segment, where Pepper Money holds a significant market share, consistently delivers strong net interest margins and substantial cash flow, underpinning the company's financial stability.
These mature products require less investment in marketing and development, allowing them to generate considerable profits. For instance, in the 2024 financial year, Pepper Group reported a net profit after tax of AUD 103.2 million, with mortgage origination remaining a key driver.
Pepper Money's core asset finance portfolio, despite a modest dip in originations during 2024, stands as a formidable pillar within the Australian market. With a robust Assets Under Management (AUM) reaching $5.6 billion, this segment consistently delivers strong cash flow and is a significant revenue driver for the company.
The loan servicing segment for Pepper Money acts as a classic cash cow within the BCG matrix. This unit manages existing loans and generates steady, high-margin fees. In CY2024, Servicing Assets Under Management (AUM) reached $3.3 billion, highlighting its established scale.
Once loans are on the books, the capital expenditure needed for servicing is minimal. This low investment requirement allows the segment to generate consistent income, bolstering Pepper Money's overall financial stability and profitability.
The acquisition of HSBC's New Zealand mortgage portfolio in December 2023 significantly boosted Pepper Money's Assets Under Management (AUM). This move injected a substantial, established portfolio into their operations.
This established portfolio acts as a core cash cow for Pepper Money. It provides a predictable and stable income stream, reinforcing the mortgage segment's cash-generating capacity within the mature New Zealand market. The consistent returns generated solidify its position as a strategic asset.
Within Pepper Money's portfolio, prime residential mortgages represent a classic cash cow. These products are designed for borrowers with strong credit profiles, making them a lower-risk segment.
While the profit margins might not be as high as some of their more specialized offerings, the sheer volume and stability of this market provide a consistent and reliable income stream. This reliability is crucial for funding growth in other areas of the business.
For instance, in 2024, the Australian prime mortgage market continued to show resilience, with major lenders reporting steady demand. Pepper Money, by focusing on this segment, benefits from lower default rates, which directly translates to predictable earnings.
Cash cows in the Pepper BCG Matrix are business segments that have a high market share in a mature, slow-growing industry. These units generate more cash than they consume, providing a stable income stream for the company. Pepper Money's established non-conforming residential mortgages are a prime example, consistently delivering strong net interest margins and substantial cash flow. The loan servicing segment also fits this description, generating high-margin fees from managing existing loans with minimal capital expenditure.
| Pepper Money Segment | BCG Category | Key Characteristics | 2024 Financial Data/Context |
|---|---|---|---|
| Non-Conforming Mortgages | Cash Cow | High market share, mature market, strong net interest margins, significant cash flow. | Net profit after tax AUD 103.2 million (FY2024) driven by mortgage origination. |
| Loan Servicing | Cash Cow | Steady, high-margin fees, minimal capital expenditure required. | Servicing Assets Under Management (AUM) reached $3.3 billion (CY2024). |
| Established NZ Mortgage Portfolio (HSBC Acquisition) | Cash Cow | Acquired a stable, mature portfolio in a slow-growing market. | Acquired Dec 2023, boosting AUM and providing predictable income. |
The BCG Matrix report you are currently previewing is the complete and final document you will receive immediately after your purchase. This means you'll get the fully formatted, analysis-ready file without any watermarks or demo content, ensuring it's ready for immediate strategic application.
Within the broader asset finance market, which showed signs of stabilizing in the latter half of 2024, some older, less dynamic sub-segments continued to struggle. These legacy areas saw a significant 13% drop in new business for the entirety of 2024.
These underperforming segments often suffer from a low presence in their respective markets and minimal growth, meaning they consume valuable capital but don't deliver strong returns. This makes them prime candidates for a thorough review, potentially leading to their sale to free up resources for more promising ventures.
Niche commercial loan products with low demand represent offerings that see very few new applications and have minimal market penetration. These might include specialized financing for very specific industries or unique asset types that appeal to a tiny borrower segment.
For instance, a bank might offer a loan product specifically for vintage aircraft restoration, which, while potentially profitable per deal, garners very few origination requests annually. In 2024, such niche products often struggle to justify the compliance and servicing costs, especially if they represent less than 0.5% of a financial institution's total commercial loan portfolio origination volume.
Within Pepper Money's diverse portfolio, certain asset finance products have unfortunately landed in the "Dogs" category of the BCG Matrix. These are the segments showing elevated late-stage arrears, meaning a growing number of borrowers are significantly behind on their payments. This trend directly translates to higher loan loss expenses, as the likelihood of recovering the full loan amount diminishes.
These underperforming assets are a drain on resources. For instance, in the first half of 2024, Pepper Money reported a statutory loss after tax of $23.7 million, partly influenced by increased provisions for credit losses. Products with high arrears demand more attention from collections teams and risk management, consuming valuable operational capacity without generating commensurate returns.
The combination of low profitability and elevated risk makes these products prime candidates for strategic review. Pepper Money, like many financial institutions, must carefully consider whether to reduce exposure to these segments or even discontinue them altogether. This strategic pruning allows the company to reallocate resources towards more promising growth areas, ultimately strengthening its overall financial health.
Older product lines that haven't been updated or integrated with digital technology may find it difficult to keep up in today's lending market. Without modern features or smooth digital processes, their market share could be shrinking.
These products can hinder innovation and efficiency across the entire portfolio. For example, in 2024, a significant portion of legacy mortgage products, which often lack robust online application portals, saw a 5% year-over-year decline in new originations compared to digitally-enhanced offerings.
Small, non-strategic loan portfolios often fall into the 'dogs' category of the BCG Matrix. These are typically segments that don't represent a significant portion of a financial institution's assets under management (AUM) or contribute meaningfully to overall profitability. For instance, a bank might hold a portfolio of niche agricultural loans that, while profitable on a per-loan basis, are too small to impact the institution's bottom line significantly and have limited potential for expansion.
These portfolios might be legacies of previous business lines or highly specialized offerings with low market growth. Consider a situation where a financial firm acquired a smaller entity with a unique, but now outdated, lending product. In 2024, such a portfolio might represent less than 0.5% of total loan origination for larger institutions, with projected annual growth rates below 2%.
Dogs in the BCG Matrix represent business units or products with low market share and low growth potential. For financial institutions, these are often legacy products or niche offerings that consume resources without generating substantial returns. In 2024, segments with declining market share and operational inefficiencies, like older mortgage products lacking digital portals, saw a 5% year-over-year drop in new originations.
These segments are characterized by high arrears and increased loan loss expenses, impacting profitability. For instance, Pepper Money's first half of 2024 results showed a statutory loss influenced by higher credit loss provisions, partly due to such underperforming assets.
The strategic implication for these 'dog' products is a need for careful review, potentially leading to divestment or discontinuation to reallocate capital to more promising growth areas.
Financial institutions must address these 'dog' segments to improve overall portfolio health.
| BCG Category | Market Share | Market Growth | Example in Finance | 2024 Trend Impact |
| Dogs | Low | Low | Niche commercial loans with low demand, legacy digital products | 13% drop in new business for struggling legacy segments; 5% decline in originations for non-digitalized mortgages. |
| Stars | High | High | Digital-first lending platforms, innovative fintech solutions | Continued strong growth, though competition intensified. |
| Cash Cows | High | Low | Established, stable mortgage products with strong brand recognition | Steady, predictable income streams, but growth limited. |
| Question Marks | Low | High | Emerging markets, new digital payment solutions | High investment required, uncertain future returns. |
Pepper Money's new digital lending platform initiatives represent a strategic move into the Stars quadrant of the BCG Matrix. These innovations are designed to empower brokers with advanced tools and significantly improve the customer journey, tapping into a high-growth potential market. By enhancing efficiency and accessibility, Pepper Money aims to capture a larger share of the evolving digital lending landscape.
While the growth potential is considerable, the current market share of these digital platforms remains nascent, reflecting an ongoing adoption phase. For instance, the overall digital mortgage market in Australia, while growing rapidly, still sees traditional channels dominating, though this is expected to shift. Pepper Money's investment here is crucial for scaling these operations and establishing a strong foothold as digital adoption accelerates.
Pepper Money's recently expanded homeowner loan options, featuring no and low early repayment charges (ERCs) introduced in July 2025, represent a strategic move to capture a segment prioritizing flexibility. This expansion directly addresses a growing consumer demand for adaptable mortgage solutions, a trend observed across the broader lending market.
While these new offerings are positioned to tap into a burgeoning market need, their current market share remains modest due to their recent introduction. The success of these ERC-friendly products hinges on Pepper Money's ability to rapidly gain traction and maintain a competitive edge against established players in the homeowner loan space.
Expanding Pepper Money into new geographic markets, such as Southeast Asia or parts of Europe, would position these ventures as question marks within the BCG matrix. These markets, while offering significant long-term growth potential, would start with a minimal existing market share for Pepper Money.
Initiating operations in these new territories in 2024 would necessitate considerable initial investment in market research, regulatory compliance, and establishing local operations. For instance, entering a market like Vietnam, with its projected GDP growth of 6.5% in 2024 according to the World Bank, presents an attractive opportunity but also carries the inherent risk of unproven market acceptance and competitive responses.
Pepper Money's strategic approach involves identifying and filling gaps in the financial market with innovative products. This proactive strategy positions them to capitalize on emerging opportunities, particularly in niche sectors.
Forming strategic partnerships for these emerging niche markets aligns perfectly with Pepper's strategy. These collaborations are designed to address highly specific needs, such as specialized commercial finance or unique consumer lending segments, which currently represent low market share but possess significant growth potential.
Pilot products, often the initial ventures into uncharted market territories, represent a critical phase for identifying and nurturing future growth engines. These offerings are specifically engineered to address unmet customer needs or gaps left by existing solutions, aiming to carve out unique market positions.
The CEO’s mention of an extensive product rollout underscores a strategic initiative to innovate and capture emerging opportunities. These pilot products, by their very nature, begin with negligible market share but hold the potential for significant expansion if they resonate with the target audience and prove their value proposition.
For instance, in 2024, many tech companies have launched beta programs for AI-powered productivity tools, targeting specific professional workflows that were previously inefficient. Early adoption rates and user feedback from these pilots are crucial in determining which products warrant further investment and development to transition into the ‘Star’ category within the BCG Matrix.
Question Marks in Pepper Money's portfolio represent new ventures or products in nascent markets with high growth potential but currently low market share. These are strategic investments, requiring significant capital infusion to gain traction and potentially become future Stars.
The key challenge for Question Marks is converting potential into performance. Success hinges on effective market penetration strategies and adapting to evolving consumer needs. For example, Pepper Money's expansion into new geographic regions in 2024, like Southeast Asia, falls into this category, demanding substantial upfront investment for market research and operational setup.
The success of these ventures is not guaranteed, and a careful analysis of market dynamics and competitive landscapes is crucial. For instance, while Vietnam's projected GDP growth of 6.5% in 2024 is attractive, unproven market acceptance and competitive responses pose significant risks for new entrants.


