
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
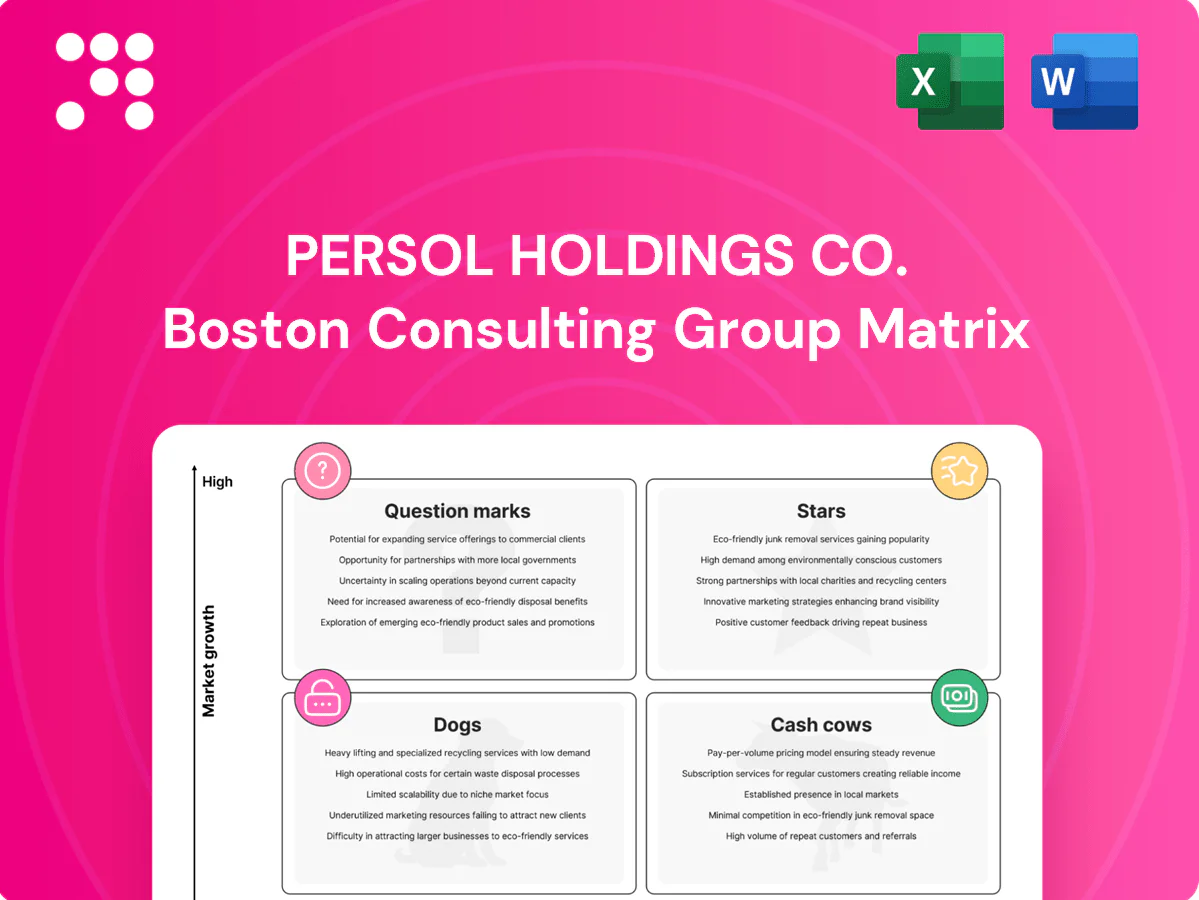
Quick snapshot: Persol Holdings’ BCG Matrix shows where services and staffing units sit today — a mix of steady cash cows and a few promising question marks that could become stars with the right moves. Want the full quadrant breakdown, data-backed recommendations, and slide-ready visuals? Purchase the complete BCG Matrix for a Word report plus an Excel summary and start reallocating capital with confidence.
High growth demand for cloud, data and cybersecurity talent in Japan aligns with Persol’s deep bench of tech recruiters, driving higher fill rates and upward pressure on bill rates. Clients are scrambling for skills across cloud migration, analytics and security, so recruiter enablement and brand investment are key to defend and grow share. Holding position as market cools would transition this business into a Cash Cow for Persol.
Large APAC accounts are consolidating vendors and Persol, with group revenue around 1.1 trillion JPY (FY2024), is regularly on shortlists; RPO/MSP program scale and embedded teams drive sticky revenue through deep data visibility. Backlog and bookings in APAC RPO/MSP rose ~18% in 2024, but sustaining momentum requires continued investment in delivery tooling and client success. With win rates remaining above 60%, the segment is shaping into a durable margin engine.
Engineering & life-science placements at Persol command specialist roles with scarce talent and premium fees, supporting higher ARPU; Persol Holdings reported about 1.1 trillion yen consolidated revenue in FY2024, highlighting scale. Growth tails stem from semiconductor, EV and medtech projects with sustained hiring cycles. Protect through niche talent communities and faster time-to-shortlist and keep reinvesting to compound category leadership.
Onsite solutions (VMS-integrated) are Persol Holdings' star offering: as of 2024 Persol runs high-share, expanding workforce programs on client sites, with VMS integration locking in workflow and visibility across supply chains. This model demands continuous process redesign and rising analytics spend to sustain margins. Strategy: scale now, harvest later as client switching costs increase.
Career transition for enterprise clients sits as a Star for Persol in the current BCG view: corporate restructuring cycles are active across Japan and APAC amid tight labor markets (Japan unemployment ~2.5% in 2024), Persol’s brand and 3,000+ counselor network give it lead status, and elevated growth requires accelerating digital coaching and redeployment pathways; if cycles stabilize, it will transition to Cash Cow.
Persol’s Stars: cloud/data/cyber, APAC RPO/MSP, engineering/life-science and onsite VMS programs drive premium fill rates and ARPU amid 2024 demand; group revenue ~1.1 trillion JPY (FY2024) supports scale. APAC RPO/MSP bookings +18% in 2024 with win rates >60%; Japan unemployment ~2.5% sustains career-transition demand. Invest in recruiters, tooling and analytics to secure cash-cow transition.
| Metric | 2024 |
|---|---|
| Group revenue | ~1.1 trillion JPY |
| APAC RPO/MSP growth | +18% |
| Win rate | >60% |
| Japan unemployment | ~2.5% |
 Detailed Word Document
In-depth BCG review of Persol Holdings' units, highlighting Stars, Cash Cows, Question Marks and Dogs with investment guidance and trend context.

 Customizable Excel Spreadsheet
One-page BCG matrix placing Persol business units in quadrants to simplify portfolio decisions and cut meeting time.
Domestic clerical/office temp staffing is a mature, high-share segment for Persol that delivered approximately ¥300bn in revenue in 2024, with utilization near 92% and repeat clients driving stable demand. Growth is low but steady—vacancy days were reduced ~15% YoY and operating margins held around 7% in 2024. Focus: optimize mix, minimize vacancies, streamline compliance and milk cash while automating back-office further.
Accounting, sales, HR show stable hiring with solid placement fees (industry standard 15–25% of first‑year salary) and limited expansion appetite.
Strong Persol brand keeps inbound candidate and client flow efficient, lowering acquisition cost and time‑to‑fill.
Priority is consultant productivity and referral loops; maintain services and resist overspending on broad promotion.
Payroll and HR outsourcing at Persol is a classic cash engine with sticky contracts, reported recurring revenue share of about 18% of group sales in 2024 and client churn under 5%, delivering steady cashflow. Growth is modest (around 3–5% annually), while operating margins improved to roughly 12% in 2024 as scale reduced unit costs. Investing in tooling and SLA automation can widen spreads further. Surplus cash is being allocated to higher-growth bets within the portfolio.
SMB temp-dispatch networks in Japan deliver repeat orders via longstanding local relationships; Persol Group reported consolidated revenue ~¥1.1 trillion in FY2023, with the domestic staffing market (~¥2.2 trillion in 2023) largely flat but Persol’s share entrenched. Centralizing sourcing and routing orders digitally can trim cost-to-serve and protect margins, providing stable cash to support the wider portfolio.
Bundled with Persol Holdings core staffing and placement, training and assessment add-ons deliver steady, high-margin revenue: the global corporate training market was about 420 billion USD in 2024, and standardized digital programs often achieve 40–60% gross margins. These upsells are not hyper-growth but provide dependable, low-cost drip revenue when content and delivery are productized and scaled.
Persol cash cows: domestic clerical (~¥300bn revenue 2024, utilization ~92%, low growth), payroll/HRO (recurring, ~18% group sales, ~12% margin, churn <5%), training & upsells (productized, 40–60% margins, global market ~$420bn 2024); scale and digital routing protect margins and fund growth bets.
| Segment | Revenue | Margin | Growth | Note |
|---|---|---|---|---|
| Domestic clerical | ¥300bn (2024) | ~7% | Low | Util ~92% |
| Payroll/HRO | 18% group sales | ~12% | 3–5% | Churn <5% |
| Training | — | 40–60% | Modest | Market ~$420bn (2024) |
The file you're previewing is the exact Persol Holdings Co. BCG Matrix you'll receive after purchase. No watermarks, no demo content—just the fully formatted, analysis-ready report built for strategic clarity. Once bought, the full document is immediately downloadable and editable for presentations or planning. No surprises—just a professional, market-informed tool you can use right away.
Legacy print job listings are a low-growth Dogs segment as audiences have largely migrated to online platforms, eroding print reach and monetization; revenue per listing has fallen and margins are weak. Cash remains tied up in printing and distribution with limited return, so Persol should sunset print offerings and migrate remaining clients to digital channels. Avoid further turnaround spend on print infrastructure and reallocate budget to digital acquisition and platform upgrades.
Subscale overseas niches in Persol Holdings (TSE:2181) show tiny share and commoditized rates, making them hard to defend. Margins erode with overhead so these pockets often only break even. Recommend exit or consolidate into regional hubs to cut cost and complexity. Freeing management bandwidth redirects resources to scalable domestic and high-margin segments.
Dogs: retail/hospitality short-shift dispatch faces high churn (often >60% annually) and low unit economics with industry operating margins below 5% in 2024; volatile schedules push coordination costs that can erode gross margin by double-digit percentage points. Prune geographies lacking density and automate retained routes (scheduling, matching) to cut coordination spend. Do not chase volume for volume’s sake; focus density and profitability.
Non-core facilities temp pools show fragmented clients, high compliance burden and limited differentiation, delivering low margin and little cross-sell; Persol’s group revenue was about ¥1.27 trillion in FY2024 but temp-facility verticals underperform versus core staffing segments. Stop incremental fixes: divest or outsource under partner brands to cut compliance costs and redeploy capital to higher-growth lines.
Standalone career fairs (offline-heavy) are Dogs for Persol Holdings: attendance has fallen about 28% YoY in 2024 and sponsor ROI has drifted down roughly 35%, while digital alternatives in 2024 show ~60% lower cost per attendee and ~3x reach versus physical events. Fold useful in-person elements into virtual formats, retire the rest, and keep costs off the books.
Dogs: legacy print, niche overseas, retail/hospitality dispatch, non-core temp facilities and offline career fairs drain cash with low margins; Persol group revenue was ¥1.27 trillion in FY2024 yet these segments underperform. Recommend divest/exit, consolidate or digitize; reallocate CAPEX to digital acquisition and high-margin staffing. Do not pursue volume-led fixes.
| Metric | 2024 |
|---|---|
| Group revenue | ¥1.27T |
| Retail/hospitality churn | >60% |
| Operating margin (segments) | <5% |
| Career fair attendance YoY | -28% |
| Sponsor ROI | -35% |
| Digital cost per attendee | ≈-60% |
| Digital reach vs physical | ≈3x |
HR tech matching platform sits in a high-growth category—global HR tech market ~US$33B in 2024 with ~10% CAGR—but Persol’s share remains limited versus pure-play apps. The business consumes cash for product development and customer acquisition, driving elevated CAC and burn. Strategy: double down where Persol owns supply or form partnerships if CAC stays high. With clear unit economics it can flip to a Star.
The freelance/gig marketplace is a Question Mark for Persol: global platform demand grew ~12% YoY in 2024 as buyers pilot models while regulation tightens, yet Persol holds low share amid fierce competition from Upwork/Fiverr and regional players. Persol should invest to scale fast and target white-collar niches aligned with its corporate client base (IT, finance, HR) or exit quickly; without rapid scale it risks sliding to Dog.
Demand for regional talent flow in APAC is rising—the region holds roughly 60% of the world’s population—yet Persol’s cross-border operations remain early-stage. Regulatory complexity and relocation friction, especially visa and tax hurdles across Japan, SEA and Australia, slow ramp. Focus on building trusted pipelines in a few high-potential corridors first. If placement velocity improves, this business line can scale rapidly.
Skills training is booming globally; in 2024 corporate learning spend topped an estimated $400B, yet Persol’s digital share remains nascent, requiring rapid capability build or partners.
Content quality and completion rates drive outcomes and margins; pilot with anchor clients and tie programs to hiring guarantees to prove ROI.
Sector-specific RPO for startups/scaleups sits as a Question Mark: venture markets rebounded in 2024 with deal value spikes (PitchBook reported ~35% YoY growth in US VC value in 2024), but Persol’s share remains low amid choppy cycles. Offer modular, lower-cost RPO bundles to land logos; if win rates rise and retention strengthens, the unit can graduate to Star status.
Persol Question Marks: HR tech (~US$33B 2024, ~10% CAGR) and gig platforms (+12% YoY 2024) show demand but low Persol share; APAC cross-border (60% world pop) and digital training (corporate spend ~US$400B 2024) need scale/partners; RPO for startups tied to VC rebound (~+35% US VC value 2024)—invest selectively, pilot-to-scale or exit.
| Business | 2024 Signal | Action | Trigger |
|---|---|---|---|
| HR tech | US$33B; ~10% CAGR | Double down/partner | Positive unit economics |
| Gig marketplace | +12% YoY | Scale niches or exit | Rapid share gains |
| APAC cross-border | APAC ≈60% pop | Focus corridors | Higher placement velocity |
| Skills training | US$400B corporate spend | Pilot hire-guarantees | Completion→hiring ROI |
| Startup RPO | US VC +35% | Modular low-cost offers | Rising win/retention |


