
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
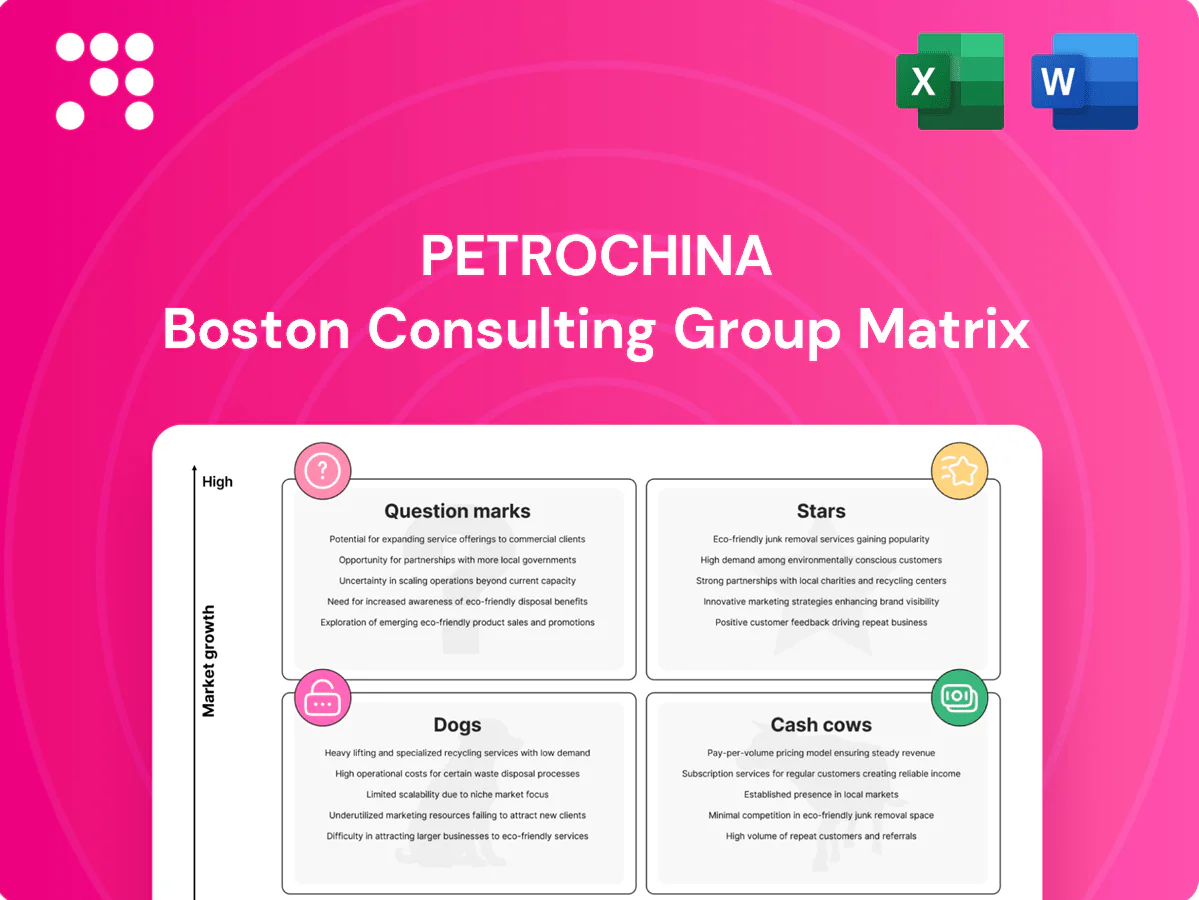
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Look under the hood of PetroChina with our concise BCG Matrix: see which business lines are Stars, which generate steady cash, which lag, and which need a rethink. This preview maps the rough landscape—buy the full BCG Matrix for quadrant-by-quadrant placements, data-backed recommendations, and strategic moves tailored to PetroChina’s market reality. Purchase now for a ready-to-use Word report plus an editable Excel summary you can present and act on immediately.
China’s gas demand kept climbing, reaching about 350 bcm in 2024, and PetroChina controls the country’s largest pipeline network and roughly 40% of wholesale gas supplies, creating a durable infrastructure moat. High market share plus policy support for gas substitution make this a BCG Stars asset, yet PetroChina still required heavy capex (around RMB 250bn in 2024) to expand capacity and de‑bottleneck. Keep feeding investment now to capture scale benefits as the market matures; expect it to transition to Cash Cow as utilization and pricing stabilize.
Unconventional gas in Sichuan and Ordos expanded rapidly in 2024, with regional volumes rising over 15% year‑on‑year and PetroChina holding prime acreage and leading technical depth. The business is capital‑hungry—drilling, fracs and learning curves drove incremental capex in the hundreds of millions RMB this year—but the growth runway remains real. Reported cost per well is trending down roughly 20% as EURs and volumes scale; stay invested to lock in share before growth tapers.
Securing contracted LNG plus flexible spot volumes gives PetroChina leverage in a still-expanding market, smoothing supply-cost exposure. Regas terminals and storage add system value and optionality, enabling seasonal arbitrage and reliable offtake for downstream customers. The model is cash intensive—ships, terminals and working capital—but it anchors long-term gas sales and scaling now supports durable margins later.
Integrated petrochem value chains (aromatics, olefins) are Stars for PetroChina: downstream chemicals fed by captive naphtha and LPG grow faster than fuels in domestic demand centers, and integration reduces feedstock risk while boosting plant utilization and margins. Cycles remain volatile, yet PetroChina’s share in advantaged clusters is high and management continues to expand where site economics win.
Digitalized marketing and industrial gas solutions are Stars for PetroChina in 2024 as data-led pricing, bundled energy services and city-gas growth (urban gas penetration >70% in China, 2024) are taking share in a market still opening up; PetroChina’s vast customer base and pipeline network give it a running start.
Ongoing investment in digital platforms and customer operations is required; when executed well, these initiatives compound into a defensible lead and support premium pricing and higher industrial gas margins.
Stars: core gas network (350 bcm market 2024; ~40% wholesale) plus unconventional (+15% regional growth 2024) and digital city‑gas (>70% urban penetration 2024) require heavy capex (RMB250bn 2024) but secure scale, margins and transition to Cash Cow as utilization and costs (per‑well down ~20%) improve.
| Metric | 2024 |
|---|---|
| China gas demand | 350 bcm |
| PetroChina market share | ~40% |
| Capex | RMB 250bn |
| Unconventional growth | +15% YoY |
| Urban gas penetration | >70% |
| Cost/well | -20% |
 Detailed Word Document
Concise BCG review of PetroChina: Stars, Cash Cows, Question Marks, Dogs with investment, hold, divest guidance and trend context.

 Customizable Excel Spreadsheet
One-page PetroChina BCG Matrix mapping business units to quadrants to highlight priorities and remove decision friction.
Refining (large, coastal & integrated sites) sits in a mature market with big share and typically runs at >90% utilization, spinning off steady cash when crude and product slates are optimized. Capex has shifted toward efficiency and emissions upgrades rather than step-out growth, with maintenance/upgrade spending now dominating investment profiles. Reliability and energy-intensity gains drop straight to operating cash flow, supporting steady margins; avoid overbuild to preserve ROIC.
Mature conventional oilfields are declining but predictable, with operating costs tamed by decades of know-how; PetroChina’s legacy upstream generated stable free cash flow, funding capex. Low growth but high domestic share makes them classic cash generators, with incremental EOR and strict opex discipline extending the tail. Surplus cash is being redirected to gas-led investment and renewables transition.
Retail fuels network (core corridors) delivers stable volumes through entrenched locations—PetroChina operated roughly 20,000 service stations across China in 2024, underpinning predictable throughput. Pricing discipline on fuels plus convenience retail (non-fuel gross margins near 30%) boosts site-level margin, so the segment is cash generative rather than high growth. Modest capital for site upgrades and expanded non-fuel sales preserves cash flow, enabling harvest strategies without degrading customer experience.
Pipeline transportation tariffs are regulated, creating tariff-driven, utility-like cash flows; PetroChina reported pipeline utilization near 90% in 2024, yielding steady throughput and muted top-line growth but a durable revenue base. Targeted efficiency upgrades and loss reductions in 2024 lifted segment margins with low incremental risk. The segment reliably funds corporate overhead and debt service.
When integrated with refining, base commodity chemicals can deliver steady cash in mature demand; integrated margins typically outpace standalone chemical units through feedstock arbitrage and product uplift. Debottlenecking projects in 2024 showed higher IRRs than greenfield builds, cutting lead times and capital intensity. Operational focus on yield, energy efficiency, and byproduct valorization preserves margins—let scale do the rest.
Refining & coastal complexes >90% utilization (2024) generate steady cash; legacy upstream provides predictable FCF with EOR extending decline; retail network (~20,000 stations in 2024) secures volumes and ~30% non-fuel margins; pipelines (utilization ~90% in 2024) yield tariff-stable revenue funding capex and debt service.
| Segment | 2024 metric | Role |
|---|---|---|
| Refining | Utilization >90% | Primary cash generator |
| Upstream | Stable FCF, declining | Harvest/FCF |
| Retail | ~20,000 stations; non-fuel ~30% GM | Predictable cash |
| Pipelines | Utilization ~90% | Tariff-stable revenue |
The file you're previewing is the exact PetroChina BCG Matrix report you'll receive after purchase. No watermarks or demo placeholders—just a fully formatted, editable document built for strategic clarity. Delivered immediately to your inbox, it's ready for printing, presenting, or tweaking for board-ready analysis. Buy once and get the professional, market-informed BCG Matrix that's ready to plug straight into your planning.
High-cost overseas upstream barrels are small, remote or politically complex assets whose elevated lifting costs drag PetroChina's returns and tie up capital and management attention without real growth. Turnarounds are costly and uncertain, often with long payback horizons. These assets are prime candidates for divestment or managed wind-down to redeploy capital to higher-return opportunities.
Subscale urban fuel stations in PetroChina’s portfolio show low throughput and brutal competition; PetroChina operated roughly 30,000 retail sites by 2023 while China had about 130,000 stations nationwide, compressing volumes per site and pricing power. Even with brand strength, retail fuel margins (often only a few jiao per liter) leave economics barely above breakeven. Site closures or consolidation typically yield better ROIC than costly rehab. Free the capital for higher-return upstream or convenience formats.
Coal-to-chemicals is highly carbon-intensive and faces growing policy headwinds as China pursues carbon peak before 2030 and carbon neutrality by 2060; regulators tightened approvals in 2024. Unit economics are often subpar, with high feedstock and CO2 compliance costs leaving projects margin‑squeezed. Environmental liabilities add contingent risk to balance sheets. Better strategic exit than chasing marginal fixes.
Non-integrated commodity lines with non-captive feedstock and small plants suffer margin cyclicality; 2024 examples show plants under 150 ktpa and EBITDA margins around 3–6% versus integrated peers at 15–20%, while market share remains low and switching costs are nil. Maintaining them absorbs opex and capital, often USD 50–100m annually; sell or shutter and redirect feedstock and volumes to integrated sites to restore margin resilience.
Workshops, minor logistics and side businesses at PetroChina act as Dogs in the BCG matrix: low growth, low share activities that at best break even and often distract management from core upstream/downstream value-chain priorities.
Recommend outsourcing or monetizing these assets; industry studies in 2024 show non-core service units typically contribute under 3% of group EBITDA and dilute ROIC, so redeploy capital to core energy segments.
High-cost overseas upstream, subscale retail sites (PetroChina ~30,000 vs China ~130,000 in 2023), coal-to-chemicals under 2024 approval tightening, and small non-integrated plants ( <150 ktpa; EBITDA 3–6% vs integrated 15–20%) are Dogs—low share, low growth; non-core services <3% group EBITDA; recommend divest/outsource to redeploy capital.
| Asset | Metric | 2023/24 |
|---|---|---|
| Retail sites | Share | 30,000 / 130,000 |
| Non-integrated plants | EBITDA | 3–6% |
| Non-core services | Group EBITDA | <3% |
Policy buzz is strong—China's 14th Five-Year Plan and carbon neutrality by 2060 drive hydrogen focus—but infrastructure and end-demand remain nascent. PetroChina's network of around 30,000 service sites, plus power and logistics, offers an edge if the market inflects. Realizing scale will need heavy capex and partnerships; prioritize selective bets near industrial clusters where demand and off-take are likeliest.
Gas stations are ideal nodes for EV charging but utilization and viable business models vary by city; China had about 2.34 million public charging points by end‑2023, highlighting uneven density. The right mix of DC fast charging, food and services can scale unit economics and lift convenience retail spend per visit. Early units will consume cash as demand patterns settle; pilot fast, standardize designs and roll where throughput and payback exceed thresholds.
CCUS at refineries and gas fields rates as a Question Mark for PetroChina: strong strategic fit with large point sources and nearby depleted reservoirs, but economics hinge on regulation and carbon pricing. Capture costs remain chunky at roughly $40–120/tCO2 and technical capture up to ~90% is proven; global operational capacity was ~40 MtCO2/yr in 2023, so stage-gate investments should wait for policy clarity.
Advanced materials and specialty chemicals are question marks for PetroChina: margins rise moving up the value chain but require R&D, customer intimacy, and patience; current portfolio share is small (estimated ~2–4% of 2024 revenue) while China specialty-chemicals demand grew ~6% in 2024, showing real optionality. Wins come from focused niches, not breadth, and incubation should target feedstock-advantaged sites.
International LNG marketing and trading sits as a Question Mark for PetroChina: 2024 saw China remain the world’s largest LNG importer, so global trading can scale beyond securing domestic supply, but the segment is intensely competitive and risk-heavy; current book share is small and carries a steep learning curve.
Question Marks (hydrogen, EV charging, CCUS, specialty chemicals, LNG trading) need selective capex, pilots and partnerships; PetroChina’s 30,000 service sites and logistics give optionality but cash burn is likely until demand and policy firm. Prioritize industrial clusters, feedstock-advantaged sites and stage-gate CCUS pending carbon pricing clarity.
| Segment | 2024/2023 metric | Priority |
|---|---|---|
| Hydrogen | policy push 14th FYP | pilots near clusters |
| EV charging | 2.34M points end‑2023 | pilot fast chargers |
| CCUS | $40–120/tCO2; 40Mt/yr (2023) | stage‑gate |
| Specialty chemicals | ~2–4% rev; demand +6% (2024) | niche scale |
| LNG trading | China largest importer (2024) | build traders, controls |


