
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
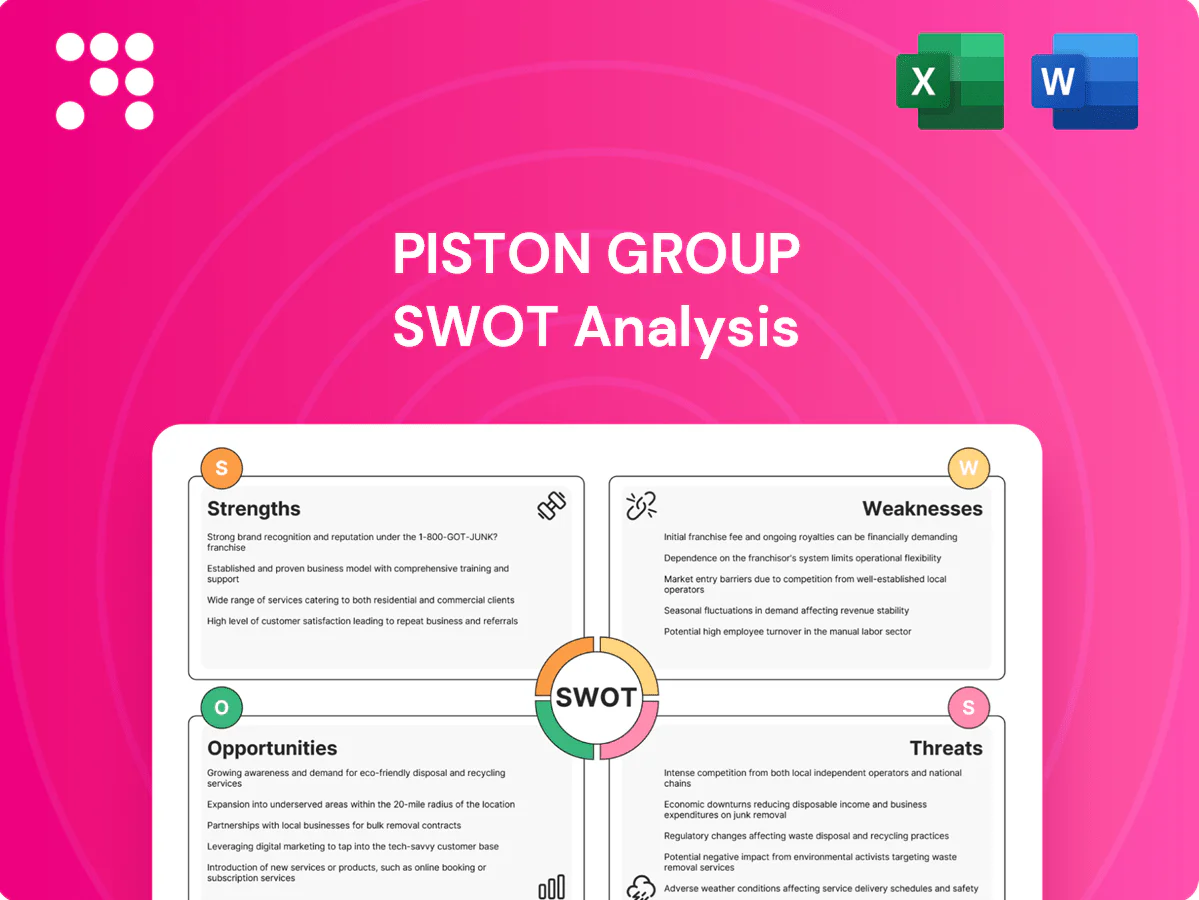
Piston Group’s SWOT snapshot reveals key strengths, vulnerabilities, market opportunities, and competitive threats to inform smarter decisions. Ready for deeper, research-backed insights? Purchase the full SWOT report—editable Word and Excel deliverables included to support strategy, pitching, and investment planning.
Piston Group’s integrated design-to-assembly model minimizes handoffs and accelerates launch timing, enabling faster NPI—concurrent engineering with OEMs can cut development cycles by up to 30% and Piston reports faster module launches versus industry peers. Vertical integration strengthens cost control and quality traceability, positioning the group as a preferred partner for complex modules and rapid problem resolution.
Diverse product and systems portfolio across powertrain, interior and chassis smooths demand swings and reduced cyclicality; top 100 suppliers still capture roughly 70% of OEM content in 2024, benefiting scaled suppliers. Cross-domain expertise enables systems-level optimization and value engineering, raising margins. Breadth increases share-of-wallet with key OEMs and creates cross-selling in platform programs.
Piston Group's deep ties with major automakers underpin stable, multi-year revenue streams by securing program commitments early in vehicle development. Early involvement in vehicle programs locks in design-in positions and reduces aftermarket competition. Proven on-time, quality launch performance strengthens renewal odds, while strong referenceability with top OEMs accelerates wins on new platforms.
Robust APQP/PPAP and lean practices drive defect rates toward Six Sigma benchmarks (3.4 DPMO), cutting scrap and rework. Consistent delivery performance (>98% on-time) preserves OEM production uptime and reduces penalty exposure. Data-driven continuous improvement has driven conversion-cost reductions of roughly 10–20% in comparable supplier programs, and a strong quality reputation wins competitive sourcing awards.
Modular lines and adaptable tooling let Piston Group shift mix and volume rapidly, supporting just-in-time delivery and minimizing changeover time.
Facilities located near OEM plants reduce inbound logistics risk and costs while enabling rapid response to platform changes and launch cadence.
Footprint flexibility allows efficient localization for new platforms, shortening lead times and supporting OEM capacity swings.
Piston Group’s integrated, vertically aligned model shortens NPI by up to 30%, sustains >98% on-time delivery and 3.4 DPMO, delivers 10–20% CI conversion-cost savings, and secures durable OEM program share amid 2024 industry concentration (top 100 suppliers ≈70% OEM content).
| Metric | Value |
|---|---|
| NPI cycle reduction | up to 30% |
| On-time delivery | >98% |
| Quality (DPMO) | 3.4 |
| CI savings | 10–20% |
| 2024 OEM concentration | Top 100 ≈70% |
 Detailed Word Document
Provides a clear SWOT framework analyzing Piston Group’s internal capabilities, market strengths, growth opportunities, operational weaknesses, and external threats shaping its competitive position.

 Customizable Excel Spreadsheet
Provides a concise, editable SWOT matrix for Piston Group that streamlines stakeholder alignment and enables rapid strategic decisions; ideal for quick updates and easy integration into reports and presentations.
Dependence on a few OEMs heightens revenue volatility: for many tier-1 suppliers the top three customers account for over 60% of sales, leaving Piston Group exposed to demand swings. Loss or delay of a single platform can materially cut utilization and margins, with single-program shortfalls often reducing capacity use by 20–40%. Pricing leverage skews toward large buyers, and diversification across customers and regions remains a priority.
Equipment, tooling and launch investments exert steady pressure on free cash flow, with initial capex often concentrated in the first 12–36 months. Payback depends on sustained production volumes and stable programs, raising risk if orders slip. Higher interest rates (federal funds ~5.25–5.50% mid-2025) raise financing costs for capex. Large, heavy assets reduce agility and increase fixed-cost burdens during downturns.
Piston Group's production volumes closely track macro auto demand and OEM schedules, with industry production swings of roughly 20-30% across cycles driving large revenue variability. Sudden downturns make inventory and labour balancing difficult, causing overtime or layoffs and higher per-unit costs. High fixed costs magnify margin swings; forecast errors force costly expediting or risk of parts obsolescence.
ICE-heavy legacy mix leaves Piston Group exposed as EVs reached about 14% of global new car sales in 2024 and global electric car stock was ~26 million at end-2023 (IEA), implying secular decline in ICE content; shifting engineering into EV systems and software requires capital and skills investment, while some legacy lines risk underutilization and margin erosion if the portfolio shift is mistimed.
Concentration with top OEMs (>60% sales) creates high revenue volatility and pricing pressure; single-program shortfalls can cut utilization 20–40%. Heavy capex/tooling (payback 12–36 months) and federal funds ~5.25–5.50% (mid-2025) squeeze free cash flow. ICE-heavy mix risks margin erosion as EV share reached 14% in 2024 and global EV stock ~26M (end-2023).
| Metric | Value | Impact |
|---|---|---|
| Top-3 OEM share | >60% | Revenue concentration |
| Program shortfall | 20–40% utiliz. | Margin hit |
| Capex payback | 12–36 mo | Cash pressure |
| Fed funds | 5.25–5.50% (mid-2025) | Higher financing cost |
| EV share | 14% (2024) | ICE obsolescence risk |
| Global EV stock | ~26M (end-2023) | Secular shift |
This is the actual Piston Group SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report and reflects its structure, findings, and recommendations. Buy now to unlock the complete, editable version ready for immediate use.
Growing EV demand — global BEV+PHEV sales ~14 million in 2024 — expands TAM for battery, thermal and e‑drive assemblies, unlocking high-margin modules. Designing modular, lightweight systems targets multiple OEM platforms and can secure design wins across cohorts. Strategic partnerships with cell, inverter and thermal suppliers shorten time‑to‑market, and early program wins convert to sticky multi‑year revenues.
Robotics, machine vision and IoT analytics can raise yield and OEE substantially—industry reports show productivity gains commonly in the 10–30% range. Predictive maintenance has been shown to cut unplanned downtime by up to 50% and lower maintenance costs 10–40%. Digital twins accelerate launch validation and changeovers, often reducing time-to-market 20–30%. Automation also lowers exposure to labor-availability risk and wage inflation.
Piston Group’s precision-assembly capabilities map directly to aerospace, defense and industrials; earning AS9100 and ISO 13485 opens high-spec contracts. US defense procurement totaled about $858B in FY2024, while medical device and mobility markets (≈$600B range) can diversify margins and reduce auto-driven cyclicality.
Aftermarket kitting, sequencing and remanufacturing can add significant revenue per vehicle, tapping a global aftermarket estimated at about $415 billion in 2024 and higher-margin reman channels; bundled service contracts increase customer stickiness and can boost lifetime value. Data-enabled quality services differentiate bids and improve win rates, while aftermarket channels help smooth OEM production volatility and absorb demand swings.
EV demand (BEV+PHEV ~14M sales, 2024) and 26M global EVs expand TAM for batteries, thermal and e‑drive modules. Automation/digital twins can lift OEE 10–30% and cut downtime up to 50%, lowering costs and time‑to‑market ~20–30%. Defense ($858B FY2024) and medical (~$600B) diversify revenues. Aftermarket (~$415B, 2024) and M&A/JVs scale software (~$2k/vehicle by 2030).
| Metric | Value |
|---|---|
| EV sales 2024 | ~14M |
| Global EV stock | ~26M |
| Defense FY2024 | $858B |
| Aftermarket 2024 | $415B |
OEM platform shifts may outpace Piston Group rebalancing as electric vehicles reached about 14% of global car sales in 2023 (IEA) while major OEMs like Volkswagen target ~70% BEV mix in Europe by 2030, risking abrupt legacy volume drops, rapid tooling obsolescence from new battery/EV standards, and share loss to faster movers such as Tesla and BYD.
Price swings in steel (HRC volatility ~±20% in 2024), aluminum (~$2,300/ton LME) and copper (~$9,500–$10,500/ton in 2024–25) and resin markets (20–30% range moves) compress margins; invoice surcharges and index lags create timing mismatches. Energy cost spikes—recent gas/electric surges adding roughly 5–12% to conversion costs—exacerbate pressures, while hedging (typically covering 50–70% exposure) may not fully offset sharp moves.
Tariffs and export controls, exemplified by US Section 301 duties of up to 25% covering about 3,600 Chinese tariff lines, can materially alter Piston Group’s sourcing economics. Cross-border disruptions from port congestion and sanctions delay parts flow and have driven many OEMs to raise inventory buffers since 2020. Local content rules in markets like India and the EU complicate footprint planning. Sanctions risk, notably since 2022, threatens suppliers and key customers.
OEM cost-down targets of 3–5% annually eat into piston margins, while larger rivals leverage scale to lower sourcing and overhead per unit, squeezing mid-sized suppliers. New EV-component entrants intensify bidding, narrowing win rates; losing a rebid can strand dedicated tooling and require write-downs. Capital intensity and short bid cycles amplify cash strain and exit risk.
OEM EV shifts (14% global sales 2023; VW ~70% BEV Europe by 2030) risk rapid legacy volume loss and tooling obsolescence. Commodity swings (HRC ±20% 2024; copper $9.5–10.5k/t 2024–25) and energy spikes compress margins despite partial hedges. Tariffs (US duties up to 25%) plus OEM 3–5% cost-down targets and labor/automation gaps heighten cash and bid risk.
| Risk | Metric |
|---|---|
| EV adoption | 14% (2023), VW ~70% BEV EU by 2030 |
| Commodities | HRC ±20% (2024); Cu $9.5–10.5k/t (2024–25) |
| Tariffs | Up to 25% (US Section 301) |
| OEM pressure | 3–5% cost-down p.a. |


