
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
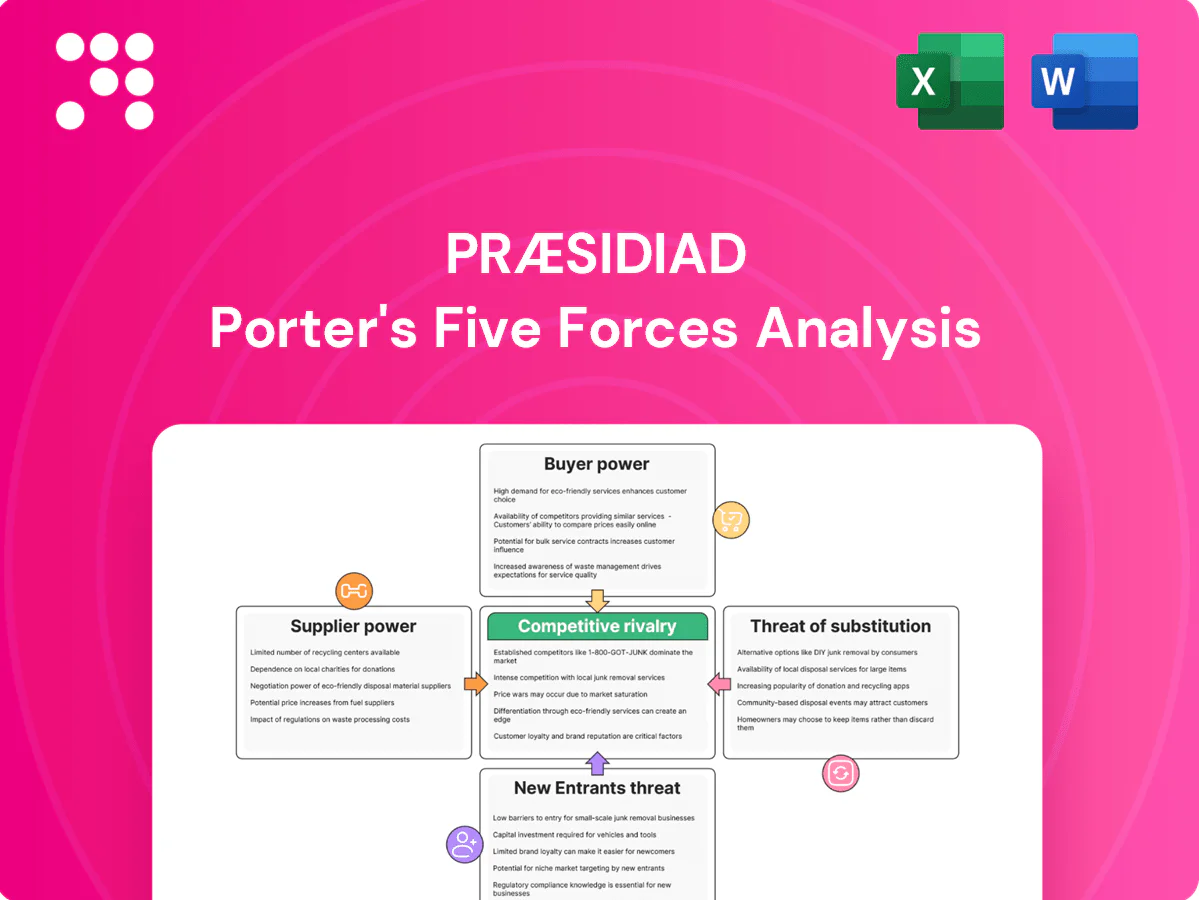
Præsidiad faces moderated buyer power and concentrated supplier pressure that constrain pricing and margins. Competitive rivalry is intense with differentiated incumbents and steady threat of niche entrants. Substitute technologies and regulatory shifts add asymmetric risks to growth. This brief snapshot only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore Præsidiad’s competitive dynamics, market pressures, and strategic advantages in detail.
Præsidiad depends on high-grade steel, galvanization and powder-coating from a concentrated set of mills and chemical firms, with supplier concentration exceeding 50% in key markets in 2024, raising switching costs and limiting pricing leverage. Long-term contracts and hedging programs reduce input-price volatility, but energy and geopolitical supply shocks have squeezed margins in recent years. Dual-sourcing and regional supplier footprints materially cut disruption risk.
Detection systems rely on niche OEM sensors, control boards and firmware, concentrating supplier power as certified components often require 3–12 months of validation. Global semiconductor lead times averaged about 12 weeks in 2024, while chip-price swings of up to 20% created cost pass-through stress. Long lead times and certification bottlenecks can delay projects; design-for-multi-vendor and standard interfaces reduce dependency and bargaining leverage.
Freight, hot-dip galvanizing capacity and skilled installation subcontractors drive supplier power; global container freight volatility remained elevated in 2024 with Drewry WCI averaging about $1,400 per 40ft equivalent, tightening margins. Local galvanizing bottlenecks and scarce installers can push input costs and premiums on expedited jobs. Project delivery windows increase vendor leverage; preferred supplier networks and staging inventory buffers reduce exposure to short-term spikes.
Compliance with security, safety and corrosion standards makes certifiers quasi-suppliers, able to impose requalification that has driven 6–12 month delays and incremental CAPEX of roughly $0.5–3.0M on similar industrial projects in 2024; changes in standards can force redesigns and trigger those costs, giving certifiers indirect leverage over timelines and spending. Proactive certification roadmaps reduce surprise burdens and shorten approval cycles.
Qualifying new steel grades, coatings or electronics typically requires 9–18 months of testing, audits and warranty contingencies in 2024, creating friction that deters rapid supplier switches and strengthens incumbent leverage. Praesidiad’s scale in 2024 enables framework agreements that reclaim supplier power by consolidating roughly 30% of procurement spend under long‑term terms. Modular design reductions in requalification scope have cut requalification touchpoints by about 20% in pilot programs, lowering future switching costs.
Supplier power is elevated: steel/chem supplier concentration >50% in key markets (2024) and qualification times of 9–18 months raise switching costs; framework agreements capture ~30% of spend, softening leverage. Niche sensor/semiconductor supply caused ~12-week lead times and ~20% chip-price swings in 2024, pressuring margins. Logistics, galvanizing and certifiers add episodic premium costs ($0.5–3.0M requalification) and timing risk.
| Metric | 2024 value |
|---|---|
| Steel/chemical supplier concentration | >50% |
| Qualification time | 9–18 months |
| Framework spend capture | ~30% |
| Semiconductor lead time | ~12 weeks |
| Chip-price volatility | ~20% |
| Drewry WCI freight | $1,400/40ft |
| Requalification CAPEX impact | $0.5–3.0M |
 Detailed Word Document
Comprehensive Porter's Five Forces analysis tailored to Præsidiad, uncovering competitive drivers, supplier and buyer power, threats from substitutes and new entrants, and strategic implications to protect market share and pricing; fully editable for investor decks, business plans, and internal strategy.

 Customizable Excel Spreadsheet
A concise one-sheet Porter's Five Forces summary with adjustable pressure levels and an instant radar chart—clean, no-macro layout ready to drop into pitch decks or integrate with broader reports for fast, boardroom-ready decision-making.
Large public and critical‑infrastructure buyers run competitive RFPs with strict specs; OECD data show public procurement averages about 12% of GDP, concentrating buying power in 2024. Their scale and procurement rigor compress vendor margins via multi‑year frameworks and price benchmarking, often forcing low single‑digit margin outcomes. Proven performance and compliance, however, can still earn measurable value premiums for suppliers.
Airport perimeters, rail corridors and industrial sites involve sizable orders often exceeding $1 million per contract, creating strong buyer leverage. As of 2024 buyers negotiate volume discounts commonly in the 5–15% range and extended multi-year warranties. Bundling gates, barriers and detection systems amplifies negotiating power on total-package pricing, while offering turnkey solutions helps Præsidiad defend margins through scope control.
Once a perimeter standard is adopted, switching requires redesign, regulatory approvals, and operational downtime, creating strong post-install stickiness that tempers buyer power. Pre-award, open specifications invite aggressive price competition among suppliers. Vendor-lock through multi-year lifecycle service and managed-security contracts further reduces churn and preserves margins.
Security buyers prioritize intrusion delay, detection accuracy and uptime over price, often demanding four nines (99.99%) SLA uptime and certifications such as ISO 27001, which reduces price elasticity where risk is high; documented KPIs and certifications weaken commoditization claims, while failures trigger penalty clauses and reimbursement pressure.
Buyers can solicit regional fabricators or integrators for fence lines and access kits; for lower-risk sites this widens choice and hardens price negotiations—2024 procurement surveys show regional sourcing can cut lead times 20–30% and costs 10–15%. For critical assets, typically 2–3 qualified vendors limit options and restore bargaining balance. Reference sites and manufacturer guarantees remain decisive tie-breakers.
Large public buyers (public procurement ~12% of GDP in 2024) and critical‑asset customers compress margins via competitive RFPs and multi‑year frameworks, but certified performance (ISO 27001, 99.99% SLA) supports price premiums.
Volume discounts typically 5–15%; regional sourcing can cut lead times 20–30% and costs 10–15%; critical sites usually shortlist 2–3 vendors, raising buyer power pre-award but creating post‑install stickiness.
| Metric | 2024 Value |
|---|---|
| Public procurement | ~12% GDP |
| Volume discounts | 5–15% |
| Regional savings | Lead time −20–30%, Cost −10–15% |
| Critical vendors | 2–3 |
This preview displays the exact Præsidiad Porter's Five Forces Analysis you'll receive after purchase—fully written, formatted, and ready to use. It includes in-depth evaluation of competitive threats, supplier and buyer power, entry barriers, and industry rivalry. No placeholders or samples; the full document is identical to this view and is available for instant download once you buy.
The market is split between multinational perimeter firms and strong regional fabricators, with the global perimeter security market valued at about USD 7.1 billion in 2024 and the top 10 players capturing roughly 45% of revenue.
Rivalry is fiercest in standard fencing—where product differentiation is thin and average industry EBIDTA margins compress below 12%—while high-security and integrated detection segments have fewer specialists, reducing pure price wars.
Geographic proximity and logistics efficiency are key battlegrounds, with firms reporting up to 30% faster lead times through regional hubs and nearshore production in 2024.
Wire mesh, posts and basic gates face intense price-driven rivalry, with low-cost overseas producers and imports exerting clear margin pressure in 2024; many US distributors reported single-digit gross margins on commoditized SKUs. Differentiation has migrated to coatings durability, delivery speed and service levels, while value engineering and SKU rationalization remain essential to protect profitability.
Combining physical barriers with sensors, analytics, and remote monitoring is a primary rivalry axis; integrated systems made up an estimated 60–70% of large enterprise security spend in 2024. Firms invest in interoperable platforms and AI-assisted detection, and VMS/PSIM partnerships can increase deal size by up to 30% and create account lock-in. Lagging on software reduces win rates in complex bids.
Aftermarket service, spares and upgrades generated roughly 30% of lifecycle revenue in 2024, creating recurring revenue and customer stickiness as competitors compete for maintenance contracts at renewal cycles. Performance-based SLAs (with upside/penalty bands often up to 10% of contract value) intensify rivalry and reward reliability leaders. Remote diagnostics and predictive maintenance adoption rose to about 45% of fleets in 2024, with the predictive maintenance market near $6.5B, strengthening retention for providers with advanced analytics.
Market split between multinationals and regional fabricators; top 10 hold ~45% of revenue (2024).
Intense price rivalry in standard fencing (industry EBITDA <12%); high-security/integrated segments see fewer competitors.
Integrated systems 60–70% of large enterprise spend; aftermarket ~30% of lifecycle revenue (2024).
| Metric | 2024 Value |
|---|---|
| Top 10 share | ~45% |
| Industry EBITDA (standard) | <12% |
| Integrated systems | 60–70% |
| Aftermarket share | ~30% |
Electronic surveillance—CCTV, AI analytics and drones—can substitute for some physical barriers in lower-risk sites, offering rapid deployment and lower upfront costs; the global video surveillance market topped about $40 billion in 2024, signaling widespread adoption. They provide improved detection but cannot provide the delay/denial of hardened barriers against forced entry. Hybrid deployments combining sensors, barriers and cameras are increasingly dominant, reducing pure substitution risk.
Guarding can replace or reduce fencing at some sites, but studies show mixed outcomes as the global private security market reached roughly $300 billion in 2024 and deployment often complements physical barriers. Labor flexibility appeals—US median security guard wage was about $16.50/hr (BLS May 2024)—yet ongoing opex remains high and human-error incidents persist. Insurance and compliance frequently still mandate physical deterrents, so cost-benefit analysis favors mixed models over full substitution.
Terrain shaping, moats, berms and hostile architecture can act as effective substitutes for fencing in select designs, providing integrated aesthetics and lower ongoing maintenance compared with metal barriers. These measures are highly site-specific and typically harder to retrofit into existing urban or industrial footprints. For critical infrastructure and high-value assets, engineering standards and regulatory requirements continue to favor certified engineered perimeters. Implementation choice hinges on site constraints and compliance demands.
In facilities where threats are mainly digital or insider, budgets shift to IT/cyber and identity systems. Gartner forecasted global security and risk management spending at about $188 billion in 2024, with IAM growing near 10% YoY, diverting funds from perimeter hardware. Physical breaches remain a distinct risk class; balanced architectures limit wholesale budget diversion.
For residential and light-commercial segments, local welders offer fences and gates at 20–40% lower upfront cost than branded Præsidiad systems, substituting where certification is not mandated. Poorer coating durability and absent warranties limit heavy-duty adoption; certified systems show 3–5x longer certified lifecycles. Education on lifecycle cost and warranty value reduces this substitution risk.
Substitutes—video surveillance ($40B global 2024), private security ($300B 2024) and SRM/IT spend ($188B 2024)—reduce but do not replace certified perimeter barriers; local welders cut upfront cost 20–40% yet certified systems deliver 3–5x longer lifecycles, so hybrid models dominate for high-risk sites.
| Substitute | 2024 Value/Stat |
|---|---|
| Video surveillance | $40B |
| Private security | $300B |
| SRM spend | $188B |
| Local welders cost gap | 20–40% |
| Certified lifecycle | 3–5x |
Setting up steel fabrication plus galvanization and coating lines requires CAPEX in the tens of millions USD (galvanizing often 10–30m, coating/high-capacity fabrication pushing into high-single to double-digit millions), while full plant builds commonly exceed 50m; scale is needed to match incumbent cost and lead-time economics, project revenue cyclicality creates 60–120 day working-capital needs, and entrants typically need 18–36 months to reach efficient utilization.
High-security markets demand tested, certified systems: US federal procurement requires FIPS 140-2/3 for cryptographic modules and many EU tenders cite Common Criteria or equivalent. Achieving these approvals is costly and time-consuming—FIPS validation and lab testing commonly exceed $200,000 and can take 6–18 months, while Common Criteria evaluations often span 6–24 months with six-figure costs. Without such credentials, entrants are effectively locked out of government and critical-infrastructure tenders, creating durable entry barriers.
Winning major tenders depends on integrator networks and proven reference sites, and in 2024 many enterprise procurements tacitly expect 3+ live reference installations and established integrator partnerships. Entrants lacking credibility and long‑standing relationships struggle to pass technical and commercial shortlists. Building a regional service footprint and installer base typically requires 12–24 months. Warranty backing and financial assurances are closely scrutinized during due diligence, often requiring multi‑year support commitments.
Open tenders can appear to lower entry barriers, but incumbent learning curves and volume-driven pricing sustain dominance: incumbents typically realize 10–30% lower unit costs and OTIF performance north of 95%, while new entrants often start at 60–80% OTIF and must discount 15–40%, eroding margins and viability. Logistics reliability and sustained OTIF are hard to match early, making focused niche segments the most feasible entry path.
Entry requires CAPEX often $10–100m, 18–36 months to reach efficient utilization, and 60–120 days working capital; incumbents keep 10–30% unit-cost advantage and >95% OTIF versus entrants' 60–80%. Certifications (FIPS/Common Criteria) incur six-figure costs and 6–24 months, blocking many public tenders. Niche focus, integrator partnerships or ~15% R&D intensity are typical mitigation strategies.
| Metric | Value | 2024 |
|---|---|---|
| CAPEX | $10–100m | market data |
| Time to scale | 18–36 months | industry |
| Cert cost/time | $200k+ / 6–24m | govt tenders |
| Incumbent edge | 10–30% cost, >95% OTIF | procurements |


