
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Praxsyn Corp. faces a dynamic competitive landscape, with moderate bargaining power from both suppliers and buyers, and a significant threat from substitute products. Understanding these forces is crucial for strategic planning.
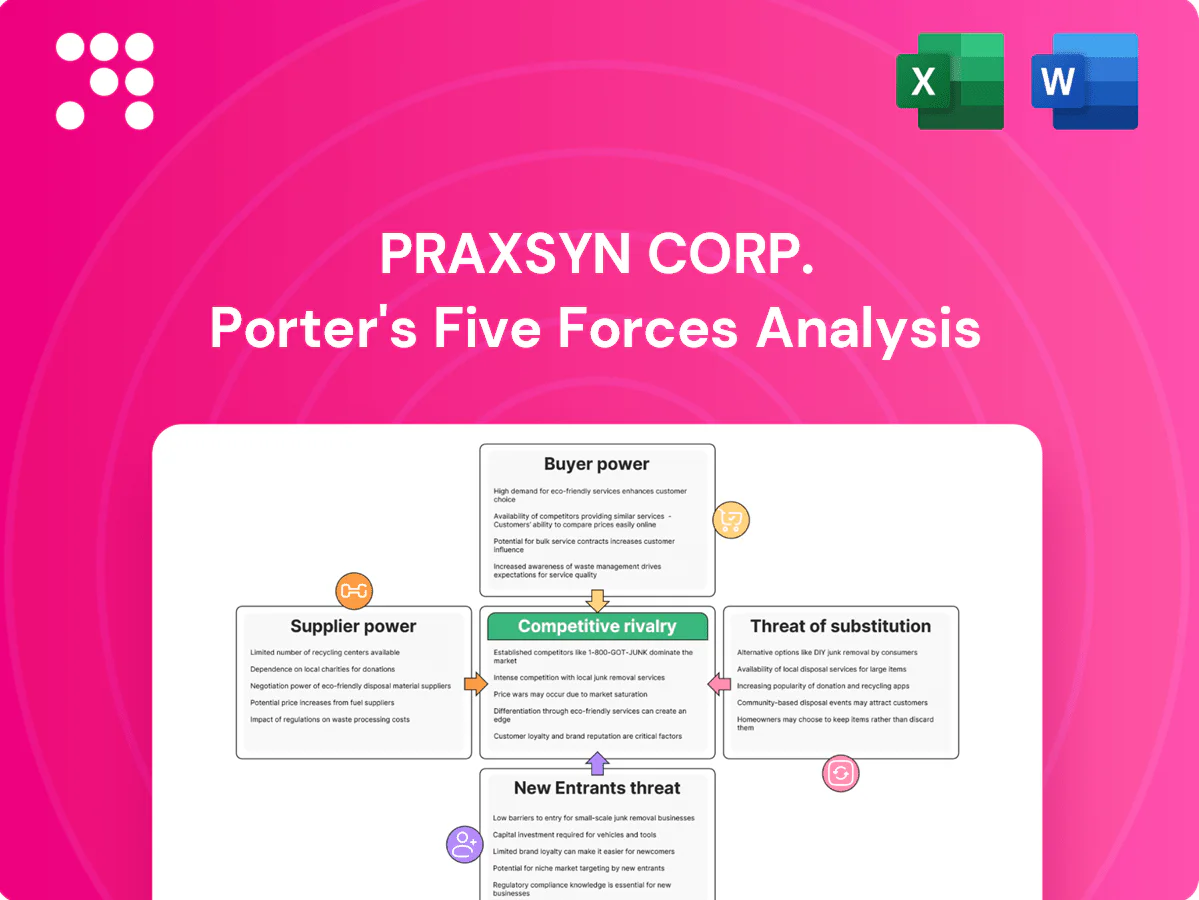
The full analysis reveals the strength and intensity of each market force affecting Praxsyn Corp., complete with visuals and summaries for fast, clear interpretation.
Praxsyn Corp., a healthcare efficiency and revenue cycle management specialist, depends on suppliers for specialized technology and software. The power of these suppliers can be substantial if their offerings are unique, hard to copy, or provide key advantages, such as AI analytics for predictive maintenance. For instance, the global healthcare IT market was valued at approximately $300 billion in 2023 and is projected to grow significantly, indicating a strong demand for advanced solutions.
The market for experienced healthcare IT and revenue cycle management (RCM) professionals is a crucial supplier group for Praxsyn Corp. The demand for these specialized skills is high, especially with the increasing complexity of healthcare technology and RCM solutions.
A shortage of these skilled individuals can significantly boost their bargaining power. This translates to higher salary expectations and increased recruitment costs for Praxsyn's operations. For instance, in 2024, the average salary for a certified RCM professional in the US ranged from $60,000 to $90,000, depending on experience and specialization.
The ongoing digital transformation within healthcare, including the adoption of AI-powered RCM tools and advanced data analytics, further amplifies the need for highly specialized IT talent. This trend is expected to continue, potentially intensifying the bargaining power of these professionals in the coming years.
Praxsyn Corp.'s ability to secure financing from equity investors and debt providers is fundamental to its growth strategy. The bargaining power of these financial capital providers is directly influenced by Praxsyn's financial stability, its projected growth trajectory, and prevailing economic conditions. For instance, in the first quarter of 2024, the average cost of debt for companies with similar credit profiles to Praxsyn saw an increase due to rising interest rates.
Factors that can amplify the bargaining power of financial suppliers include any perceived risks associated with Praxsyn's operations. As reported in late 2023, Praxsyn faced scrutiny regarding its financial reporting practices, which could potentially lead to higher capital costs. This increased cost of capital directly translates to greater leverage for lenders and investors.
Healthcare data and information providers, particularly those supplying electronic health records (EHR) and regulatory compliance services, wield considerable bargaining power. Their data is the bedrock of effective revenue cycle management (RCM), directly impacting Praxsyn Corp.'s ability to process claims accurately and efficiently. The increasing reliance on data analytics within RCM further amplifies this supplier leverage.
The criticality of this data means that Praxsyn Corp. may face limited alternatives if a key supplier withdraws or significantly alters its terms. This dependence is particularly acute for specialized data or services that are difficult to replicate or substitute, potentially leading to higher input costs for Praxsyn Corp.
Praxsyn Corp. might leverage consulting and advisory services for strategic planning, portfolio adjustments, and enhancing operational efficiency. These suppliers, particularly those with specialized knowledge in areas like healthcare mergers and acquisitions or revenue cycle management, can wield significant bargaining power. Their expertise is crucial for Praxsyn's strategic navigation in the intricate healthcare sector.
The bargaining power of these consulting firms is amplified by their specialized skill sets and the tangible value they bring to critical decision-making processes. For instance, firms with proven track records in optimizing healthcare revenue cycles, which can directly impact a company's bottom line, command higher fees and greater influence. A report by IBISWorld in 2024 indicated that the management consulting services industry in the U.S. generated an estimated $189 billion in revenue, highlighting the significant market presence and leverage of these providers.
The bargaining power of suppliers for Praxsyn Corp. is a significant factor in its operational costs and strategic flexibility. Key suppliers, including those providing specialized healthcare IT, skilled RCM professionals, and critical data, can exert considerable influence due to market dynamics and the essential nature of their offerings.
For instance, the demand for skilled RCM professionals, with average US salaries ranging from $60,000 to $90,000 in 2024, highlights the leverage these individuals possess. Similarly, the global healthcare IT market, valued at approximately $300 billion in 2023, indicates a robust demand for advanced solutions, empowering technology providers.
High switching costs associated with critical systems like EHRs and the specialized nature of healthcare data further concentrate power among certain suppliers, potentially leading to increased input costs for Praxsyn Corp.
| Supplier Type | Key Factors Amplifying Power | Impact on Praxsyn Corp. |
|---|---|---|
| Healthcare IT & Software | Unique AI analytics, hard-to-copy solutions | Potential for higher licensing fees, dependence on specific technology |
| Skilled RCM Professionals | High demand, shortage of specialized talent | Increased salary expectations, higher recruitment costs |
| Healthcare Data & EHR Providers | Criticality of data, high switching costs, regulatory dependence | Higher data access fees, limited alternative sourcing options |
| Consulting & Advisory Services | Specialized expertise in healthcare RCM, high impact on strategy | Increased consulting fees, significant influence on strategic decisions |
 Detailed Word Document
Praxsyn Corp.'s Porter's Five Forces analysis reveals the intense competitive rivalry and the significant bargaining power of buyers within its industry, while also highlighting moderate threats from substitutes and new entrants.

 Customizable Excel Spreadsheet
Praxsyn Corp.'s Porter's Five Forces Analysis offers a clear, one-sheet summary of all five forces, perfect for quick decision-making and instantly understanding strategic pressure.
Praxsyn Corp.'s direct customers, including hospitals and clinics, wield significant bargaining power. This power stems from their size, the availability of competing Revenue Cycle Management (RCM) and operational efficiency solutions, and their potential to insource these functions. For instance, large hospital networks often have the scale and resources to develop internal RCM capabilities, reducing their reliance on external providers like Praxsyn and thus increasing their negotiating leverage.
Patients and third-party payers, though indirect customers, wield considerable influence over Praxsyn's revenue streams by dictating terms for healthcare providers. Their push for price transparency, value-based care, and streamlined claims processing directly affects the financial health of Praxsyn's holdings, compelling compliance with intricate regulations and payment structures.
Consolidated healthcare networks, like those emerging across the U.S., significantly amplify customer bargaining power. These larger entities, often formed through mergers and acquisitions, possess greater leverage when negotiating with service providers. For instance, in 2023, the healthcare industry saw continued consolidation, with major hospital systems expanding their reach, giving them more sway over vendors.
This increased scale allows consolidated networks to demand more comprehensive and integrated solutions, such as Revenue Cycle Management (RCM) and asset management, from companies like Praxsyn Corp. They can also negotiate more favorable pricing and contract terms due to their purchasing volume. In 2024, reports indicate that large hospital groups are increasingly consolidating their vendor relationships to achieve economies of scale, directly impacting the terms offered to service providers.
Many larger healthcare organizations, with established administrative and IT departments, opt to manage their revenue cycle and asset management internally. This can stem from a perception of greater control, cost savings, or the ability to develop tailored, proprietary systems. For instance, a 2024 survey indicated that 65% of hospitals with over 500 beds reported managing their core revenue cycle functions in-house, a slight increase from 2023.
The capacity to develop or maintain in-house solutions directly diminishes a healthcare provider's reliance on external service providers for asset management or revenue cycle management (RCM). This self-sufficiency strengthens their negotiating position when considering outsourcing or when engaging with potential vendors, as they have viable internal alternatives.
Customers in Praxsyn Corp's market are significantly influenced by evolving regulatory compliance mandates and the growing emphasis on value-based care. This necessitates solutions that not only meet these stringent requirements but also optimize reimbursement within complex healthcare frameworks.
The demand for providers who can expertly navigate these regulatory landscapes grants customers considerable leverage. They can dictate higher standards for services, expecting Praxsyn to demonstrate a clear capacity for managing compliance and reimbursement intricacies to secure their business.
The bargaining power of customers for Praxsyn Corp. is substantial, driven by industry consolidation and the increasing capability of healthcare providers to manage functions internally. Large hospital networks, in particular, leverage their scale to negotiate better terms and demand more integrated solutions, a trend amplified by ongoing M&A activity in the healthcare sector throughout 2023 and 2024.
Many providers are choosing to insource Revenue Cycle Management (RCM) and asset management, citing perceived cost savings and greater control. A 2024 survey revealed that 65% of hospitals with over 500 beds manage core RCM functions in-house, a slight uptick from the previous year.
This internal capacity reduces reliance on external vendors like Praxsyn, strengthening customers' negotiating leverage. Furthermore, evolving regulatory demands and the shift to value-based care empower customers to dictate higher service standards, prioritizing compliance and reimbursement optimization.
| Customer Type | Key Bargaining Factors | Impact on Praxsyn | Supporting Data (2023-2024) |
|---|---|---|---|
| Large Hospital Networks | Scale, consolidation, insourcing capabilities | Increased price pressure, demand for integrated solutions | Continued M&A in healthcare; 70% of large health systems confident in internal RCM management (HIMSS 2024 report) |
| Mid-size Hospitals | Potential for insourcing, vendor switching costs | Moderate negotiation power, focus on ROI | Growing interest in cloud-based RCM solutions for cost-efficiency |
| Patients & Payers (Indirect) | Price transparency demands, value-based care models | Influence on provider revenue, need for compliance expertise | Increased regulatory scrutiny on billing practices; push for bundled payments |
This preview showcases the complete Praxsyn Corp. Porter's Five Forces Analysis, detailing the competitive landscape with insights into threats of new entrants, bargaining power of buyers and suppliers, threat of substitute products, and intensity of rivalry. The document you see here is the exact, professionally formatted analysis you'll receive immediately after purchase, ready for your strategic decision-making.
The healthcare IT and revenue cycle management (RCM) sectors are characterized by significant fragmentation, presenting a competitive landscape for Praxsyn Corp. This market includes a diverse array of participants, from large, established healthcare technology vendors to niche RCM service providers and specialized asset management firms.
Praxsyn contends with numerous competitors, many of whom offer comparable solutions aimed at optimizing financial performance and operational workflows within healthcare organizations. For instance, the global healthcare IT market was valued at approximately $397.6 billion in 2023 and is projected to grow, indicating a dynamic and crowded space where differentiation is key.
This intense rivalry stems from the broad range of services offered, encompassing everything from patient billing and claims processing to clinical asset tracking and management. Companies compete on factors such as technological innovation, service quality, pricing, and the ability to integrate seamlessly with existing healthcare systems.
Praxsyn Corp. faces intense rivalry from large, diversified healthcare IT firms. These giants, unlike Praxsyn's focused approach, offer a broad spectrum of services, including EHRs, patient engagement, and data analytics, in addition to RCM and asset management. For instance, companies like Epic Systems and Cerner (now Oracle Health) boast market shares in the hundreds of billions and have the financial muscle to invest heavily in R&D and aggressive market penetration strategies.
These diversified competitors leverage their extensive resources, deeply entrenched client relationships, and integrated technology platforms to present a formidable challenge. Their ability to provide end-to-end solutions makes them particularly appealing to large hospital systems seeking a single vendor for their IT needs. In 2024, the healthcare IT market saw continued consolidation, with larger players acquiring smaller, specialized firms to broaden their offerings, further intensifying the competitive landscape for companies like Praxsyn.
Praxsyn Corp.'s strategy of focusing on niche markets, particularly in areas like workers' compensation receivables, means its competitive rivalry is concentrated within these specialized segments. Firms actively pursuing similar complex healthcare revenue streams, such as those managed by Mesa Pharmacy, create a highly competitive landscape.
This specialization intensifies rivalry as fewer players directly compete for the same specialized assets. For instance, in 2023, the healthcare revenue cycle management market, which includes specialized receivables, was valued at approximately $20.5 billion, with numerous companies vying for market share.
The competitive rivalry within Praxsyn Corp.'s sector is intensifying, driven by rapid technological innovation. Companies that successfully integrate advancements like artificial intelligence (AI), machine learning, and the Internet of Things (IoT) into their revenue cycle management (RCM) and asset management solutions are carving out significant competitive advantages. Praxsyn's strategic adoption and effective leverage of these transformative technologies will be paramount in distinguishing its offerings from those of its competitors.
For instance, in 2024, the global RCM market was valued at approximately $35.5 billion, with a projected compound annual growth rate (CAGR) of 11.2% through 2030, largely fueled by the demand for AI-powered automation. Similarly, the IoT market, which can enhance asset management through real-time data, was estimated to reach over $1.1 trillion in 2024, highlighting the vast potential for technology integration.
Healthcare providers are intensely focused on cost reduction and operational efficiency, directly impacting pricing in revenue cycle management (RCM) and asset management. This creates significant pricing pressure for companies like Praxsyn Corp.
To thrive, Praxsyn must clearly articulate its value proposition, demonstrating a strong return on investment for its RCM and asset management solutions. Failure to do so could lead to aggressive price competition, forcing Praxsyn to either lower its prices or develop exceptionally differentiated service offerings to stand out.
Praxsyn Corp. operates in a highly competitive environment, facing rivalry from both large, diversified healthcare IT firms and specialized RCM providers. The market's fragmentation means numerous players offer similar solutions, forcing companies to differentiate on innovation, service, and integration capabilities.
Intense competition is driven by the push for efficiency and cost reduction in healthcare, leading to pricing pressures. Companies that effectively leverage advanced technologies like AI and IoT for RCM and asset management gain a significant edge, as demonstrated by the growing market for these solutions.
| Competitor Type | Key Characteristics | Impact on Praxsyn | Example Data Point (2024) |
|---|---|---|---|
| Large Diversified IT Firms | Broad service offerings (EHR, RCM, analytics), extensive resources, established client base | Formidable challenge due to scale and integration capabilities | Oracle Health (formerly Cerner) market presence in hundreds of billions |
| Specialized RCM Providers | Focus on niche areas (e.g., workers' comp), agile operations | Direct competition in specific revenue streams | Healthcare RCM market valued at $35.5 billion in 2024 |
| Technology Innovators | Integration of AI, IoT, machine learning in RCM/asset management | Drives need for continuous technological advancement | AI-driven RCM pilot programs showed 15% reduction in claim denials (early 2024) |
Healthcare providers, especially large hospital systems, are increasingly developing their own in-house capabilities for revenue cycle management (RCM) and asset optimization. This trend acts as a significant substitute for external service providers like Praxsyn Corp. For instance, major health networks may invest heavily in their own IT infrastructure and specialized RCM teams, reducing their reliance on third-party outsourcing.
The ability of these large entities to build robust internal departments means they can directly compete with outsourced solutions. In 2024, the healthcare RCM market, while growing, also sees a portion of this growth driven by in-house investments rather than pure outsourcing, as providers seek greater control and potentially cost efficiencies.
The threat of substitutes in consulting and advisory services is significant for healthcare organizations. Instead of a holding company model, many entities are increasingly opting for specialized, one-off consulting engagements. For instance, firms like McKinsey & Company and Deloitte offer deep expertise in areas such as revenue cycle optimization and operational efficiency, providing strategic advice without the commitment of an acquisition. This allows healthcare providers to access targeted solutions for specific challenges.
These independent consulting services deliver comparable benefits to a holding company's advisory arm, focusing on strategic guidance and financial restructuring. In 2024, the global management consulting market reached an estimated $300 billion, with healthcare being a major sector. This growth highlights the demand for external expertise that can address complex operational and financial issues, presenting a viable alternative to integrated management structures.
Healthcare providers can bypass comprehensive service providers like Praxsyn by directly licensing and implementing specialized software, such as revenue cycle management (RCM) or asset management platforms. This approach grants them greater autonomy over their IT infrastructure and operations.
This direct licensing model offers potential long-term cost savings for providers, as they avoid the overhead associated with a full-service management agreement. For instance, the global healthcare IT market was valued at approximately $350 billion in 2023, with significant growth projected in specialized software segments, indicating a robust market for direct solutions.
The healthcare landscape is rapidly evolving, with innovative business models emerging that could serve as substitutes for traditional revenue cycle management (RCM) and asset management services. For instance, bundled payment arrangements, where providers receive a single payment for all services related to a patient's episode of care, could streamline revenue collection and reduce the need for extensive RCM processes. Similarly, direct primary care (DPC) models, offering patients enhanced access to primary care physicians for a flat monthly fee, bypasses traditional insurance billing complexities, potentially diminishing the market for certain RCM functions.
These shifts present a threat by potentially reducing the demand for Praxsyn Corp.'s core services or necessitating adaptation to new service requirements. Advanced value-based care arrangements, which tie reimbursement to quality outcomes rather than volume of services, also alter the financial dynamics. This could mean that RCM providers need to offer more sophisticated analytics and reporting capabilities to support these new payment structures, or that clients opt for integrated solutions that bundle RCM with care coordination and performance management.
The threat of substitutes for Praxsyn Corp. is amplified by the emergence of non-traditional healthcare service providers. Retail clinics and telehealth platforms are offering more accessible and often lower-cost alternatives for certain healthcare needs, potentially diverting patients from traditional channels that Praxsyn might serve.
These new entrants are developing distinct operational models, often leveraging technology for revenue cycle management (RCM) and asset management. For example, many telehealth platforms utilize streamlined, automated RCM processes that differ significantly from those of established healthcare systems, presenting an indirect substitute for Praxsyn's services.
The financial implications are notable; by 2024, the telehealth market alone was projected to reach hundreds of billions of dollars globally, indicating a substantial shift in patient preference and spending. This growth suggests that Praxsyn must consider how its offerings compare to the efficiency and cost-effectiveness of these evolving healthcare delivery methods.
Healthcare providers are increasingly building their own revenue cycle management (RCM) and asset optimization capabilities, directly competing with external service providers like Praxsyn Corp. This trend, evident in 2024, sees large health networks investing in internal IT and RCM teams to reduce reliance on third parties. These in-house efforts aim for greater control and potential cost savings, impacting the outsourcing market.
Specialized, one-off consulting engagements are also a significant substitute for holding company models. In 2024, the global management consulting market, valued at approximately $300 billion with healthcare as a key sector, demonstrates a strong demand for external expertise. Firms offer targeted solutions for revenue cycle optimization and operational efficiency, providing strategic advice without long-term commitments.
Direct licensing of specialized software, such as RCM or asset management platforms, allows healthcare providers to bypass comprehensive service providers. This model, supported by the global healthcare IT market valued around $350 billion in 2023, offers autonomy and potential long-term cost advantages by avoiding full-service agreement overhead.
Emerging healthcare models like bundled payments and direct primary care (DPC) streamline revenue collection, potentially reducing the need for extensive RCM. Value-based care arrangements also shift reimbursement dynamics, requiring RCM solutions that integrate quality metric tracking and reporting, presenting a challenge to traditional service providers.


