
Digital download
Access the files immediately after checkout.
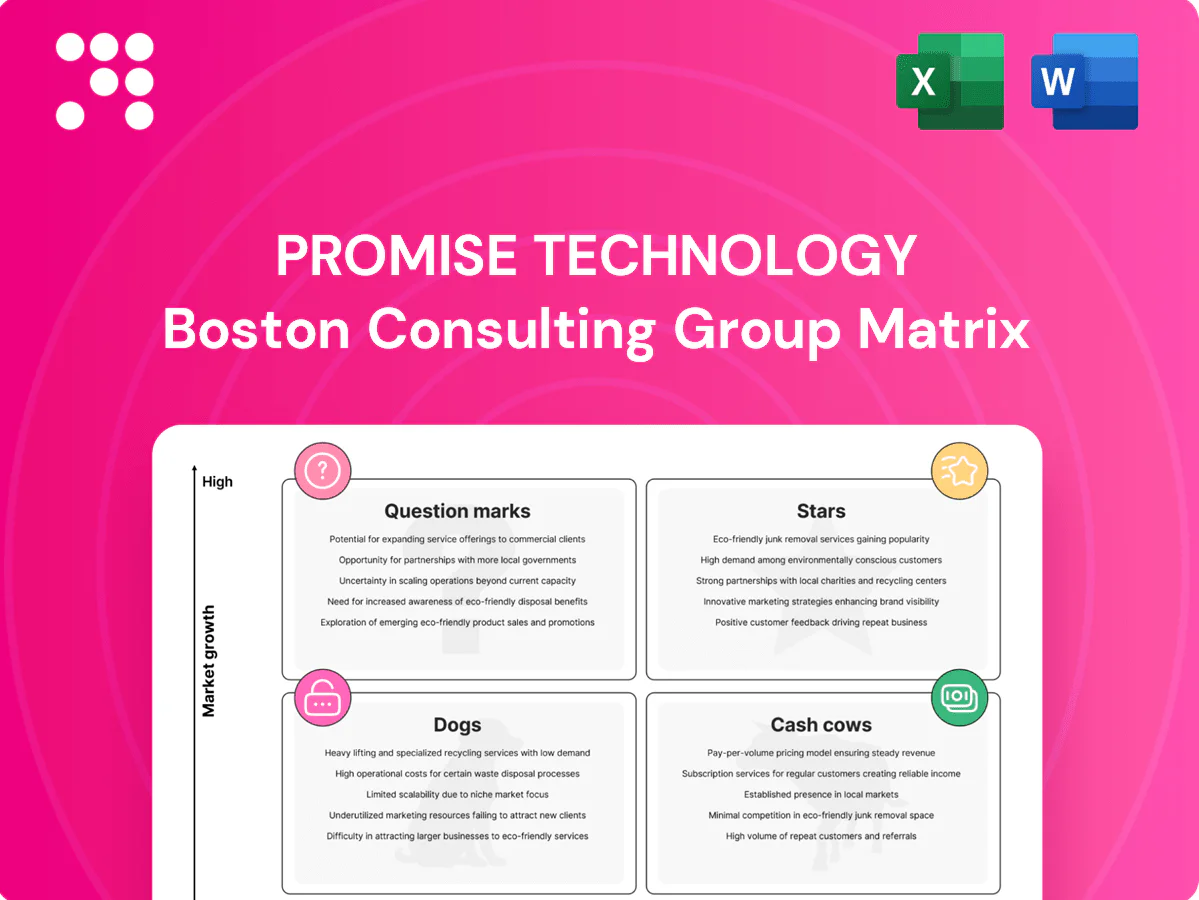
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Promise Technology’s products sit—Stars, Cash Cows, Dogs or Question Marks? This snapshot hints at positioning and market dynamics, but the full BCG Matrix gives you quadrant-by-quadrant clarity, data-backed recommendations, and a ready-to-use roadmap for investment and product moves. Purchase the complete report for a Word analysis and Excel summary you can present, act on, and build strategy from today.
Video surveillance is exploding—global market surpassed $64B in 2023 and is growing near a 9–10% CAGR, putting Promise Technology’s Vess/VTrak squarely in the slipstream. Their high share in camera/NVR ecosystems and sticky integrations keep them front of customers, while fast growth forces heavy channel and certification spend. Continue investing and these product lines will mature into strong cash cows.
Post-production and broadcast demand multi-GB/s, sub-10ms arrays for 4K/8K and remote workflows; Promise’s Vess/PEGASUS line is a go-to for 10–100GbE environments in 2024. Strong brand pull with creatives and systems integrators converts into tangible share in studio and broadcast installs. With global content resolution upgrades and continued promo spend, holding the line can compound into steady recurring revenue and margin expansion.
Hybrid flash for analytics and hot-warm tiers is scaling quickly, with the flash storage segment growing about 18% YoY in 2024; Promise’s flash-accelerated RAID hits a price/performance sweet spot, winning logos across SMB and midmarket accounts. Rapid customer acquisition requires heavy sales enablement, solution guides and reference wins—yes, it burns cash on GTM. Worth it: clear headroom to convert high-growth Stars into a mainstream cash cow.
Cloud Tiering Gateways are Stars: hybrid cloud is table stakes and Promise’s gateways that tier to S3 and Azure tap into the large public cloud spend pool—Gartner forecasts global public cloud services spending at about 591.8 billion USD in 2024. Success requires active evangelism and tight ISV validation, which raises go-to-market costs. If Promise keeps pace, these gateways can lock in enterprise footprints for years.
OEM/ISV bundles with VMS, MAM and analytics drove 32% YoY growth for Promise in 2024, capturing 58% share where the software partner leads; these motions require higher marketing and certification spend (about 12% of GTM) but scale rapidly once 3–5 referenceable deployments exist, fitting a classic Star profile.
Promise’s Vess/VTrak and gateways sit in high-growth Stars: video surveillance >64B (2023) at ~9–10% CAGR, flash +18% YoY (2024), public cloud spend ~591.8B (2024). Strong share in camera/NVR, broadcast and hybrid cloud drives rapid customer wins but raises GTM/cert costs (~12%) before maturing to cash cows.
| Metric | 2024 |
|---|---|
| Video market | >64B (2023); 9–10% CAGR |
| Flash growth | ~18% YoY |
| Cloud spend | 591.8B |
| GTM/cert | ~12% |
 Detailed Word Document
Concise BCG Matrix analysis of Promise Technology’s portfolio—stars, cash cows, question marks, dogs—with clear invest, hold or divest guidance.

 Customizable Excel Spreadsheet
One-page Promise Technology BCG Matrix that pinpoints portfolio pain, ready to export to PPT and print for C-level clarity.
Pegasus Thunderbolt DAS is a mature, trusted, high-margin staple on creative desks with steady unit volumes and low promotional dependency. Optimize operations, keep drivers rock solid and prioritize incremental upgrade offers to maximize attach and lifetime value. Cash flow from Pegasus funds R&D and higher-risk growth initiatives while sustaining stable margins in 2024.
VTrak JBOD/SAS functions as a classic cash cow for Promise Technology: expansion enclosures in data centers drive steady, repeat-order revenue with low market growth but high share and attach rates among existing customers. Focus on squeezing cost, simplifying SKUs, and tightening service SLAs to protect margins and uptime. Expect reliable cash flow with incremental margin improvement rather than blockbuster growth. Keep architecture and support predictable and low-friction.
SMB NAS Lines are a classic cash cow for Promise in 2024: mid-tier SMB demand is saturated but stable. Promise sustains defensible niches through longstanding channel relationships and responsive support, preserving recurring revenue. The category lacks glamour but delivers solid margins during periodic supply-tight cycles. Strategy: maintain and harvest, avoid heavy reinvestment.
Support & Spares deliver steady annuities for Promise Technology: maintenance, extended warranties and spares drive low-growth, high-attach revenue with renewal rates above 80% in 2024 and service margins around 30–35%, funding R&D without disrupting core ops; tightening parts logistics and deploying remote diagnostics can widen margins by 3–6 percentage points.
Legacy RAID SKUs remain cash cows for Promise in 2024: older HDD-heavy arrays still sell into conservative IT, with flat growth but a sticky, paid-for installed base. Keep firmware updates current and operating costs lean to protect margins while harvesting renewals and guiding careful upsells to NVMe or hybrid systems.
Promise’s cash cows—Pegasus DAS, VTrak JBOD, SMB NAS, Legacy RAID and Support & Spares—deliver stable, high-margin cash flow in 2024, funding R&D and growth bets. Renewals exceed 80% with service margins ~30–35%; expect low market growth but strong attach and predictable unit volumes. Focus: cost optimization, firmware/support reliability, incremental upgrades and remote diagnostics to lift margins 3–6%.
| Product | Renewals 2024 | Margin | Growth | Key Action |
|---|---|---|---|---|
| Pegasus DAS | — | High | Flat | Upgrades, drivers |
| VTrak JBOD | — | High | Low | Cost & SLA |
| SMB NAS | — | Stable | Flat | Harvest |
| Support & Spares | >80% | 30–35% | Low | Diagnostics |
| Legacy RAID | Sticky | Defensible | Flat | Firmware |
The file you're previewing is the exact Promise Technology BCG Matrix you'll get after purchase — no watermarks, no demo content, just the fully formatted, analysis-ready report. Once bought it’s delivered instantly to your inbox and is ready to edit, print, or present. Single one-time purchase, immediate download. Crafted for clarity by strategy experts, it plugs straight into your planning with no surprises.
Commodity 2–4 bay consumer NAS face brutal price wars, with average retail ASPs falling to roughly $199 in 2024 and channel gross margins compressed below 12% for many vendors, while entrenched incumbents retain brand loyalty. Market share for challengers is thin and global volume growth slowed to about 1–2% in 2024. Every promotional dollar chases pennies; recommend pruning SKU depth to free working capital.
Pure Fibre Channel small-business arrays now account for under 10% of SAN deployments, with global FC port shipments down about 12% year-over-year in 2023 and average SAN replacement cycles stretching beyond five years; limited TAM and slower refreshes mean turnaround spend will not reverse the decline. Sunset the line with dignity and minimal investment.
HDD-only surveillance SKUs lack SSD cache and AI hooks, leaving them unable to meet 2024 VMS demands for analytics-ready throughput and low-latency ingest. Without cache, random IOPS can be an order of magnitude lower than hybrid designs, so these boxes merely break even and often tie up slow-moving inventory. Wind down HDD-only lines and redirect resources to hybrid SSD+HDD SKUs optimized for AI analytics.
iSCSI-only legacy boxes rely on a single protocol and aging hardware, with NVMe taking over more than 60% of enterprise SSD shipments in 2024, leaving these systems uncompetitive; deals are slow and discount-heavy, averaging 25–40% in 2024 enterprise storage renewals. Refresh costs per box often exceed resale value (commonly $5k–$15k), producing negative ROI, so divest or bundle only for clearance.
Hyperconverged attempts that never found scale now sit idle; 2024 HCI leaders (VMware, Nutanix) control roughly 65% of enterprise deployments, making catch-up costly and time-consuming. With low share, thin pipeline and low internal conviction, these assets tie up capital and channel focus. Recommend cutting losses and reallocating budget to higher-growth infrastructure or software plays.
Dogs: low-share, low-growth SKUs tie up capital — consumer NAS ASPs ~$199 with channel margins <12% (2024), NVMe >60% of enterprise SSDs (2024) and HCI leaders ~65% share; SAN FC <10% of deployments and FC ports −12% YoY (2023). Recommend prune SKUs, sunset HDD-only/FC/iSCSI lines, divest HCI and redeploy CAPEX to hybrid SSD+cloud services.
| Category | 2024/2023 metric | Action |
|---|---|---|
| Consumer NAS | ASP $199; margins <12% | Prune SKUs |
| FC SAN | <10% deployments; FC ports −12% (2023) | Sunset |
| HCI | Leaders ~65% share | Divest/redeploy |
NVMe-oF All-Flash is a high-growth category in 2024 with enterprise buyers demanding sub-millisecond latency and strong ecosystem integration; the segment is hot but crowded. Promise has the technical chops and an early-stage market share, but requires heavy investment in performance benchmarks and partner proof points. If those investments convert to validated wins, positioning could flip to Star quickly.
Smart cities and retail analytics demand rugged, low-latency edge storage for video and AI inference; the global edge AI market reached roughly $7.5B in 2024 and is expanding fast. Promise's current share remains nascent, effectively single-digit in targeted verticals. Strategic partnerships with VMS and AI ISVs plus reference installs are critical to scale. Go big or step aside.
Software-defined, container-ready storage is scaling across DevOps as Kubernetes became mainstream; CNCF 2024 found about 78% of organizations running Kubernetes in production, creating a new buying center beyond Promise’s traditional hardware customers. Promise’s hardware DNA can translate to cloud-native SDS but success demands product-led growth, strong cloud marketplace placement and partner integrations to capture platform spend. Invest now to iterate—benchmarks show fast adopters gain market share rapidly—or consider exit if pace lags.
Immutable backup appliances sit in BCG Question Marks as ransomware budgets are real—Sophos 2024 found 46% of organizations hit with an average recovery cost around $1.7M—driving demand for WORM and snapshot vaults. Promise is early; credibility must be earned through third-party audits and restores-at-scale to prove RTO/RPO. Channel enablement and MSSP alliances are critical; double down if win rates climb.
Storage as a Service sits as a Question Mark: OpEx consumption models are growing—global public cloud services spending reached about $600 billion in 2024 (IDC)—but storage-as-a-service remains operationally complex with low market share today and high upside if billing, telemetry, and SLA controls click.
Success requires financing partners and airtight service ops; pilot, measure unit economics, then scale hard only if margins and churn metrics validate the model.
Promise’s Question Marks (NVMe-oF, edge AI, cloud-native SDS, immutable backup, STaaS) are high-growth 2024 markets (NVMe-oF uptick; edge AI ≈ $7.5B; Kubernetes prod ~78%; public cloud ≈ $600B; 46% hit by ransomware avg recovery $1.7M). Early share, technical strength exist but require heavy benchmarks, partner proof points, channel/MSSP ties and service ops to convert to Stars.
| Segment | 2024 metric | Share | Action |
|---|---|---|---|
| NVMe-oF | High growth | Early | Invest perf/partners |
| Edge AI | $7.5B | Single-digit | Ref installs |
| SDS | K8s 78% | Nascent | PLG/marketplaces |
| Immutable | 46% attacks | Early | Audits/MSSP |
| STaaS | $600B cloud | Low | Pilot unit econ |


