
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
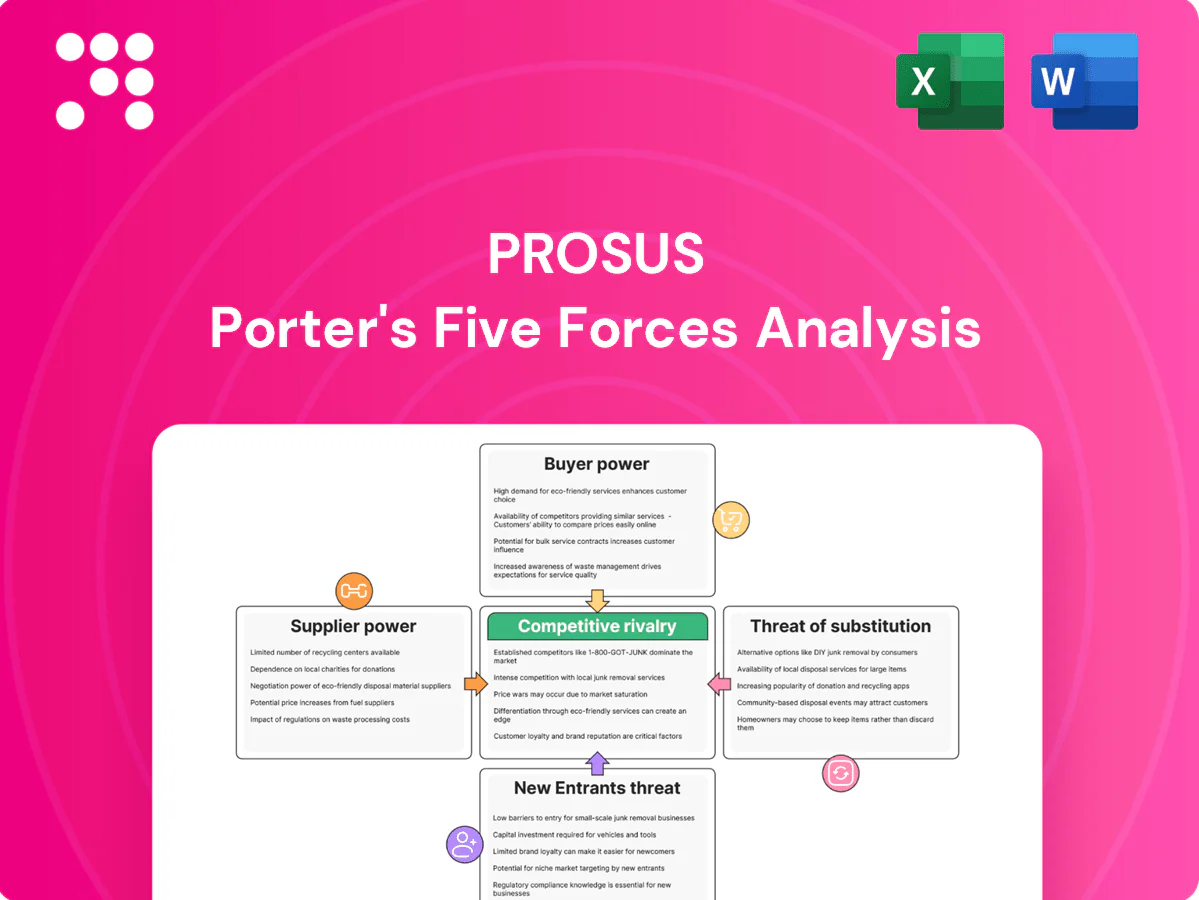
Prosus faces a dynamic mix of strong buyer power, fierce digital-platform rivalry, and constant threat from agile entrants and substitutes, while supplier leverage varies across its global portfolio. Our snapshot highlights key pressures on margins, growth levers, and strategic vulnerabilities. This brief only scratches the surface—unlock the full Porter's Five Forces Analysis for force-by-force ratings, visuals, and actionable recommendations tailored to Prosus.
Prosus-backed platforms compete directly with Amazon, Alibaba, Meta, Google and Apple across commerce, ads and payments; Google+Meta capture roughly 60% of global digital ad spend (2024), allowing cross-subsidization and bundled services. Sustainable moats demand superior local execution, regulatory fluency and tight category focus, while strategic partnerships (telcos, banks, local retailers) can neutralize costly head-to-head battles.
Regional champions such as Mercado Libre (2024 revenue about $13B), Sea (2023 revenue ~$11B), Grab and Delivery Hero (2023 revenue ~€9B) and Flipkart drive intense competition in Prosus core markets, leveraging strong local incumbency and dense logistics networks. Rivalry plays out through subsidies, advanced ad tech and fintech integrations, compressing margins. Prosus’s diversified portfolio strategy helps hedge concentrated regional exposure.
Food delivery and ride-hailing platforms drive competition through deep discounts and courier incentives, compressing contribution margins and delaying profitability; Delivery Hero reported group revenue of €7.7bn in 2023 while many peers still subsidize orders in 2024. Route density, batching and marketplace ads partially offset subsidy pressure by raising orders per courier and ad monetization. Rationalization of subsidies typically follows consolidation cycles as scale enables margin recovery.
Rapid shifts in checkout, wallets, BNPL and AI-driven recommendations have created an arms race where slow rollout risks losing share to faster experimenters; global digital wallet users reached about 4.6 billion in 2024, intensifying competition. Shared platforms and reusable components shorten time-to-market, while data network effects compound performance and personalization advantages.
Consolidation via M&A reshapes rivalry by concentrating market share and strengthening bargaining positions as Prosus pursues scale and selection through strategic acquisitions.
Acquisitions provide rapid route density and product breadth but integration risk and intensified regulatory scrutiny remain binding constraints on deal value and pace.
Active portfolio rebalancing reallocates capital toward winning assets, accelerating consolidation among top competitors.
Intense rivalry vs Amazon, Alibaba, Google and Meta compresses margins; Google+Meta held ~60% of global digital ad spend in 2024. Regional champions (Mercado Libre ~$13B 2024, Sea ~$11B 2023) defend incumbency with logistics and fintech. Subsidies in delivery/ride-hail and BNPL fuel an arms race; consolidation and M&A restore margins but raise regulatory risk.
| Metric | Value |
|---|---|
| Google+Meta ad share (2024) | ~60% |
| Mercado Libre revenue (2024) | ~$13B |
| Sea revenue (2023) | ~$11B |
| Global digital wallet users (2024) | ~4.6B |
Consumers can bypass marketplaces by buying in-store or on brand-owned websites, a risk amplified as global e-commerce accounted for about 23% of retail sales in 2024 (Insider Intelligence). For payments, direct bank transfers and cash remain viable alternatives in many markets. Marketplaces must offer superior convenience and reliability to offset offline immediacy. Omnichannel tools—click-and-collect, unified inventories, loyalty—can convert these substitutes into complements.
Social platforms and super-apps (WeChat ~1.3 billion MAUs in 2024) integrate shopping, payments and messaging, creating native commerce channels that can bypass traditional marketplaces. Influencer-driven discovery, with influencer marketing spend near $21 billion in 2024, often replaces search-led discovery. Embedded checkout reduces friction and disintermediates aggregators, while partnerships and social-native features help platforms retain merchants.
Instant A2A and local real-time rails increasingly substitute card and wallet flows, driven by ubiquity and lower fees; India’s UPI crossed 100 billion annual transactions in 2023–24, illustrating consumer and merchant appetite for rails. Lower interchange and near-zero merchant costs make cash/bank rails attractive, while value-added services such as fraud protection and reconciliation preserve revenue for platforms. Orchestration across multiple rails keeps Prosus-relevant services layered atop core rails.
Large restaurant chains and retailers increasingly insource delivery or deploy white-label solutions, cutting aggregator order volume and commission income; industry commissions average about 20% in 2024, making insourcing materially attractive. Differentiated demand generation and last-mile efficiency are essential moats, while hybrid models and SaaS tools can reclaim portions of insourced volume.
Free content (YouTube >2B monthly users in 2023), peer-to-peer learning and employer-led training can substitute paid platforms for many learners, making credential value and measurable outcomes key to stickiness; Coursera reported 104M learners by 2023. Adaptive learning and cohort-based courses raise differentiation, while partnerships with universities and employers reduce substitution risk as the global edtech market heads toward HolonIQ's $404B projection for 2025.
Substitutes—from offline retail (global e‑commerce 23% of sales in 2024) to social commerce (WeChat ~1.3B MAUs in 2024) and influencer-driven buying (marketing spend ~$21B in 2024)—erode marketplace depth. Payment rails (India UPI >100B annual transactions 2023–24) and insourced delivery (industry commissions ~20% in 2024) further disintermediate. Prosus must layer value (omnichannel, SaaS, fraud/reconciliation) to retain merchants and margins.
| Metric | Value |
|---|---|
| E‑commerce share (2024) | 23% |
| WeChat MAUs (2024) | ~1.3B |
| Influencer spend (2024) | $21B |
| UPI txns (2023–24) | >100B |
| Avg commission (2024) | ~20% |
Acquiring users, building logistics and achieving density typically require hundreds of millions in upfront investment, which entrants often cannot sustain without deep-pocketed backers. New players struggle to reach the scale needed for efficient unit economics and low CAC that Prosus-backed platforms benefit from. After 2022, investor discipline tightened, reducing late-stage capital availability and raising the effective entry barrier. Established networks retain clear cost and scale advantages.
Regulatory licensing—KYC, AML, data privacy and sector-specific permits—adds 6–12 month delays and drives compliance costs (often 5–10% of operating expense), deterring smaller fintech and marketplace entrants. Global data-privacy and AML enforcement has produced billions in fines annually, and audits raise barrier to entry. Prosus-backed firms leverage experience across 80+ jurisdictions to navigate requirements; missteps can trigger fines, bans or delayed market entry.
Two-sided marketplaces and payments scale with user and merchant density, and Prosus leverages network liquidity—its ~27% stake in Tencent and PayU presence in over 50 markets amplify reach and transactions. Cold-start problems make it hard for entrants to match incumbent selection and reliability, slowing GMV ramp. Loyalty programs and subscription revenues deepen retention and recurring cash flow. Category-specific density in classifieds and payments is costly and time-consuming to replicate.
Building last-mile networks, fraud prevention workflows and scalable customer support remains nontrivial for Prosus: operational excellence beyond software is a material barrier to entry, and 2024 industry reports reaffirm that route optimization and fulfillment tech require time and proprietary data to mature. Quality lapses quickly erode trust and retention, raising churn and return costs. New entrants face high upfront capex, recruitment and tech-training needs.
Incumbents like Prosus exploit rich first‑party datasets to personalize products, underwrite risk, and prevent fraud, creating millions‑strong feedback loops that new entrants lack. Building brand trust and dispute‑resolution capabilities typically takes years and sustained transaction volume. Strong privacy and security postures increasingly gate market access, raising entry costs significantly.
High upfront capex and marketing (often $100–500m) plus tighter late‑stage funding (VC late‑stage deals down ~30% in 2023–24) raise financial entry barriers. Compliance delays (6–12 months) and ongoing costs (5–10% opex) deter smaller entrants and risk fines. Network effects, Prosus ~27% stake in Tencent and PayU in 50+ markets, create liquidity and data moats that are costly to replicate.
| Barrier | Impact | Metric |
|---|---|---|
| Capital | High | $100–500m |
| Compliance | Delay/cost | 6–12 months; 5–10% opex |
| Network/Data | Moat | 27% Tencent; PayU 50+ markets |


