
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
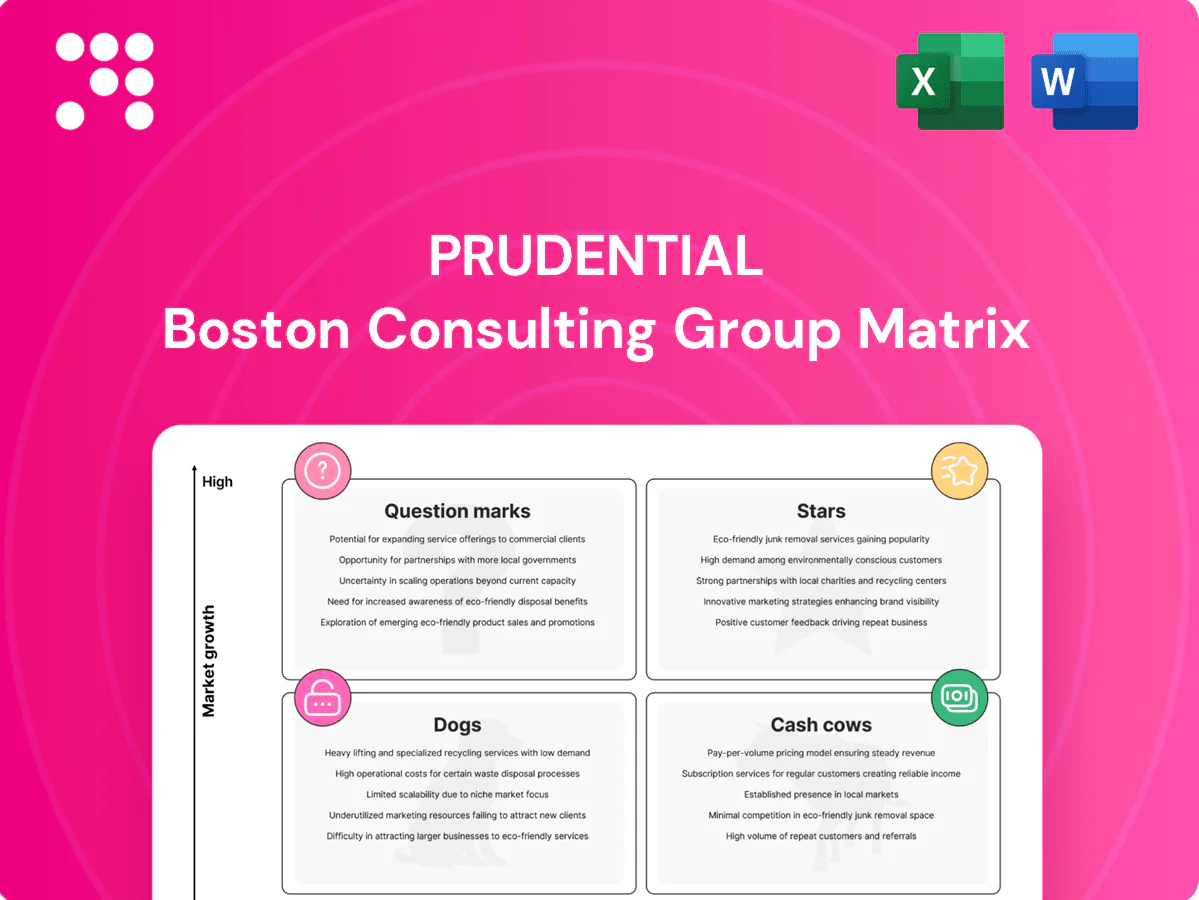
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Quick look: Prudential’s BCG Matrix snapshot shows which product lines are pulling their weight and which need a rethink—think Stars that deserve investment, Cash Cows that fund growth, Question Marks to decide on, and Dogs to phase out. This preview teases the trends; buy the full BCG Matrix to get quadrant-by-quadrant placements, data-backed recommendations, and a ready-to-use Word report plus an Excel summary. Get instant access and stop guessing—make strategic moves with confidence.
High-growth demand and Prudential’s strong footprint—serving about 26 million customers across Asia with reported APE growth near 6% in 2024—make Core health & protection a front-line leader. Protection gaps in Asia remain vast, with estimates around $20 trillion across Asia-Pacific, and are widening in markets like China, India and SEA. Keep feeding distribution, underwriting analytics and medical partnerships to convert unmet demand. Hold share now; this engine is set to mature into substantially larger cash flows over the next decade.
Large, productive agency forces give Prudential scale and speed in fast-growing cities, enabling rapid market coverage and higher penetration of protection products; the agency channel remains a primary driver of new business and back-book persistency. They sell complex protection well and defend share against new entrants, but require ongoing investment in training, digital tools and incentives. Continued spend is justified as the channel sustains top-line growth and persistency metrics.
Prudential’s bancassurance mega-partnerships across 10 markets deliver strong volume growth and reportedly reduce acquisition cost per policy by ~30% versus agency channels, improving APE economics.
Pulse digital health ecosystem is a Star for Prudential with wide reach (12M users in 2024) and rising engagement (+32% YoY), serving as a credible bridge from wellness to insurance; it’s not just leads—behavioral data sharpens risk and pricing, cutting claims ~7% and lifting conversions ~3.8%.
Wealth-linked unit-linked life sits in Stars as demand for wealth creation plus protection surged among emerging middle classes; Asian life premiums rose ~7% YoY in 2024, boosting sales of hybrid products.
Prudential’s strong brand and advisory network win bigger ticket sales and higher persistency, but market volatility in 2024 means careful risk-product tuning and dynamic asset allocation.
Keep momentum by expanding digital advisory tools, transparent fee slabs and client dashboards to retain leadership and lift VONB and AUM growth.
Stars: Core health & protection, agency, bancassurance, Pulse and UL — Prudential ~26M customers, APE +6% (2024), Pulse 12M users (+32% YoY), bancassurance cuts acquisition ~30%, Asian life premiums +7% (2024); invest in distribution, underwriting analytics and digital advisory to capture APAC protection gap ~$20T.
| Metric | 2024 | Impact |
|---|---|---|
| Customers | 26M | Scale |
| APE growth | +6% | Top-line |
| Pulse users | 12M (+32%) | Data/Leads |
| Bancassurance | -30% ACQ cost | Profitability |
 Detailed Word Document
Prudential BCG Matrix: evaluates each unit across Stars, Cash Cows, Question Marks, Dogs and recommends invest, hold, or divest.

 Customizable Excel Spreadsheet
One-page Prudential BCG Matrix mapping each business unit into quadrants for clear prioritization and faster decisions
Renewal premiums from Prudential’s in-force life book are large and sticky, generating steady, predictable cash flows that underpin capital allocation. Low incremental acquisition cost and high persistency create classic milk-the-book economics, so management emphasizes retention, service quality, and disciplined claims handling. These renewal cash streams fund strategic investments in digital capabilities and selective new-market expansion.
With-profits/participating life sits as a cash cow in Prudential’s BCG matrix: mature blocks generate steady, predictable cashflow and retained value, supporting core markets where brand trust remains high. Capital intensity falls once blocks are scaled, making new acquisition marginally capital-light versus legacy servicing. Maintain strict investment discipline and bonus-smoothing to protect solvency and customer confidence while harvesting surplus cash. 2024 performance targets focused on sustaining mid-single-digit annual payouts and measured capital extraction.
Core bancassurance renewals deliver dependable cash: renewals often cost ~10% of new-acquisition spend and in 2024 accounted for the majority of recurring premium in bank channels, so relationship maintenance outperforms heavy marketing. Joint bank-insurer campaigns lifted upsell conversion by ~20% in 2024 at minimal incremental cost. Protecting pricing, terms and SLAs keeps churn near industry low levels (~8%).
Eastspring mature mandates act as Prudential cash cows, delivering steady fee income from seasoned AUM of c. USD 267bn (2024) and high retention from internal and external clients; operating leverage from scaling platforms lifts margins. Maintaining consistent performance and sensible fees is critical to preserve cash generation. Excess cash funds growth initiatives without significant new capex.
Renewal-heavy life and bancassurance books generate stable, low-cost cash flows (renewals ~10% of new-acquisition cost, bancassure churn ~8%) while with-profits and established group health deliver predictable margins (claims inflation ~5%). Eastspring mandates provide steady fee income on c. USD 267bn AUM (2024). Surplus funds digital investment and selective expansion.
| Metric | 2024 |
|---|---|
| AUM | c. USD 267bn |
| Renewal cost | ~10% of acquisition |
| Upsell lift | ~20% |
| Churn | ~8% |
| Claims inflation | ~5% |
The file you're previewing on this page is the final Prudential BCG Matrix you'll receive after purchase. No watermarks or demo content—just a fully formatted, ready-to-use report built for strategic clarity. After buying you'll get the exact same editable file, ideal for presenting, printing, or dropping into your planning docs. It's authored by strategy pros and sent instantly—no surprises, no revisions needed.
Small, sub-scale product niches in fragmented markets tie up operations and capital: long-tail SKUs commonly make up about 60% of items but generate roughly 20% of revenue. With market share under 5% and annual growth often below 2%, these Dogs show low share, little growth, and scarce brand pull. Rationalize or exit to free capacity—divestitures can reallocate working capital to higher-return lines. Customers rarely miss offerings that never achieved traction.
Capital-heavy guarantees—legacy-style products—strain capital with little new demand in 2024, forcing capital charges up as duration mismatches persist. Pricing seldom matches today’s rates and volatility; the 10-year Treasury averaged near 4% in 2024, widening spreads versus old guarantees. Hedge costs eat margin fast, eroding profitability. Wind down or reprice; turnarounds rarely repay the capital drag.
Standalone travel/accident micro-lines are highly commoditized and aggregator-driven, with over 50% of retail purchases routed through price-comparison sites in recent industry reporting; low loyalty forces rising marketing spend while margins compress (2024 industry trend). These products show little synergy with core protection strategy, so minimize exposure and redirect resources to higher-margin protection lines.
Sub-scale corporate pensions in select markets sit in the Dogs quadrant: fragmented employer bases, tough pricing and high admin burden erode margins; many schemes hold under £50m while UK pension assets were ~£2.9tn in 2024, leaving low share plus low fees as dead cash. Hard to differentiate without scale tech; consider consolidation or strategic exit.
One-off affinity deals have been tactical tie-ups that never reached sustainable volume and clogged distribution teams; integration effort often outweighs the marginal premium uplift, and observed renewal quality is weak, prompting reallocation of resources to durable channels.
Dogs: sub-scale SKUs (≈60% items, ≈20% revenue), market share <5% and growth <2%; divest or rationalize. Legacy guarantees drain capital as 10y Treasury ≈4% in 2024, hedging erodes margins. Sub-scale pensions (<£50m) in fragmented markets; UK pension assets ≈£2.9tn in 2024—consolidate or exit.
| Metric | Value (2024) |
|---|---|
| Long-tail SKU share | 60% items / 20% revenue |
| Market share | <5% |
| 10y Treasury | ≈4% |
| UK pension assets | £2.9tn |
Africa mass-market protection sits on a huge runway with insurance penetration still low at roughly 3.5% of GDP across the continent, early share and distribution are still forming. Mobile money and micro-agency models show promise given wide digital payment adoption and rising agent networks. Needs targeted investment in onboarding, claims automation and trust-building; if scale lands, this can flip to a Star quickly.
Digital D2C traffic surged ~35% YoY in 2024, yet conversion (~2%) and ticket size (30–50% below agency) lag agency channels (~8%), leaving it a Question Mark in Prudential’s BCG mix.
UX fixes, smarter pricing and embedded journeys have shown 2–3x conversion lifts in 2024 pilots and can unlock a step-change in value per visit.
CAC must decline via partnerships and first‑party data; targeted markets where digital CAC is 20–40% lower (SEA) merit doubling down, not a global roll‑out.
SME health platforms target an underserved, fast-growing segment—SMEs account for roughly 90% of firms and about 50% of employment (World Bank, 2024)—but service intensity and per-customer touch are high. Bundling wellness, telemedicine and admin tools can shift share: telehealth usage rose over 50% versus 2019 (2024), improving engagement. Unit economics remain unproven at scale, with many pilots showing CAC payback beyond 18 months. Pilot hard, standardize fast, then scale.
Islamic/takaful expansion fits Prudential’s footprint given Islamic finance assets exceeded $3.5 trillion (IFSB 2023), but Prudential’s takaful presence remains early-stage; product design, Sharia governance and tailored distribution require bespoke builds to capture rising demand. Strategic partnerships with local players can compress time-to-scale; pursue a focused, prioritized rollout rather than scattershot entry.
Wealth management for the mass affluent is a Question Mark: fast-growing demand for advice plus protection, competing directly with banks and fintechs offering slick platforms; global robo-advice and hybrid advice AUM surpassed $1 trillion in 2024, signaling scale opportunities. If advisory tools and hybrid models land, Prudential’s share can surge through targeted propositions. Test-and-learn on pricing and portfolio mixes before scaling.
Africa mass-market (penetration ~3.5% GDP) and digital D2C (traffic +35% YoY; conv ~2%) are high-upside Question Marks needing CAC compression and ops automation to become Stars. SME health and takaful show demand (Islamic finance >$3.5T) but unit economics unproven; mass-affluent wealth needs hybrid advice pilots to prove LTV/CAC before scale.
| Segment | 2024 metric | Action |
|---|---|---|
| Africa mass-market | Penetration ~3.5% GDP | Invest distribution & claims automation |
| Digital D2C | Traffic +35% YoY; conv ~2% | UX/pricing pilots to raise conv |
| SME health | Telehealth +50% vs 2019 | Pilot bundles; prove CAC payback |
| Takaful | Islamic assets >$3.5T | Partnerships + Sharia governance |
| Wealth (mass affluent) | Robo/hybrid AUM >$1T | Hybrid advisory pilots |


