
Digital download
Access the files immediately after checkout.
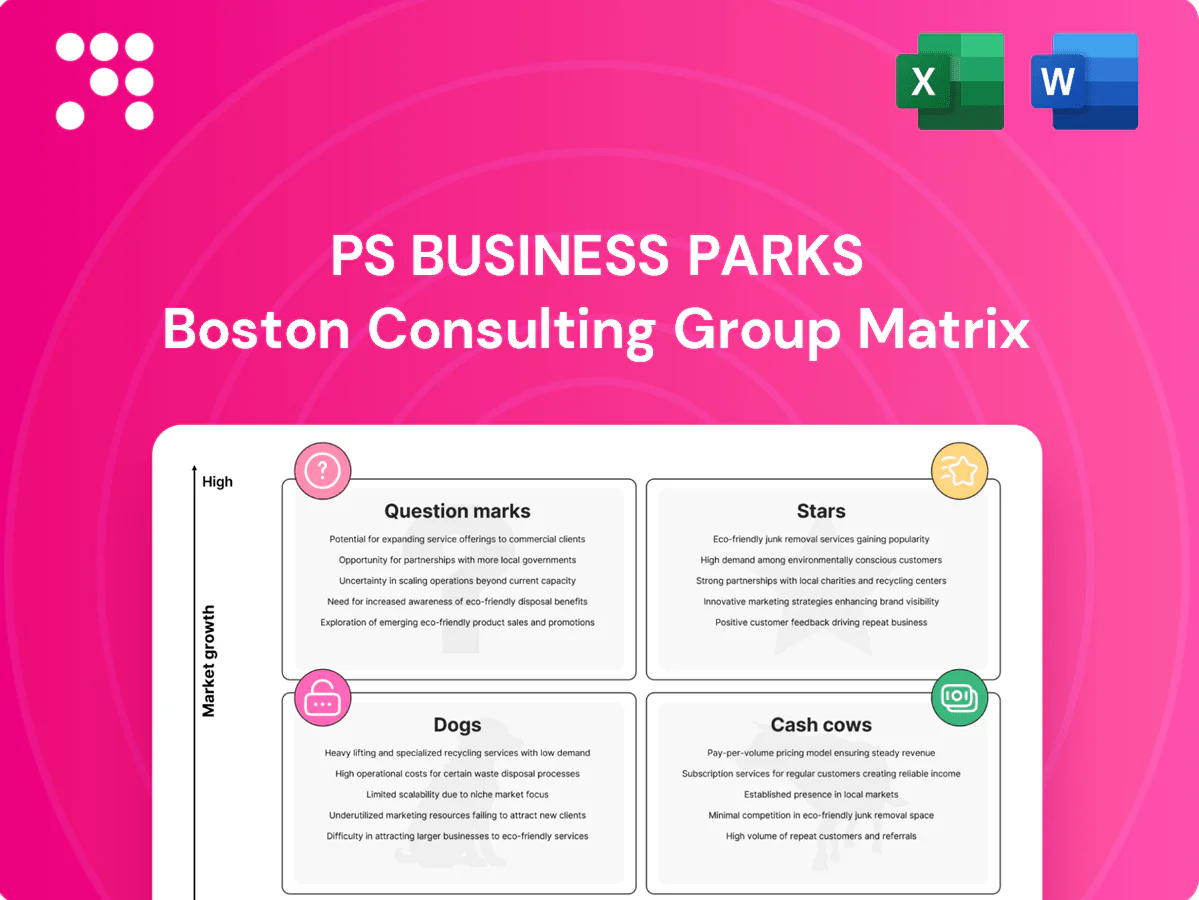
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious how PS Business Parks’ assets stack up—Stars, Cash Cows, Dogs or Question Marks? This snapshot outlines the big moves, but the full BCG Matrix digs into quadrant placement, revenue drivers and risks with data-backed takeaways. Buy the full report for Word and Excel deliverables and a ready strategic playbook. Get clarity fast and decide where to double down.
High-demand small-bay industrial in dense metros posts sub-5% vacancy in 2024, keeping rents elevated and transaction pricing strong. E-commerce penetration (~20% of retail sales in 2024), reshoring of supply chains, and same-day delivery growth sustain solid demand. PSB’s multi-tenant model and ~97% portfolio occupancy align perfectly with this segment. Continue selective capex and dynamic pricing to capture upside.
Scarce land and brutal permitting in LA/OC create Stars for PS Business Parks, with nonstop tenant demand and sub-2% industrial vacancy in 2024. High rent growth offsets higher operating intensity; renewal spreads have run consistently in the mid-to-high single digits quarter after quarter. Protect the share; these assets can age into Cash Cows when growth cools.
Data center ecosystems in Northern Virginia spill strong demand into flex and support space, with the market hosting over 2,000 MW of commissioned capacity in 2024 and double-digit hyperscaler leasing growth that fuels adjacent absorption.
Sticky enterprise and tech-adjacent service tenants plus onsite expansion options are driving steady flex absorption and longer lease tenor.
Competition is intense, yet PS Business Parks’ Northern VA footprint and flexible deal structures continue to win transactions.
Maintain targeted capex on build-to-suit specs and power upgrades (higher kW/rsf, redundant feeds) to preserve the competitive lead.
Turnkey small‑suite move‑in ready programs cut tenant downtime and accelerate occupancy; SMBs pay premiums for speed, simplicity and short leases, driving higher effective rents per sq ft and faster cashflow conversion in 2024 market recovery.
Operations platform and pricing muscle: local leasing teams, tight controllables and data-driven rent stacks underpinned PS Business Parks' 2024 same-store NOI outperformance, turning pricing into a durable edge. In multi-tenant assets, relentless execution on turnovers and concessions is the moat, and consistent NOI gains in 2024 cemented market share. Keep sharpening renewal strategy and deploy tech where payback is proven.
Small-bay industrial and Northern VA flex are Stars for PS Business Parks: portfolio occupancy ~97% and 2024 small-bay vacancy <5%, driving mid-to-high single-digit rent growth and same-store NOI outperformance; prioritize targeted capex (power, BTS) and turnkey small-suite programs to lock market share.
| Asset | 2024 Vacancy | Occupancy | Rent Growth | CapEx |
|---|---|---|---|---|
| Small-bay industrial | <5% | ~97% | mid–high % | BTS, permitting |
| Northern VA flex | ~2–4% | 95–98% | high single % | power upgrades |
 Detailed Word Document
In-depth BCG analysis of PS Business Parks' portfolio, detailing Stars, Cash Cows, Question Marks, Dogs with strategic recommendations.

 Customizable Excel Spreadsheet
One-page BCG matrix placing PS Business Parks units in clear quadrants to simplify portfolio decisions and cut analysis time.
Stabilized suburban flex assets operate at high occupancy with modest capex and low tenant improvement/leasing commission cycles, delivering strong cash conversion and predictable lease rolls. These parks function as cash cows in PS Business Parks’ BCG matrix, funding growth elsewhere while requiring expense discipline. Milk steady income and optimize OPEX to preserve yield; continue targeted capex only for rent-driving upgrades.
Mature infill industrial assets at PS Business Parks post-2024 operate with supply effectively capped and rent growth normalized, converting tight market dynamics into steady cash flow. Occupancy remained around 96% in 2024, driving predictable NOI and limited re-tenanting risk with high renewal rates. Minimal promotion is required as market demand sustains pricing; strategy: maintain, maintain, maintain.
Long‑term office/flex hybrids: credit tenants on longer terms cover the nut nicely—PSB’s 2024 portfolio showed average lease terms near 6–8 years and ~90% occupied, keeping cashflow steady. Growth is muted, but a ~300 bps spread to secured debt supports attractive returns. Keep capex surgical and avoid fancy upgrades; let leases throw off free cash for distribution or debt paydown.
Parking, storage, and service income provide steady, high-margin ancillary revenue for PS Business Parks with minimal capex and low growth; industry self-storage occupancy was about 92% in 2024 and core ancillary revenue contribution typically remains stable year-over-year. These streams are sticky, simple to manage and hard to disrupt, so optimize pricing annually and avoid overbuilding to protect margins.
Decades-long SMB relationships drive repeat deals, producing ~95% portfolio occupancy and ~80% tenant retention in 2024, with bad debt below 1% of rent; minimal selling cost and fast decision cycles keep margins high. Not flashy but highly profitable—keep high-touch service and light paperwork to preserve renewal economics.
Stabilized suburban and infill flex assets deliver high occupancy (95–96% in 2024), low capex and predictable NOI, funding growth while needing tight OPEX. Office/flex hybrids with 6–8yr average leases and ~90% occupancy provide steady cashflow; ancillary income (storage/parking ~92% occ) adds margin. Maintain targeted capex, optimize pricing, deploy cash to distribution/debt paydown.
| Metric | 2024 |
|---|---|
| Occupancy | 95–96% |
| Lease term avg | 6–8 yrs |
| Tenant retention | ~80% |
| Bad debt | <1% |
The file you're previewing is the exact PS Business Parks BCG Matrix report you'll receive after purchase — no watermarks, no placeholders, just the finished product. It's fully formatted and ready to use in presentations, planning sessions, or client decks. Once purchased you'll get the same editable file immediately, so you can print, tweak, or present without delay. Crafted by strategy pros, it’s built for clarity and action.
Commodity suburban office: low demand and high availability—U.S. suburban office vacancy hovered around 18–19% in 2024 (CoStar), and tenant downsizing has eroded rental rates and valuations. Turnarounds require heavy TI/LC investments, often exceeding 10–20% of annual lease value, with uncertain re-leasing timelines. Cash becomes trapped in TI/LC with weak ROI; best to shrink exposure or exit.
Outlying flex in thin-demand nodes shows chronic backfill failure; occupancy in many tertiary submarkets stalled in 2024 and rent growth lagged into low single digits while operating expenses crept up year-over-year. Marketing campaigns consumed leasing teams with limited conversions and high cost-per-lead. Consider sale or land-bank only if zoning flips to higher‑value uses that restore upside.
Older office assets at PS Business Parks suffer obsolete MEP systems, code compliance gaps and dated layouts that stall leasing momentum; CoStar reported U.S. office vacancy near 17.5% in mid‑2024, amplifying market resistance. Each new tenant typically triggers a capital project—often six‑figure upgrades—so returns frequently fail to clear investor hurdles. Cut losses or pursue radical repositioning (flex conversion, lab, residential) to salvage value.
Micro-units suffer high turnover that erodes effective rent and increases labor and administrative loads, while collections risk rises in softer markets, compressing net operating margins; consolidate or reconfigure into larger bays to reduce per-unit admin drag.
Non‑core geographies in PS Business Parks show small footprints away from operating hubs, creating weak scale economics and higher per‑unit operating costs; vendor costs spike and oversight thins, so portfolio performance can stall despite management effort. PS Business Parks was acquired by Blackstone for $7.6 billion in 2021, underscoring focus on consolidation into higher‑performing core markets. Divest and refocus on core metros.
PS Business Parks Dogs: commodity suburban offices, outlying flex, obsolete offices and micro‑units face low demand and high vacancy (U.S. suburban office vacancy ~18–19% in 2024, CoStar), high TI/LC and turnover eroding NOI; non‑core geographies suffer scale drain. Recommend divest, land‑bank or radical repositioning and redeploy capital to core metros.
| Asset | Issue | 2024 metric | Action |
|---|---|---|---|
| Suburban office | High vacancy | 18–19% vacancy | Exit/reposition |
| Outlying flex | Poor backfill | Rent growth low‑single digits | Sell/land‑bank |
Office‑to‑industrial conversions sit as Question Marks for PS Business Parks: zoning shifts and site layouts can unlock real value if entitlements land, but approvals are binary and failed permits mean sunk time. Industry data (CBRE 2024) shows US industrial vacancy near 4.2% with continued rent upside, justifying conversions where clear. Capex is chunky—industry estimates ≈80–150 USD/sqft—timing is murky. Go big where path to approval and logistics demand is proven; pass where uncertain.
Spec suites with lab-capable infrastructure let PS Business Parks chase life‑science demand, with industry retrofit premiums typically cited in 2024 at roughly $75–200 per sq ft incremental versus office fit‑outs and full lab builds often exceeding $400–700 per sq ft. Utility loads, dedicated HVAC/venting and code escalation can raise costs 30–60% quickly. If anchor interest (tenant pipeline >20–50k sq ft) forms, pursue; otherwise, don’t dabble. Pilot small projects, then scale deliberately.
Digital leasing and self-serve tours could slash downtime and broaden the funnel for SMB tenants, who account for 99.9% of US firms, increasing reach beyond traditional hours. Capital outlay for PropTech only makes sense if tour-to-lease conversion rises materially; target a measurable uplift before scaling. The heavy lift is process change—staffing, verification, and access control. Test aggressively in a few parks and roll only if ROI proves out.
LED retrofits can cut lighting energy use by up to 75% (DOE), HVAC smart controls typically shave 10–20% of HVAC costs, and rooftop solar can meaningfully offset common-area loads; together these upgrades can help PS Business Parks win tenants and lower opex, but observed rent premiums vary by market and remain fickle, often limited to niche green-seeking tenants.
New Sun Belt submarkets show growth in 2024 but outcomes hinge on local scale and operating teams; tightened entry pricing in 2024 raises the cost of mistakes; pursue a cluster strategy or avoid standalone entry; stage in via JVs or small portfolios first to limit execution risk.
Office‑to‑industrial and lab conversions are Question Marks: strong upside if entitlements and logistics align, but binary approval risk and ~$80–150/sqft capex. Lab/spec-suite demand can justify $75–200/sqft retrofit premiums (full labs $400–700+/sqft); require anchor pipeline. PropTech and energy upgrades cut opex but need proven tour-to-lease or rent premium before scale.
| Opportunity | 2024 Metric |
|---|---|
| Industrial vacancy | 4.2% (CBRE 2024) |
| Conversion capex | $80–150/sqft |
| Lab retrofit premium | $75–200/sqft |


