
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Want clarity on QIWI’s portfolio—what’s a Star, what’s sucking cash, and what’s worth a bet? This QIWI BCG Matrix preview scratches the surface; buy the full report for quadrant-by-quadrant placements, data-backed recommendations, and a ready-to-use Word + Excel pack. Save time, cut risk, and get strategic moves tailored to QIWI’s real market position—purchase now and turn insight into action.
Large active base—over 20 million QIWI wallets as of 2024—within a consumer payments category growing ~12% annually, driving high transaction frequency and share-of-wallet. It leads consumer payments in key markets and requires ongoing investment in UX, rewards, and security to defend growth. BCG play: keep investing to stay top-of-mind and top-of-phone so it can retain share and graduate into a powerhouse Cash Cow.
Utility bill payments via QIWI wallet are a high-frequency, sticky use case in a market where digital-pay habits expanded sharply—global digital wallet users surpassed 4.4 billion in 2024—giving QIWI strong share but requiring ongoing promos, reminders and deeper integrations to remain the default. Cash in equals cash out on growth spend today, so double down while the category continues pulling users online.
Mobile top-ups are everyday needs driving high volumes—QIWI processes millions of top-up transactions daily and via its ~15,000 kiosks in 2024, maintaining channel leadership as users migrate to digital. Promotion and placement costs remain material, but a positive unit economics flywheel is visible: steady share retention turns growth into a cash engine. Prioritize bundling, rewards, and instant confirmations to deepen engagement and margins.
Merchant acceptance is expanding and QIWI’s recognizable brand accelerates onboarding; with global e‑commerce ~19% of retail in 2024 and cart abandonment ≈70% (Baymard 2024), small conversion gains matter. Competition is fierce, so acquisition and incentives burn cash; hold the line on conversion and coverage to let it mature into a Cash Cow. Fund integrations, SDKs, and anti‑fraud to defend the lead.
B2B Payment Gateway for SMEs: SMEs are accelerating digital payments in 2024, and QIWI’s share in SME acquiring is meaningful and rising, driven by API adoption and faster settlements. Growth requires sales enablement, hands-on onboarding, and robust risk controls—costly but strategic investments that improve retention. With sustained share growth the business becomes margin-rich at scale; continued investment in APIs, instant settlement rails, and advanced reporting is essential.
QIWI Stars: >20M wallets in 2024, consumer payments growing ~12% YoY; high-frequency use cases (bills, top-ups via ~15,000 kiosks, millions daily) drive share but need continued promo, UX and security spend to defend leadership and convert to Cash Cow.
| Metric | 2024 |
|---|---|
| Wallets | 20M+ |
| Category growth | ~12% YoY |
| Global wallets | 4.4B users |
 Detailed Word Document
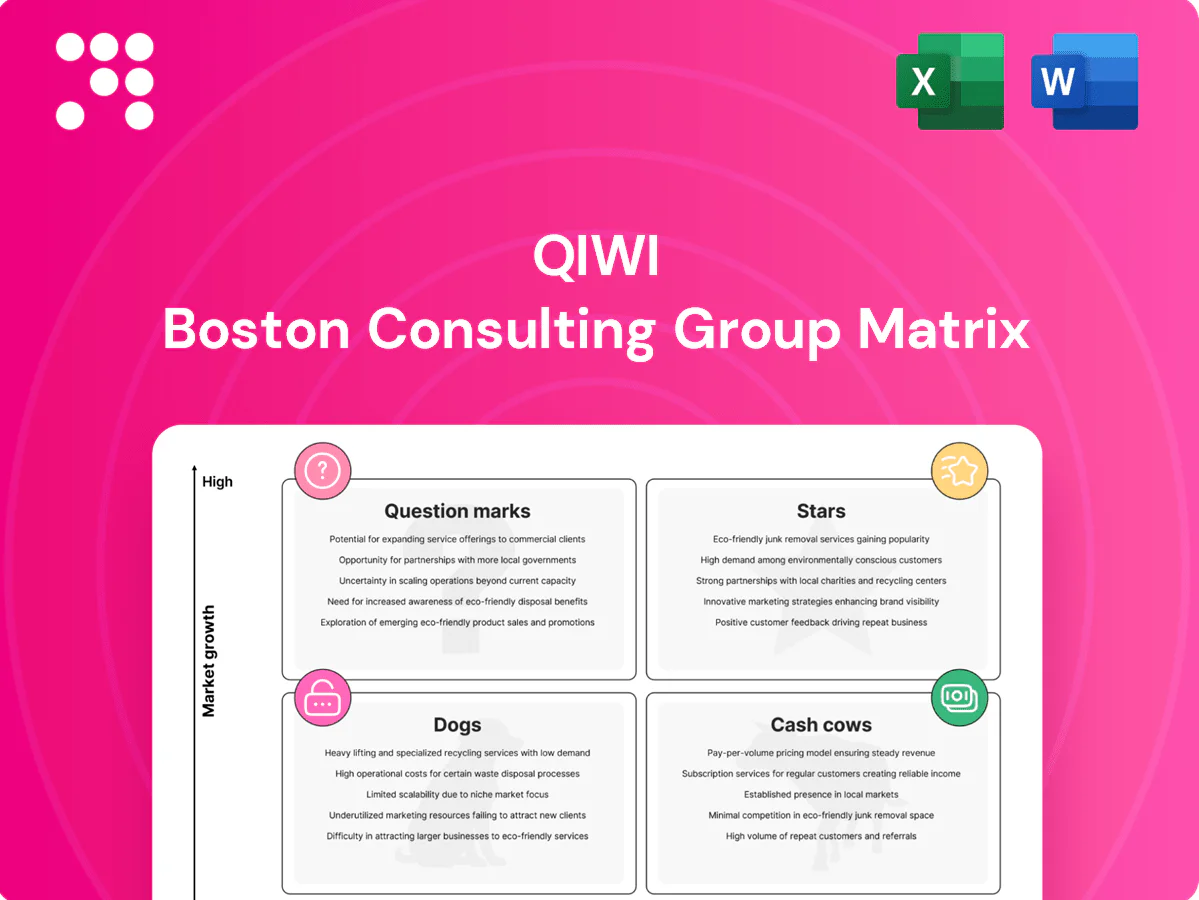
Concise BCG map of QIWI’s products: Stars, Cash Cows, Question Marks, Dogs with investment, hold or divest guidance.

 Customizable Excel Spreadsheet
One-page QIWI BCG Matrix highlighting cash cows and problem units for fast, actionable decisions
Physical kiosk cash‑in network sits in a mature market with a commanding presence and predictable transaction volumes; capex is largely sunk and incremental promotion is minimal. When routes and uptime are optimized, unit economics deliver solid margins and dependable cash flow. Milk the network reliably while upgrading selectively where measured efficiency gains justify investment.
Domestic P2P transfers inside the wallet hold a high share in a low-growth, habitual segment, with 2024 volumes broadly stable as user behavior remains entrenched. Unit economics become attractive once the network is built, driving high marginal margins on incremental transfers. Marketing needs are low—acquisition costs have declined—and maintaining uptime and disciplined fees is critical to protect recurring cash flow.
Recurring Bills & Templates drive low-cost retention through saved profiles and repeat payments, sustaining stable transaction volumes rather than high growth. Automation and fewer support touches raise margins, with industry studies showing up to 20–30% cost-to-serve reductions from self-service flows. Invest in resilient infrastructure and proactive reminders to keep churn near zero and secure predictable cash flows.
Gaming & Digital Content Payments: Established partnerships with studios and app stores ensure steady demand despite limited category growth; the global games market was about $200 billion in 2024, supporting predictable volumes. High conversion and low servicing cost deliver dependable cash, requiring minimal promo beyond periodic campaigns; focus on catalog updates and 99.9% uptime to harvest margins.
Agent and partner commission streams in QIWI represent a broad partner footprint across a mature payments ecosystem, supporting roughly 150,000 partner points and digital integrations as of 2024; predictable take-rates averaging about 1.2–1.8% drive steady margin with low incremental costs. These streams are cash-positive, funding broader initiatives and contributing materially to operating cash flow in 2024. Optimizing commercial terms and shortening settlement cycles can squeeze incremental yield by several dozen basis points without capital investment.
QIWI cash cows—kiosk network, wallet P2P, recurring bills, gaming payments and agent commissions—delivered stable, high-margin cash flow in 2024: ~150,000 partner points, wallet volumes flat y/y, take-rates 1.2–1.8%, gaming market ≈$200B. Low capex and marketing; focus on uptime, fee discipline and selective efficiency upgrades to preserve cash.
| Segment | 2024 metric | Note |
|---|---|---|
| Agent network | ~150,000 points | Take-rate 1.2–1.8% |
| Gaming | $200B market | High conversion, low cost |
| Recurring bills | Stable volumes | 20–30% lower cost-to-serve |
The file you're previewing is the exact QIWI BCG Matrix you’ll receive after purchase. No watermarks, no placeholders—just a fully formatted, ready-to-use strategic report. It’s editable, print-ready, and designed for clear decision-making. Buy once and download immediately; the final document arrives for your presentations, planning, or investor reviews with no surprises.
Low‑traffic standalone kiosks show flat to declining footfall and capture a negligible local share, tying up service costs and cash with minimal return. Operational overheads and repair cycles outpace revenue, making turnarounds rarely pay back. They are prime candidates for removal or consolidation into higher‑traffic channels or digital-first solutions.
Legacy prepaid plastic cards sit in a shrinking app-first market where digital wallets dominate consumer flows; card usage is thin and declining. Ongoing maintenance, compliance and replacement costs can consume over 60% of card unit economics, leaving break-even at best and losses often reported. Recommend wind-down and migrate remaining users to digital-first QIWI wallet options to stop bleeding margin.
Cash‑Out Services show low growth and a shrinking share as QIWI customers migrate to fully digital flows by 2024; fraud exposure and cash logistics materially depress margins, with operational costs and chargebacks repeatedly offsetting revenue gains. Continuous tactical fixes have failed to restore unit economics, so reduce scope or raise prices to reflect true cost, or prepare divestment.
Dogs: Niche Billers with Manual Reconciliation — tiny volumes and stagnant category in 2024, consuming disproportionate back-office effort; revenue often trapped in operational friction and dispute cycles, imposing a complexity tax that erodes margins and ROI. Standardize workflows or sunset these billers to free capacity for higher-growth segments.
Dogs: Niche billers with <5% merchant count and ~0% YoY growth in 2024, tying up >30% of reconciliation hours and generating <1% of payments revenue; high dispute rates and manual costs erode margins. Standardize or sunset to redeploy ops capacity to growth segments; expected cost savings ~15–25% of back‑office spend.
| Metric | Value (2024) |
|---|---|
| Merchant share | <5% |
| YoY growth | ~0% |
| Reconciliation effort | >30% |
| Revenue contribution | <1% |
SME Financial Services faces rising demand as SMEs represent about 90% of businesses and contribute over 50% of employment globally, yet QIWI’s market share in SME banking and lending remains at an early stage. Heavy upfront investment is required in risk models, onboarding and client support to scale credit offerings and control loss rates. If customer adoption and credit performance meet targets, this Question Mark can convert to a Star. Strategic choice: commit significant resources or cap exposure—do not straddle.
Global cross‑border remittances are expanding—estimated at roughly $730B in 2024—while QIWI’s remittance footprint remains a tiny fraction of that market, limiting current revenue impact. Compliance, corridor build‑out and liquidity carry measurable costs that erode margins; if specific corridors scale they become strategic and defensible. Recommend test‑and‑scale in select lanes with clear KPIs; otherwise cut underperforming corridors.
Offline QR acceptance is growing at double-digit rates globally, but entrenched POS and wallet rivals limit share; rollout should be hardware-lite with SDKs and contactless QR to lower merchant friction.
Early stages are economically tough at low scale—unit economics improve only after sustained volume—so QIWI must use incentives and consumer education to build frequency.
Prioritize dense micro-markets to prove unit economics before national expansion; pilot clusters enable measurable CAC payback and margin stabilization.
Subscription Billing Tools for SMEs: the recurring-economy keeps expanding and global subscription revenues surpassed $1.5 trillion in 2024, but penetration among SMEs remains early-stage; winning requires product depth, dunning automation and rich analytics. Expect upfront cash burn for integrations and support; if retention solidifies, this segment can graduate into Star territory.
BNPL/pay-over-time at checkout is a Question Mark for QIWI: category growth is strong globally, while QIWI’s share remains nascent and undeveloped. Credit risk, higher funding costs and merchant activation are cash drains that require disciplined underwriting and partner economics. With focused data-driven underwriting and select distribution partners, upside is material; otherwise pause investment until unit economics clear.
Question Marks: SME services (SMEs ~90% of firms; >50% employment) and subscription tools (global subscription rev $1.5T 2024), remittances ($730B 2024) and BNPL show high growth but QIWI share remains nascent; significant upfront investments and credit/funding costs risk cash burn; pursue focused pilots with KPIs and scale winners or cut underperformers.
| Segment | 2024 Size | QIWI Share | Key Cost | Decision |
|---|---|---|---|---|
| SME Finance | — | <5% | risk models, onboarding | Pilot |
| Remittances | $730B | <1% | corridor build | Test&scale |
| Subscriptions | $1.5T | <5% | integration, support | Pilot |
| BNPL | fast-growing | <5% | funding, credit | Narrow focus |


