
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
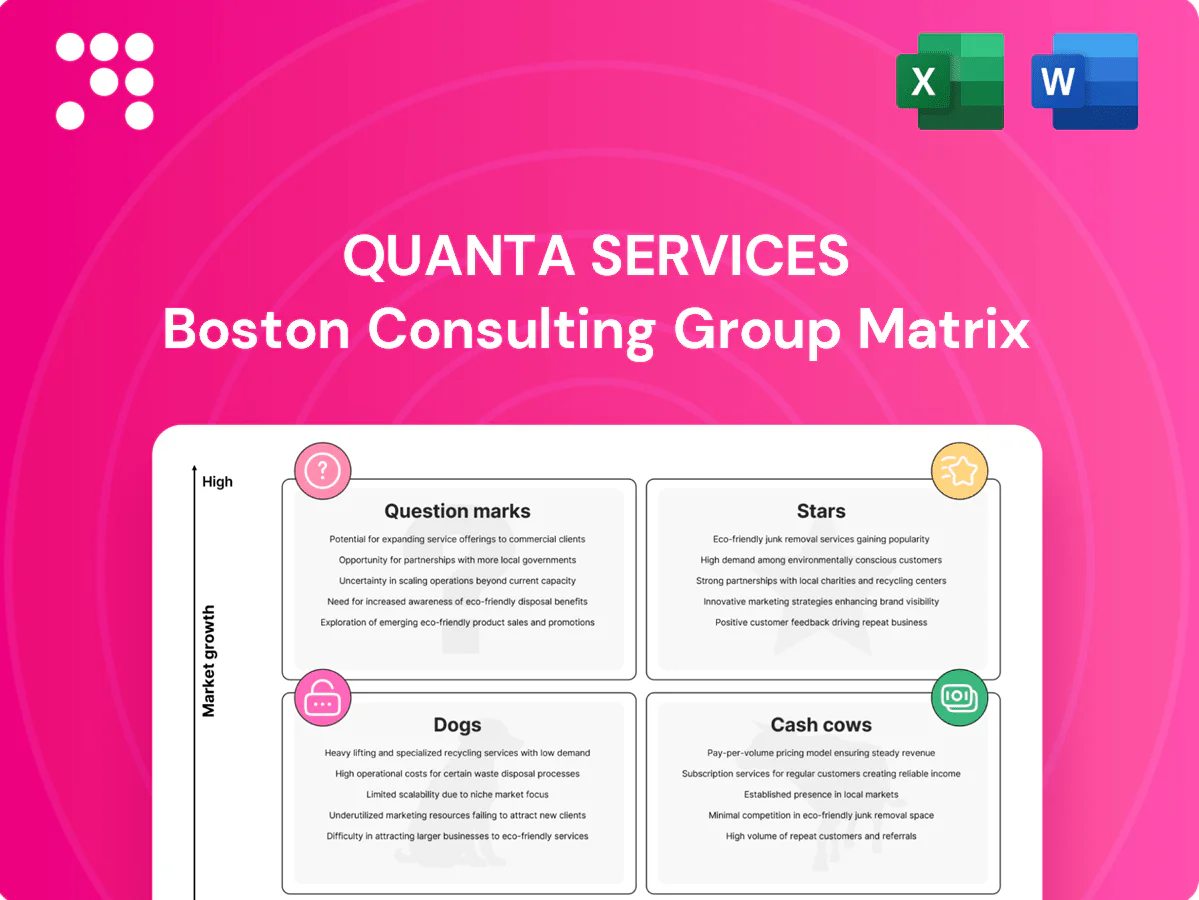
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Quanta Services' businesses sit — Stars, Cash Cows, Dogs or Question Marks? This preview scratches the surface; buy the full BCG Matrix for quadrant-by-quadrant placements, data-backed recommendations, and a clear roadmap for capital allocation. Purchase now for instant access to a polished Word report plus an actionable Excel summary so you can present, decide, and move faster.
High growth, high share—this is Quanta’s home turf: in 2024 Quanta recorded roughly $16 billion in revenue with backlog above $20 billion, reflecting strong utility demand. Utilities are pouring capex into hardening, undergrounding and expansion, with North American utility grid spend rising double digits year-over-year. Quanta leads turnkey EPC and maintenance programs across North America and should keep investing aggressively to defend share and scale capacity.
Utility-scale solar and wind keep coming online—U.S. interconnection queues topped 1,000 GW in 2024—so connections must be built fast. Quanta’s EPC depth and substation expertise make it a go-to for complex grid tie-ins. Growth is hot, bids are competitive, and execution speed wins; Quanta funds crews, tooling and pre-fab to stay the leader.
Transmission expansion corridors—interregional lines, reconductoring and HV upgrades—are big, complex, capital‑heavy projects where Quanta’s fleet, safety record and permitting expertise give it a clear edge. Quanta reported fiscal 2024 revenue near $11.8 billion, and U.S. transmission investment needs exceed $100 billion through 2030, driven by policy and renewables buildout. Market growth remains strong; doubling down leverages high barriers to entry that keep competitors out.
Data demand in 2024 remains strong as carriers push for speed and scale through dense 5G small-cell builds; Quanta’s multi-market crews and centralized program management shorten cycle times and win multi-year contracts. Growth is robust across markets, though pricing varies regionally, so continued investment in crews and logistics is critical to capture scale economies. Maintain investment to keep cycle times short and secure multi-year awards.
Wildfire hardening and storm response are Stars in Quanta Services' BCG matrix as climate volatility drives sustained resiliency spend; utilities increasingly rely on Quanta’s rapid mobilization and multi-year restoration track record to limit outage duration and costs.
Business shows high organic growth with episodic surges after major events and strong brand equity translating into repeat contracts and higher win rates; operational focus must keep capacity warm and logistics tight to capture volume spikes.
High-growth, high-share Stars: Quanta 2024 revenue ~$16B, backlog >$20B, driven by utility hardening, transmission and renewables tie-ins; invest to defend share and scale capacity. Transmission, solar/wind interconnections and wildfire hardening show double-digit growth; Quanta’s EPC scale and rapid mobilization are competitive advantages.
| Metric | 2024 |
|---|---|
| Revenue | $16B |
| Backlog | >$20B |
| Transmission rev | $11.8B |
| US interconnection queue | 1,000+ GW |
 Detailed Word Document
In-depth BCG Matrix review of Quanta Services units, outlining Stars, Cash Cows, Question Marks and Dogs with strategic actions.

 Customizable Excel Spreadsheet
One-page BCG Matrix for Quanta Services, clarifying portfolio choices and easing executive decisions.
Utility maintenance MSAs are large, recurring contracts in mature markets delivering steady revenue and high share for Quanta; backlog exceeded $9.4 billion as of mid‑2024, supporting predictable margins and low selling costs. These contracts generate strong cash flow to fund growth bets while requiring strict service quality and safety controls and vigilance against scope creep.
Distribution line upgrades and routine rebuilds are mature, repeatable projects with tight playbooks where Quanta leverages scale to keep crews utilized; FY2024 revenue from recurring utility services contributed heavily to cash flow. Low market growth but utilization north of 80% drives steady free cash generation. Continuous optimization of routing, yards, and parts inventory targets incremental throughput and margin gains.
Gas distribution maintenance & integrity is steady, compliance-driven work that generated a recurring backbone within Quanta’s 2024 mix as Quanta reported roughly $17.8B revenue and backlog topping $20B, underscoring dependable demand. Quanta’s national footprint and safety certifications secure high renewal rates and stable contract flows. Margins stay solid from deep experience curves (mid-single-digit operating margins in 2024), and targeted digital inspection investments can nudge margins up ~100 basis points.
Industrial services & plant maintenance deliver stable base-load work across select facilities, showing less cyclicality than EPC swings and maintaining familiar client relationships; these segments remained cash-positive and sticky in recent years, supporting Quanta’s overall liquidity. Keep staffing lean and response times sharp to preserve margins and client retention; focus on recurring contracts and expedited mobilization.
Integrity digs, assessments, and repairs are mandatory spend for operators, creating steady demand that positions Quanta Services as a Cash Cow: crews, QA/QC systems, and safety programs deliver high repeatability and strong margin conversion. Growth is modest but predictable; cash generation funds reinvestment and dividends. Standardizing tooling and data capture cuts rework and improves EBITDA.
Quanta’s utility maintenance, distribution upgrades, gas integrity and industrial services act as Cash Cows: large recurring MSAs gave predictable revenue and high utilization in 2024, with company revenue ~$17.8B and backlog >$20B supporting mid-single-digit operating margins and >80% crew utilization; steady cash funds growth bets and dividends.
| Metric | 2024 |
|---|---|
| Revenue | $17.8B |
| Backlog | >$20B |
| Utilization | >80% |
| Op margin | Mid-single-digit |
The file you're previewing on this page is the exact BCG Matrix report you'll receive after purchase. No watermarks, no demo placeholders—just a fully formatted, analysis-ready document designed for strategic clarity. Once bought it’s instantly downloadable and editable, ready for printing or presenting to your team or clients. Crafted by strategy pros and built for immediate use, there are no surprises—just plug it into your planning and go.
International one-off EPC projects at Quanta occupy a small share (under 5% of revenue) with uneven growth and higher risk profiles, showing volatile year-to-year contribution in 2023–2024. Mobilization costs often eat 5–10% of contract margin and learning curves reset on each project, while cash frequently gets trapped in logistics and delay claims for 3–9 months. Given these metrics and elevated working capital strain, prefer exit or partner-only models.
Legacy copper telecom maintenance is a Dog for Quanta in 2024 as carriers accelerate copper retirements and shift capex toward fiber, compressing network footprints and budgets. Low share in a shrinking pie means truck rolls rarely cover variable costs and typically only break even after overhead. Operational analysis shows redeploying crews to fiber buildouts yields higher utilization and margin improvement, supporting a wind-down of copper teams.
Coal-related infrastructure services face structural decline and regulatory headwinds as US coal generation fell to about 18% in 2023 (EIA), tightening demand and leaving limited project backlog for Quanta. Low market share and high compliance costs make coal work a cash trap with diminishing returns. Divestiture or restricting activity to bundled decommissioning and remediation preserves capital and margin.
Greenfield oil trunkline construction in select regions rates as a Dog: permitting risk, political friction and multi-year cycles create a tough recipe; 2024 permitting timelines often exceed 18 months, shrinking IRR and making project flow scarce.
Share is not compelling where projects are scarce and working capital sits idle during delays; avoid unless risk-sharing and contracted recovery of holding costs are airtight.
Dogs: niche industrial EPC outside core sectors involve small, bespoke jobs with poor repeatability, low brand leverage and high bid costs; change orders commonly erode margins by 200–500 basis points. In 2024 these activities represented a low-single-digit share of Quanta’s backlog, advising prune and refocus on scalable verticals to protect consolidated margins.
Dogs: small, low-growth niches (international one-off EPC, legacy copper, coal services, niche industrial EPC, select oil trunklines) represent low-single-digit backlog share in 2024, deliver volatile margins (often negative after mobilization/holding) and tie up working capital; recommend exit, prune, or partner-only models unless full risk-sharing and hold-cost recovery exist.
| Segment | 2024 share | Key metric |
|---|---|---|
| Intl one-off EPC | <5% | 5–10% mobilization cost |
| Copper maintenance | Low-single-digit | Covers variable cost only |
| Coal services | Negligible | Declining demand |
EV charging infrastructure EPC is a Question Mark: market growing fast but owners fragmented and utilization uncertain; US public chargers reached roughly 200,000 by end-2024 while deployments rose about 35% year-over-year. Quanta can build at scale via its ~$13.8B 2024 revenue platform and national footprint, yet share is not locked without standardization. Returns depend on charger standardization and multi-site programs with fleet or retail partners. Invest selectively with national partners to secure repeatable volume.
Enterprise and campus demand for resilience is increasing as outages rise, and the global microgrid/DER market is estimated to grow at roughly a 12% CAGR through 2030. Market remains early with varied designs and long sales cycles, favoring integrators; Quanta’s system-integration expertise aligns well but its share in microgrids remains nascent. Priorities: scale repeatable design templates and link projects to financing to accelerate adoption.
Grid-scale battery storage is a high-growth Question Mark for Quanta: deployments more than doubled over the five years through 2024, driven by renewables, so technical fit is strong given Quanta’s interconnection and EPC capabilities. Integration complexity—controls, interconnection queues, safety—requires specialized talent and OEM alliances to manage thin construction margins and competitive pressure. Invest in controls engineering and strategic OEM partnerships to scale profitably.
Offshore wind transmission and substations in the U.S. are high-growth but choppy: federal 30 GW by 2030 target drives demand while policy, permitting and supply-chain bottlenecks create uneven cadence. Quanta’s offshore-ready capabilities are forming, not yet dominant; projects are high-capex and long-timeline (Vineyard Wind capex ~2.8B). Measured consortium bets mitigate execution risk.
Rural broadband builds via BEAD and public funds sit as Question Marks for Quanta: the $42.45B BEAD pool and FCC's ~14.5M unserved locations (2023/24) create funding tailwinds, but award timing is patchy and political; Quanta’s scale (≈45,000 employees) helps win large contracts while local contractors keep pockets of share; disciplined execution can be profitable if timelines and permits hold; target clusters where logistics and permitting enable speed.
Question Marks: EV charging (US ~200,000 public chargers end-2024; deployments +35% YoY) and grid storage/microgrids/offshore transmission/BEAD present high growth but uncertain returns. Quanta (2024 revenue ~$13.8B; ≈45,000 employees) can scale but must secure standards, OEMs, financing and repeatable programs to convert them into Stars.
| Segment | 2024 datapoint | Priority |
|---|---|---|
| EV charging | 200,000 chargers; +35% YoY | national partners |
| Storage/microgrids | ~12% CAGR to 2030 | controls talent |
| Offshore | 30 GW by 2030 target | consortiums |
| BEAD | $42.45B; ~14.5M unserved | cluster bids |


