
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
Unlock the full strategic blueprint behind Rambus’s business model with our concise Business Model Canvas—three to five targeted insights show how value is created, monetized, and defended in high‑performance IP and security markets. Ideal for investors and strategists seeking actionable takeaways. Download the complete Word & Excel canvas to benchmark, adapt, and execute faster.
Partnerships with leading fabs like TSMC and Samsung Foundry and OSATs such as ASE and Amkor ensure process compatibility, yield and supply continuity for Rambus memory-interface chips; in 2024 these alliances support rapid ramp and global scale for advanced nodes and 2.5D/3D packaging critical to high-speed, low-power performance, while joint PDK and DFM collaboration reduces risk and time-to-market.
Collaborations with EDA vendors streamline IP integration, verification and timing closure, leveraging pre-validated tool flows and reference designs that cut customer effort and speed time-to-market. Model libraries and VIP improve interoperability across Cadence, Synopsys and Siemens toolchains, which together held about 70% of the EDA market in 2024. Joint support from Rambus and partners accelerates design-ins and tape-outs, aligning with Rambus 2024 revenue of about $576 million.
Close collaboration with DRAM and processor vendors ensures Rambus PHY/IP align to standards such as DDR5 (up to 6400 MT/s), LPDDR5X (up to 8533 MT/s), HBM3 (up to ~819 GB/s per stack) and evolving PCIe/CXL roadmaps. Rigorous interoperability testing elevates system-level performance and reliability. Early access programs shorten integration timelines and de-risk new standards. Joint co-marketing validates solutions for tier-1 OEMs.
Alliances with security IP vendors, certification labs, and standards groups harden Rambus solutions and shorten validation cycles. FIPS is required for US federal use and the Common Criteria Recognition Arrangement covered 31 countries in 2024, driving global adoption. Reference integrations with roots of trust and crypto cores accelerate deployment while joint threat research improves resilience.
OEMs supply co-development input and guaranteed volume demand, while hyperscalers set data center performance targets and TCO benchmarks—top five hyperscalers held roughly 70% of global cloud market in 2024, guiding Rambus priorities. Distributors and design houses expand regional reach across 100+ countries, and joint solution briefs can shorten procurement cycles by up to 30%.
Partnerships with TSMC, Samsung Foundry and OSATs ensure advanced-node supply and 2.5D/3D scale; joint PDK/DFM cuts time-to-market. EDA alliances (Cadence/Synopsys/Siemens ≈70% share in 2024) and OEM/hyperscaler co-development (top5 hyperscalers ≈70% cloud share 2024) accelerate design-ins and demand. Security and standards (FIPS, Common Criteria 31 members 2024) speed validation and global adoption; Rambus 2024 revenue ≈$576M.
| Partner | 2024 Metric |
|---|---|
| Fabs/OSATs | TSMC/Samsung; 2.5D/3D ramp |
| EDA | ~70% market share |
| Hyperscalers | Top5 ≈70% cloud |
| Revenue | $576M |
 Detailed Word Document
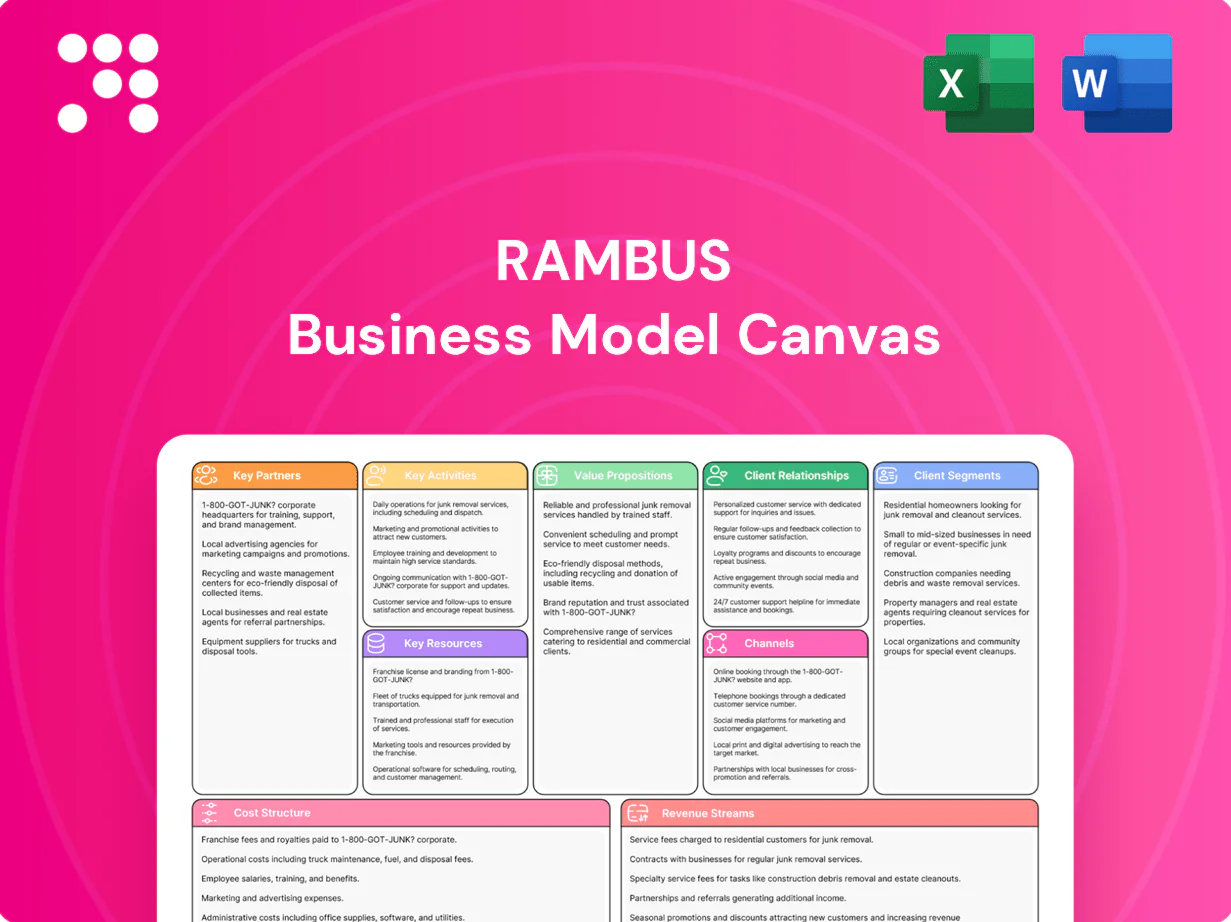
A comprehensive Business Model Canvas for Rambus detailing its nine core blocks—customer segments, value propositions, channels, customer relationships, revenue streams, key resources, activities, partnerships, and cost structure—focused on semiconductor IP, security cores, and licensing strategies; includes competitive advantages, SWOT-linked insights, and investor-ready narratives for strategic decision-making.

 Customizable Excel Spreadsheet
Condenses Rambus’s strategy into a clean, editable one-page snapshot that saves hours of formatting and helps teams quickly identify core components, compare models, and produce board-ready deliverables.
Core R&D advances signal integrity, equalization and training algorithms to support industry PHYs like DDR5 at 6,400 MT/s and SerDes up to 112 Gbps per lane; PHY, controller and SerDes designs target higher bandwidth with lower latency and power. Silicon bring-up validates models and margins in lab and production; continuous innovation aligns with next‑gen standards such as PCIe 6.0 and DDR6.
IP development and licensing operations center on creating synthesizable cores, hard macros and full deliverables that underpin Rambus licensing, supporting billions of deployed devices annually as of 2024. Robust legal, compliance and contract management protect IP value and enforce royalties. Royalty tracking ensures accurate reporting and cash flow from licensed silicon. Customer enablement packages and reference integrations cut integration friction and time to first silicon.
Memory interface IC design moves from prototype to volume production with test, characterization, and reliability screening driving yields; Rambus reported FY2024 revenue of $292 million, underscoring scale. Forecasting and logistics align die supply to demand using rolling 12-month demand plans, while cost optimization (process node and packaging) targets improved gross margins.
Rambus drives standards via active roles in JEDEC, PCI-SIG and the CXL Consortium, shaping specifications and roadmaps. Early compliance testing in Rambus labs builds credibility with OEMs and hyperscalers. Multi-vendor interoperability labs validate cross-platform compatibility; CXL membership surpassed 300 companies by 2023. Public contributions and published test results reinforce thought leadership.
Field engineering provides floorplanning, timing, and SI/PI guidance to ensure Rambus IP fits customer layouts and meets signal and power budgets; reference boards and firmware accelerate evaluation and shorten time-to-first-silicon. Training and documentation support volume ramp, while sustaining engineering closes post-silicon bugs and issues rapidly to protect revenue streams.
Rambus advances PHY/SerDes R&D (DDR5 6,400 MT/s, SerDes 112 Gbps) and silicon bring-up; IP licensing supports billions of devices and drove FY2024 revenue of $292M. Licensing/legal ops secure royalties and enable OEM integrations; field engineering, reference boards and sustaining support shorten time‑to‑silicon and ramps. Standards work (JEDEC/PCI‑SIG/CXL) with CXL >300 members by 2023 underpins interoperability.
| Activity | 2024 Metric |
|---|---|
| Revenue | $292M |
| Licensed devices | Billions deployed |
| R&D targets | DDR5 6,400 MT/s; SerDes 112 Gbps |
| CXL membership | >300 (2023) |
The document you're previewing is the actual Rambus Business Model Canvas, not a mockup or sample. When you purchase, you'll receive this exact file with all sections and formatting intact. The deliverable comes ready to edit and present in Word and Excel formats. No surprises—what you see is what you’ll get.
Rambus's extensive IP in signaling, training and security—backed by thousands of issued patents and applications worldwide as of 2024—drives licensing revenue and valuation. A mix of defensive countersuits and offensive licensing preserves differentiation. Active freedom-to-operate analyses reduce partner implementation risk. Continuous filings and prosecution through 2024 sustain the protective moat.
Expert engineering talent across analog/mixed-signal, digital, verification, and cryptography drives Rambus innovation, supporting product and IP lines that contributed to $504 million revenue in 2024. Cross-functional teams compress development cycles, institutional know-how raises first-pass silicon success, and high talent density attracts strategic semiconductor and cloud customers.
High-speed oscilloscopes and BERTs validate signal margins for 112 Gbps PAM4 lanes used in 400GbE deployments. Environmental chambers and JEDEC-rated reliability rigs (−55°C to 125°C) ensure thermal and mechanical robustness. Interop labs recreate multi-vendor systems and protocol stacks for real-world validation. Automation frameworks integrate with CI pipelines to accelerate coverage and repeatable regression testing.
Rambus's 34+ year track record and leadership in memory and interface standards reduces buyer risk by signaling predictable performance and compliance.
Long-term license and services engagements with 100+ customers create enforced switching costs via integrated IP stacks and multi-year support contracts.
Public, transparent roadmaps and recent design wins across major OEMs align Rambus roadmaps with customer product cycles and validate scalability.
Strong balance sheet funds R&D and tape-outs, with cash and equivalents of $463 million and R&D spend of $129 million in 2024; EDA licenses, VIP suites and emulation platforms sustain development throughput and tape-out velocity. SDKs, models and developer documentation compress customer adoption cycles, while secure repositories ensure IP protection and delivery integrity.
Rambus's IP portfolio (thousands of patents) and security/serdes expertise underpin licensing and product revenue, supporting $504M 2024 revenue. Engineering talent and labs enable high-quality tape-outs; cash $463M and R&D $129M (2024) fund innovation. 100+ licensees and 34+ years of standards leadership drive switching costs and design wins.
| Metric | 2024 |
|---|---|
| Revenue | $504M |
| Cash | $463M |
| R&D | $129M |
| Customers | 100+ |
| Tenure | 34+ yrs |
High-bandwidth, low-latency interfaces unlock data-intensive workloads, enabling real-time AI inference and large-scale training. Power-efficient designs reduce total cost of ownership through lower rack PUE and cooling needs. Proven interoperability ensures reliable deployment across vendors. Roadmaps in 2024 align with accelerating AI and data center expansion.
Rambus shortens time-to-market by delivering pre-verified IP and reference designs that cut integration time, providing known-good silicon to accelerate platform launches, aligning toolchains to minimize rework, and offering expert support to shorten debug cycles.
Embedded security IP and hardware roots of trust protect data in motion and at rest, enabling secure boot, key isolation and encrypted processing while meeting Common Criteria and FIPS 140-2/3 requirements. Compliance with leading certifications eases audits and shortens time-to-market for regulated customers. Hardware-based safeguards mitigate emerging threats and configurable options fit diverse risk profiles across edge, cloud and payment deployments.
Rambus’ early conformance to DDR5, HBM, PCIe and CXL reduces specification risk and accelerates time-to-market; in 2024 Rambus participated in JEDEC, PCI-SIG and the CXL Consortium to align implementations with evolving specs. Multi-vendor validation simplifies procurement and backward compatibility protects prior investments, while active forum participation signals long-term durability to customers.
Total solution flexibility combines IP licensing and ready-to-ship chips, with modular deliverables tailored for ASICs, FPGAs, and SoCs; Rambus reported fiscal 2024 revenue of 234.5 million USD supporting scalable commercial models that adapt to customer size, while support services fill capability gaps across integration and verification.
High-bandwidth, low-latency IP enables real-time AI and large-scale training, reducing TCO via power-efficient designs. Pre-verified IP and known-good silicon shorten time-to-market and integration cycles. Embedded security with FIPS/Common Criteria protects data across edge and cloud. 2024 revenue 234.5M USD supports modular IP+chip offerings and global support.
| Metric | 2024 |
|---|---|
| Revenue | 234.5M USD |
| Standards | JEDEC / PCI-SIG / CXL |
| Certifications | FIPS 140-2/3, Common Criteria |
Long-term co-development engagements with Rambus shape product features and roadmaps across typical chip design cycles of 12–24 months and program horizons of 18–36 months. Joint milestones align tape-outs and launch windows to industry cadence, reducing go-to-market slippage against a global semiconductor market of roughly $600 billion in 2024. Shared, documented test plans standardize validation and materially lower integration surprises, while executive sponsors from both sides maintain accountability and escalate decisions.
Field engineers deliver on-site and remote assistance, supported by ticketing portals and SLA-backed 24/7 coverage; recent industry benchmarks show 95% first-response within one hour and median resolution under 24 hours. Regular design reviews catch integration issues early, reducing rework and accelerating time-to-market. Clear escalation paths resolve blockers quickly, aiming for critical-path clearance within 4 hours.
Workshops and certifications upskill customer teams, with Rambus-enabled programs in 2024 reducing onboarding time by up to 40% in pilot deployments. Detailed technical collateral and playbooks accelerate integration and cut evaluation cycles by weeks. Reference platforms de-risk proofs-of-concept, while ongoing firmware and standards updates track PCIe, HBM and security changes throughout 2024.
Named account managers coordinate internal resources and customer feedback, driving focused action and escalation paths. Quarterly business reviews (QBRs) track KPIs and risks, with joint forecasts aligning supply and demand and improving forecast accuracy by up to 20% (McKinsey 2024). Regular health checks boost satisfaction and reduce service issues.
Developer ecosystem support accelerates Rambus integrations through SDKs, reference models, and application notes that cut engineering time and errors; sample code further reduces implementation effort and testing cycles. Forums and knowledge bases consolidate best practices and troubleshooting; beta programs give partners early access and feedback loops. In 2024 ecosystem engagement rose 28% year-over-year, boosting partner-led deployments.
Long-term co-development aligns 12–36 month programs with a $600B global semiconductor market in 2024, reducing go-to-market slippage. SLA-backed support shows 95% first-response within 1 hour and median resolution under 24 hours. Training cuts onboarding up to 40% in pilots; ecosystem engagement rose 28% YoY in 2024. QBRs and named managers lift forecast accuracy by ~20% (McKinsey 2024).
| Metric | 2024 |
|---|---|
| Market size | $600B |
| First-response | 95% ≤1h |
| Median resolution | <24h |
| Onboarding ↓ | ≤40% |
| Ecosystem growth | +28% YoY |
| Forecast accuracy | +20% |
Named account teams target hyperscalers, OEMs, and semiconductor customers with tailored outreach and strategic coverage. Technical sellers work alongside Rambus engineering to qualify integrations and proofs of concept. Long, relationship-driven sales cycles often span 12–24 months. In 2024, custom commercial terms commonly support large deployments with deal sizes typically exceeding $1M.
IP licensing agreements specify NRE, royalties and permitted usage with clear templates; Rambus reported roughly $116.9M in 2024 licensing-related revenue, illustrating scale of recurring royalties. Multi-year terms align product roadmaps and secure long-term royalties and cross-licensing. Robust legal frameworks and patent portfolios protect IP; self-service portals and automated updates speed deliverables and reduce admin costs.
Regional distributors expand Rambus reach for chips across APAC, EMEA and Americas, while local design houses deliver system integration and customization, shortening deployment cycles. Bundled Rambus solutions reduce buyer friction and accelerate time-to-market. Joint marketing with partners amplifies visibility and drives adoption; Rambus reported roughly $360 million revenue in 2024, underscoring partner-driven scale.
Secure online portals deliver IP, documentation and firmware updates while supporting Rambus’s product-led growth; Rambus reported $473 million revenue in 2024. Catalog listings on ecosystems increase discoverability and partner reach. Self-serve evaluations accelerate trials and analytics from portals inform roadmap and reduce time-to-market.
Industry events and standards forums let Rambus showcase live performance demos at 2024 trade shows, publish technical papers to build credibility, validate readiness in interop plugfests, and secure speaking slots to drive thought leadership.
Named account teams and technical sellers drive 12–24 month, relationship-led deals (typical deal >$1M). IP licensing and legal frameworks enabled $116.9M licensing revenue in 2024; partner channels supported ~$360M and product-led portals ~$473M in 2024, boosting discoverability, self-serve trials and analytics.
| Channel | 2024 metric |
|---|---|
| Named accounts | Deal size >$1M; 12–24mo cycle |
| Licensing | $116.9M revenue |
| Partners | $360M revenue |
| Portals | $473M revenue |
Data center and hyperscale operators demand bandwidth, ultra-low latency and efficiency gains to support AI and cloud workloads, with top hyperscalers spending over $100 billion annually on capex (2023–24). They value proven interoperability at scale to avoid costly integration delays. TCO and power (PUE targets often below 1.2) drive design decisions. Security and compliance remain non-negotiable for multi-tenant AI deployments.
ASIC, CPU, GPU and AI-accelerator teams license PHY and controller IP for predictable integration and signoff, aiming to reduce respins in 12–24 month SoC design cycles. They prioritize PPA and yield metrics to meet performance targets and manufacturing economics. Roadmap alignment with IP vendors shortens validation and decreases late-stage fixes, improving time-to-market.
Networking and telecom equipment makers demand high-throughput, low-jitter interfaces such as 400G (and growing 800G) links to meet bandwidth needs. Carrier-grade reliability requirements — typically 99.999% availability — drive component selection and redundancy design. Standards compliance (IEEE, ITU) simplifies certification and interoperability. Longevity and support matter: typical equipment lifecycles run 7–10 years, influencing procurement and maintenance contracts.
Consumer electronics and embedded OEMs must balance peak performance with power and cost, constrained by form-factor and thermal limits; pre-validated IP speeds time-to-market and reduces integration risk. Security features are essential to protect end users and limit breach costs, which averaged about 4.45 million USD per incident in the 2024 IBM Cost of a Data Breach Report.
Automotive and industrial compute demands functional safety (ISO 26262) and extended reliability for systems with lifecycles often exceeding 10 years; ruggedized performance and thermal resilience are essential for harsh environments. Stable supply and long-term component availability are critical to meet OEM qualification timetables in 2024. Certification support (AEC‑Q, ISO 26262 evidence) shortens qualification and lowers qualification cost and time.
Data centers/hyperscalers (> $100B capex 2023–24) demand ultra-low latency, PUE <1.2 and certified scalability. SoC teams need PHY/controller IP to cut respins in 12–24 month cycles and meet PPA targets. Networking, consumer, automotive segments prioritize 400/800G, security ($4.45M breach avg 2024) and ISO 26262/AEC‑Q with 7–10+/10+ year lifecycles.
| Segment | Key metric (2024) | Priority |
|---|---|---|
| Hyperscale | >$100B capex | PUE<1.2, latency |
| SoC/IP | 12–24m cycles | PPA, respin reduction |
| Networking | 400/800G | 99.999% reliability |
Rambus invested $102.3 million in R&D in fiscal 2024, funding analog/mixed-signal, digital, and security research lines. Prototyping and emulation hardware and lab cycles add material cost and extend development timelines. Talent retention for specialized IC and crypto engineers is strategic and costly. Continuous standards updates (DDR, HBM, security specs) drive recurring R&D cycles.
Wafer, packaging, and test account for roughly 60–80% of chip COGS in 2024, with packaging/test often representing 20–35% alone; active yield-improvement programs have cut scrap rates by up to 40%, materially lowering per-unit costs. Ongoing capital for lab and qualification gear runs on the order of $5–10M annually, while logistics and inventory management typically add another 4–6% of operating overhead.
Licenses for design, verification and signoff (EDA) typically range from $200k to $1M+ per seat annually, representing a major line-item; emulation and compute farms (on-premises and cloud) require multi-million-dollar capital and run-rate spend to support regression; third-party IP incurs licensing/royalty fees tied to unit volumes; secure IT and SOC controls — often 8–12% of IT budgets — protect Rambus assets.
Sales, marketing, and customer support at Rambus drive a pipeline through dedicated account teams, events, and collateral; FAEs support design-ins with in-field engagement while training and documentation require continuous upkeep, and channel programs carry incentive tiers aligned to volume—Rambus reported revenue of 318.4 million USD in fiscal 2024, underscoring commercial scale.
Patent filing and defense drive material costs for Rambus, with US patent prosecution averaging $20,000–$30,000 per file in 2024 and IP litigation often exceeding $1–5 million per major case; certification and audits add recurring tens-of-thousands of dollars to ensure trust; memberships and travel for standards work create ongoing operating spend; contracting and export controls add legal complexity and potential fines.
Rambus cost structure centers on R&D ($102.3M in FY2024), wafer/pack/test (60–80% of chip COGS), and IP/legal (US patent $20–30k/file; litigation $1–5M+). Ops spend includes EDA seats ($200k–$1M+), lab capex $5–10M/yr, and sales/support tied to $318.4M revenue in FY2024.
| Line | 2024 |
|---|---|
| R&D | $102.3M |
| Revenue | $318.4M |
| Wafer/pack/test | 60–80% COGS |
| Lab capex | $5–10M/yr |
Upfront IP licensing fees cover access to cores and deliverables, with per-core license pricing scaled by process node, geography, and end-use; typical core license ranges often fall between $100,000 and $2,000,000 depending on complexity. Option tiers provide add-on features and support, creating recurring uplifts. Non-recurring engineering (NRE) fees, commonly $50,000–$5,000,000, capture customer-specific customization and integration.
Per-unit royalties provide Rambus with ongoing payments tied to customer shipments, forming a predictable stream that scales with end-market demand; in fiscal 2024 Rambus reported $586.7 million in total revenue, with licensing and royalties comprising roughly 40% (~$235 million). Volume tiers in agreements create price breaks that incentivize OEM growth and drive higher aggregate royalties as unit shipments climb. Standardized reporting, quarterly statements, and independent audits are used to verify shipment counts and ensure royalty accuracy.
Revenue from finished memory interface ICs targets servers, networking and OEMs, contributing to Rambus reported 2024 revenue of $615 million; mix-driven margins improved as higher-volume server skus raised gross margin to roughly mid-30s. Long-term supply and licensing agreements stabilized multi-year demand, while spares and device variants provide recurring upsell and higher-margin aftermarket sales.
Annual support and maintenance contracts deliver software/firmware updates and SLAs, with 2024 industry renewal rates averaging ~90%, ensuring recurring revenue. Premium tiers upsell accelerated response and dedicated engineers for higher ARPU. Structured training packages monetize customer enablement and reduce churn. Consultancy services bridge integration gaps and capture project-based margins.
Rambus monetizes Security IP through licensing of crypto engines, root-of-trust cores and secure protocol blocks, leveraging a patent portfolio of over 3,000 patents and applications as of 2024; certification assistance generates recurring service fees, while feature bundles lift average selling prices and managed firmware/patch updates create sustained subscription-like value.
Rambus earns upfront IP licenses ($100k–$2M per core) plus NRE ($50k–$5M), recurring per-unit royalties (licensing/royalties ≈$235M, ~40% of $586.7M licensing-related 2024 mix), finished IC sales ($615M product revenue 2024) and services (90% renewal, managed updates/subscriptions). Revenue mix and volume tiers drive scale and margins (gross margin ~mid-30s).
| Metric | 2024 |
|---|---|
| Total product revenue | $615M |
| Licensing/royalties | $235M (≈40%) |
| Patent portfolio | 3,000+ |
| Renewal rate | ~90% |
| Gross margin | mid-30s% |


