
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
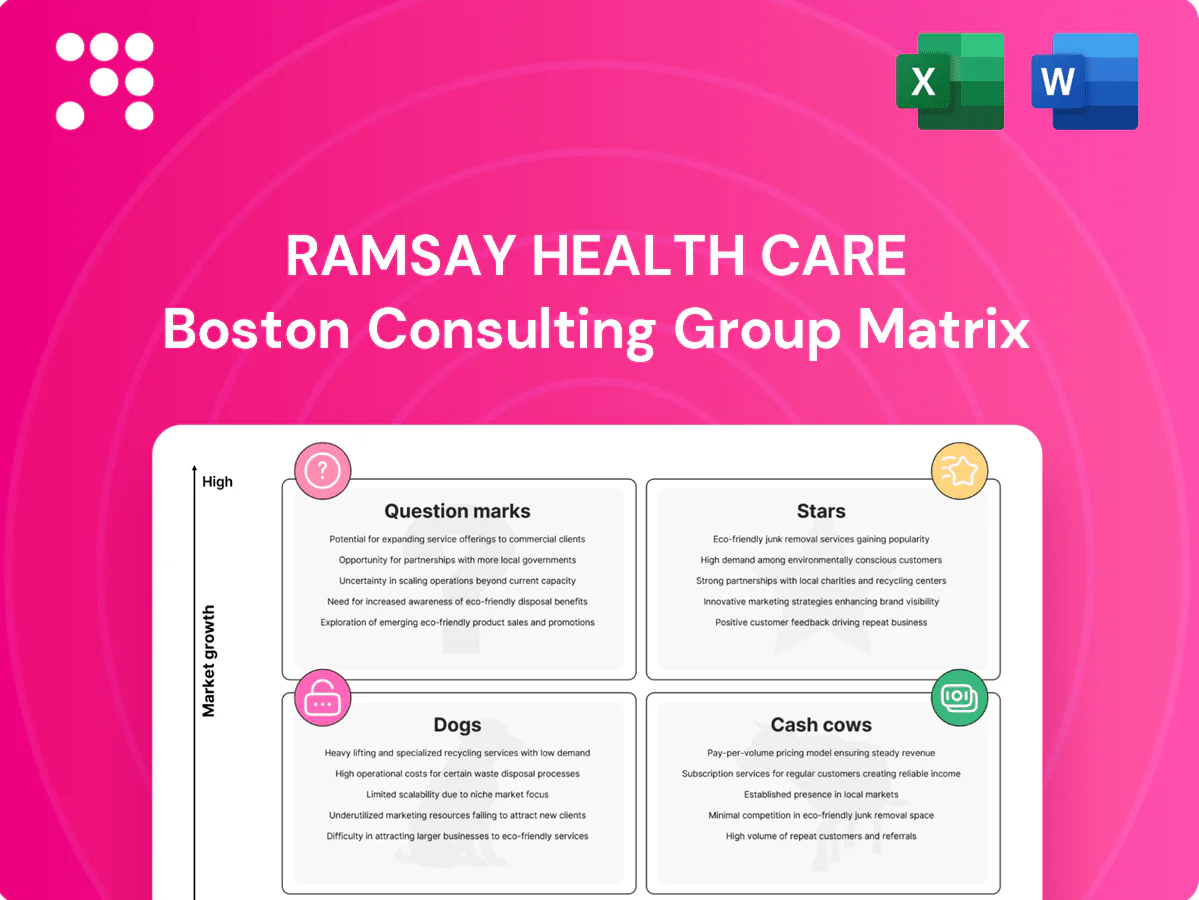
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Ramsay Health Care’s BCG Matrix preview highlights which services are powering growth, which are steady cash cows, and where investments might be stalling—quick, practical clarity for busy leaders. Want the full picture with quadrant-by-quadrant placements, actionable recommendations, and editable visuals you can present? Purchase the full BCG Matrix report for a ready-to-use Word analysis plus an Excel summary and start making smarter allocation and product decisions today.
Mental health services sit in the lead at Ramsay due to high demand, strong reputation and growing referrals in 2024. Capacity is expanding rapidly and requires ongoing investment in clinicians and site development across Ramsay’s international network. Maintain share by prioritizing access, measurable outcomes and brand strength. If momentum persists as the market normalizes, this line can mature into a cash cow.
Elective shifts to same‑day settings are running hot and Ramsay’s network — ~480 facilities across 11 countries — rides that wave, delivering high throughput and patient convenience. Strong payer alignment and ambulatory reimbursement support double‑digit growth in many markets. Scale, scheduling tech and block‑time allocation defend share; invest in dedicated centers and surgeon relationships to capture volume.
Orthopedics, cardiology and oncology are high-acuity, high-ticket specialties where Ramsay, the largest private hospital operator in Australia, is a go-to provider; case-mix depth and specialist rosters create a durable moat.
Procedure complexity and multidisciplinary teams drive higher margins and justify ongoing capital; global 65+ population exceeds 700 million, sustaining brisk demand.
Keep feeding capital into robotics, specialist recruitment and integrated multidisciplinary pathways to capture aging-population growth.
Integrated surgery-to-rehab pathways let Ramsay own the full episode (pre-op, acute, rehab), improving outcomes and retention; seamless bundles are favored by payors and patients and Ramsay’s 2024 footprint of over 490 facilities across 10 countries supports capture. Growth needs coordination tech and tight clinician collaboration; standardised pathways will lock in share.
Imaging capacity underpins elective volumes and faster turns; MRI/CT demand rose in 2024 (≈7% nationally) while subspecialty reads increased, supporting higher revenue per case. Where Ramsay leads locally, share held and grew in 2024, with upgraded sites reporting ~10–15% volume gains. Invest in kit, uptime, and rapid reporting to stay the first choice.
Mental health, same‑day elective and specialist acute care are Stars for Ramsay in 2024: high demand, expanding capacity and strong payer alignment drive double‑digit ambulatory growth. Imaging upgrades (+7% MRI/CT demand; upgraded sites +10–15% volume) and 490+ facilities support scale; continued investment in clinicians, robotics and coordination tech is required to maintain share.
| Metric | 2024 | Implication |
|---|---|---|
| Facilities | 490+ | Scale |
| MRI/CT demand | +7% | Throughput |
| Upgraded sites uplift | +10–15% | Revenue |
 Detailed Word Document
Concise BCG Matrix of Ramsay Health Care: identifies Stars, Cash Cows, Question Marks, Dogs with strategic invest/hold/divest guidance.

 Customizable Excel Spreadsheet
One-page BCG matrix for Ramsay Health Care, pinpointing underperformers to relieve pain and prioritize fixes.
Mature metro private hospitals in Ramsay’s portfolio carry high share in stable, insured markets with reliable occupancy and modest organic growth; Ramsay operates over 480 facilities across 11 countries and reports roughly 4 million annual admissions, underpinning steady revenue streams. Pricing and payer contracts are largely fixed, delivering strong cash generation after maintenance capex and enabling free cash flow optimization. Operational focus on milk efficiency—patient flow and theatre utilization around industry norms—sustains margin conversion.
Rehabilitation hospitals within Ramsay Health Care deliver predictable volumes from surgical pipelines and chronic care, benefiting a group that in FY2024 operated over 480 facilities globally; low market growth but consistent length‑of‑stay supports steady margins. Cash is generated when beds remain occupied—Ramsay’s focus on occupancy preserves free cash flow. Optimising staffing ratios and discharge planning can modestly increase throughput and cash conversion.
In‑hospital pharmacies within Ramsay Health Care leverage captive demand across over 480 facilities (2024), controlling formularies to steer volume and capture repeat scripts post‑discharge. They deliver mature, low‑volatility revenue with decent margins and minimal promotional spend, driven by compliance and convenience. Focus on automation and procurement scale reduces costs and improves throughput.
Established insurer‑funded electives in orthopedics, ophthalmology and general surgery on long‑held contracts deliver steady case flow with low patient switching in mature markets; at Ramsay this reliably covers overheads across its network of over 480 facilities (2024), supporting predictable cash generation. Protecting scheduling priority and surgeon loyalty is key to sustaining this cash.
Mature diagnostics contracts with embedded imaging in long‑running Ramsay sites generate steady volumes and limited growth but solid cash flow; equipment is largely depreciated so uptime directly preserves margin. Prioritise service SLAs and selective refresh cycles to sustain throughput; Ramsay operated over 480 facilities in 2024.
Mature metro hospitals, rehabilitation units, in‑hospital pharmacies, elective orthopedics/ophthalmology and embedded diagnostics across Ramsay’s 480+ facilities (≈4.0m admissions in 2024) generate stable, high cash conversion with low organic growth; depreciated assets and fixed payer contracts underpin predictable free cash flow. Operational focus: occupancy, theatre/utilisation, procurement scale and SLAs to protect margins.
| Metric | 2024 |
|---|---|
| Facilities | 480+ |
| Admissions | ≈4.0m |
| Core cash sources | Metro hospitals, rehab, pharmacies, electives, diagnostics |
The Ramsay Health Care BCG Matrix you’re previewing here is the exact same, final document you’ll receive after purchase. No watermarks, no demo text—just a fully formatted, analysis-ready matrix built for strategic clarity. Once bought, the file is instantly downloadable and editable for presentations, board packs, or internal planning. It’s crafted by strategy pros and ready to plug straight into your work—no surprises, no tweaks required.
Underutilized regional hospitals in Ramsay's portfolio—which spans about 480 facilities across 11 countries with roughly 83,000 staff—sit in low-growth catchments where fragmented market share depresses returns; low theatre utilisation raises unit fixed-costs and margins. Turnarounds require significant capital and time, making these sites prime candidates for consolidation, repurpose, or exit.
Legacy Ramsay facilities, many of the group’s over 480 hospitals across 11 countries (2024), demand heavy capex to close compliance gaps and modernize, draining cash without commensurate revenue growth. Large refurbishment bills show unclear payback horizons and extended ROI timelines. Even break‑even sites lock capital that could fund growth assets. Consider mothballing, sale‑leaseback, or targeted divestment to free liquidity.
Standalone GP clinics within Ramsay sit as low-share Dogs: thin margins unless feeding hospitals and not contributing meaningfully to FY2024 group revenue (Ramsay reported about AUD 13.5bn and operates over 480 facilities across 11 countries in 2024). Marketing spend rises but patient referrals don’t stick, turning clinics into cash traps if isolated. Either embed them into hospital care pathways to drive utilisation or divest/shut.
Non‑core ancillary services (eg peripheral retail) sit far from Ramsay Health Care’s clinical core, rarely achieving scale; management attention often exceeds marginal profit, and they neither grow revenue materially nor defend clinical moat, so they should be trimmed and capital redeployed to core hospital services and high‑margin clinical pathways.
Dogs:
Dogs: underutilised regional hospitals, legacy facilities, standalone clinics and ancillaries drain cash with low growth. Ramsay operates ~480 facilities, ~83,000 staff and reported ~AUD 14.6bn revenue in FY2024. Duplicate back‑office platforms raise OPEX and complexity; consolidate, divest or repurpose to free capital.
| Metric | Value (2024) | Action |
|---|---|---|
| Facilities | ~480 | Consolidate/sell |
| Revenue | AUD 14.6bn | Redeploy capex |
| Staff | ~83,000 | Streamline ops |
Primary care networks present attractive growth tailwinds for Ramsay given rising outpatient demand, but Ramsay's share is small and fragmented relative to its c.500 facilities footprint (2024). They are strategic if they drive referrals and unlock patient data for care pathways. Realising value requires investment in access, digital platforms and clinician incentives. Move to scale fast or fold networks into stronger partners.
Virtual pre/post‑op care is a rapidly growing space and Ramsay’s stake is still early; Ramsay operates about 480 hospitals across 10 countries (2024). It can shorten length‑of‑stay and raise surgical throughput by enabling earlier discharge and more efficient follow‑up. Implementation requires telehealth platforms, remote monitoring devices and pathway redesign. Prioritise deployment where it links directly to core surgical volumes.
Outpatient specialty centers in new geographies sit in a high-growth market—global ambulatory surgery volumes rose ~5–7% annually pre-2024—yet Ramsay’s local share in these markets is small, giving room to scale. De‑risk with hub‑and‑spoke models anchored on existing hospitals to concentrate referrals and optimize OR utilization. Capital‑light rollouts are possible but require brand and surgeon buy‑in; invest selectively to prove unit economics before wider roll‑out.
Data/AI‑enabled care coordination offers big promise for efficiency and outcomes but currently represents a minimal share of Ramsay Health Care’s operational mix; hospital AI deployments remained below 10% in 2024 and surgical cancellation rates globally sit around 5–15%, so impact can be material if realised.
Early implementation requires heavy upfront spend and returns typically lag, yet if AI shortens diagnostics and lowers cancellations the operational flywheel can accelerate volume, margin and patient throughput.
Pilot, measure KPIs (cancel rate, LOS, diagnostic turnaround), then scale where ROI is proven.
Value-based care partnerships are a Question Mark for Ramsay: payers are increasingly testing risk-sharing and the global value‑based care market was ~USD 78bn in 2024, so growth exists but Ramsay’s position remains nascent; its pathway control can be monetised. Delivering this needs advanced analytics, contracting muscle and strong clinical governance; fund a few focused pilot contracts to learn fast.
Question Marks: high-growth adjacencies (primary care, virtual peri‑op, outpatient specialty, AI, VBC) with Ramsay scale c.480–500 facilities (2024); markets growing 5–7% (ambulatory), VBC ~USD78bn (2024); capex-heavy, pilots to prove ROI, scale where cancel rate, LOS, TAT improve.
| Adjacency | 2024 metric | Key KPI |
|---|---|---|
| Scale | 480–500 sites | Market share |
| AI | <10% deployment | Cancel rate 5–15% |
| VBC | USD78bn market | Contract ROI |


