
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
Unlock the strategic blueprint of RATCH Group with our concise Business Model Canvas. This in-depth canvas reveals how RATCH creates value, secures partnerships, and monetizes large-scale power assets. Ideal for investors, consultants, and entrepreneurs seeking actionable, ready-to-use insights. Purchase the full Word & Excel files for a section-by-section breakdown and practical next steps.
RATCH partners with national utilities such as EGAT to secure interconnection and long-term offtake, often under PPAs of up to 25 years. These alliances de-risk projects through transparent dispatch and settlement, aligning with Thailand’s peak demand near 32 GW (2024). Close coordination ensures system reliability and capacity planning and supports expansion into cross-border power trade with neighboring grids.
RATCH partners with experienced EPC firms to secure on-time, on-budget builds, supporting its consolidated fleet of over 4 GW in 2024. Long-term O&M partners target availability above 95% and heat-rate optimization, using performance-based contracts that tie fees to reliability. These contracts align incentives with plant uptime, reducing lifecycle costs and outage risks.
Strategic long-term agreements with gas/LNG suppliers and renewable OEMs secure fuel and performance inputs for RATCH’s generation portfolio. Technology partners supply turbines, inverters, batteries and digital controls, with multi-year service and warranties (commonly 5–15 years) guarding asset uptime. Diversified sourcing stabilizes costs and exposure, using benchmarks like the $132/kWh global battery pack price (BNEF 2023) to guide procurement.
Banks, ECAs and institutional investors provide project finance and refinancing for RATCH, while green and sustainability-linked instruments help lower the cost of capital and meet ESG targets. Joint-venture equity partners spread project risk and expand operational capacity, and capital market access supports scaling the project pipeline and liquidity management.
Early engagement with regulators streamlines permitting and compliance, shortening approval timelines for RATCHs ~4.8 GW generation portfolio (2024) and new projects. Community, landowners, and municipal partners facilitate site access and social license, while targeted educational and environmental programs increase local acceptance. Stable regulator and stakeholder relationships reduce execution delays and cost overruns.
RATCH secures long-term PPAs (up to 25 years) with EGAT and neighbors to serve Thailand’s ~32 GW peak (2024), de-risking revenue. EPC and O&M partners support a ~4.8 GW fleet (2024) with >95% availability targets. Fuel/OEM ties stabilize costs (benchmarked to $132/kWh battery price, BNEF 2023) and financiers provide project and green financing.
| Partner | Role | Key metric |
|---|---|---|
| EGAT/Utilities | Offtake/interconnection | PPA ≤25y; 32 GW peak (2024) |
| EPC/O&M | Build/operate | Fleet ~4.8 GW; >95% avail |
| Suppliers/Financiers | Fuel/tech/capital | $132/kWh (battery 2023) |
 Detailed Word Document
A concise Business Model Canvas for RATCH Group detailing its nine blocks—customer segments (utilities, corporates, markets), value propositions (reliable, diversified power generation), channels, revenue streams (PPAs, spot sales), key resources (plants, grid access), partners (govt, EPCs, lenders), cost structure, and risk profile. Designed for analysts and investors to assess operational strategy, competitive advantages, and growth in renewables and IPP markets.

 Customizable Excel Spreadsheet
High-level view of RATCH Group's business model with editable cells—quickly identify core assets, revenue streams and operational risks to relieve strategic uncertainty and accelerate decision-making.
RATCH identifies sites, conducts feasibility studies and secures land rights for thermal and renewable projects. It manages environmental and social impact assessments (EIA typically 6–12 months) to obtain permits. Grid studies and interconnection applications are coordinated early (system studies often 12–18 months). Stakeholder engagement is continuous throughout development to reduce permitting delays.
RATCH structures bankable PPAs and optimizes debt–equity mixes to support project finance and reduce funding costs, focusing on transactions executed in 2024 that tapped green bonds and sustainability-linked loans (SLLs).
Use of project finance and capital market instruments in 2024 aimed to lower WACC while hedging strategies manage interest-rate and FX exposures.
Disciplined capital allocation steers portfolio growth and prioritizes returns and risk-adjusted investments.
RATCH supervises EPC contractors to ensure quality and safety, enforcing schedule controls and milestone-based payments tied to contractual checkpoints. Commissioning protocols validate output against PPA performance guarantees and warranty metrics, with instruments to record deviations. Lessons learned from each project are integrated into procurement and design standards; as of 2024 RATCH operates a generation portfolio exceeding 5 GW, informing continuous improvement.
Centralized O&M at RATCH maximizes plant availability and operational efficiency through standardized procedures and pooled expertise.
2024 industry studies show predictive maintenance and continuous digital monitoring can cut unplanned downtime by about 50%, improving reliability.
Optimized fuel procurement, dispatch algorithms and contract management enhance margins and unit economics.
RATCH acquires, divests and forms JVs to balance conventional and renewable exposure, recycling capital from mature assets into growth projects; as of 2024 RATCH operated roughly 5.7 GW of equity capacity across Asia and Australia. Geographic and technology diversification—thermal, hydro, wind and solar—reduces regulatory and resource risk while active portfolio rebalancing stabilizes cash flows and supports EBITDA resilience.
RATCH develops sites, secures permits and coordinates grid interconnections; continuous stakeholder engagement shortens timelines. In 2024 it executed project finance transactions using green bonds and sustainability-linked loans to optimize capital structure. Centralized O&M and predictive maintenance (≈50% fewer unplanned outages) support a 2024 equity portfolio of ~5.7 GW.
| Metric | 2024 |
|---|---|
| Equity capacity | ~5.7 GW |
| Predictive maintenance impact | ≈50% downtime reduction |
| Financing | Green bonds & SLLs executed |
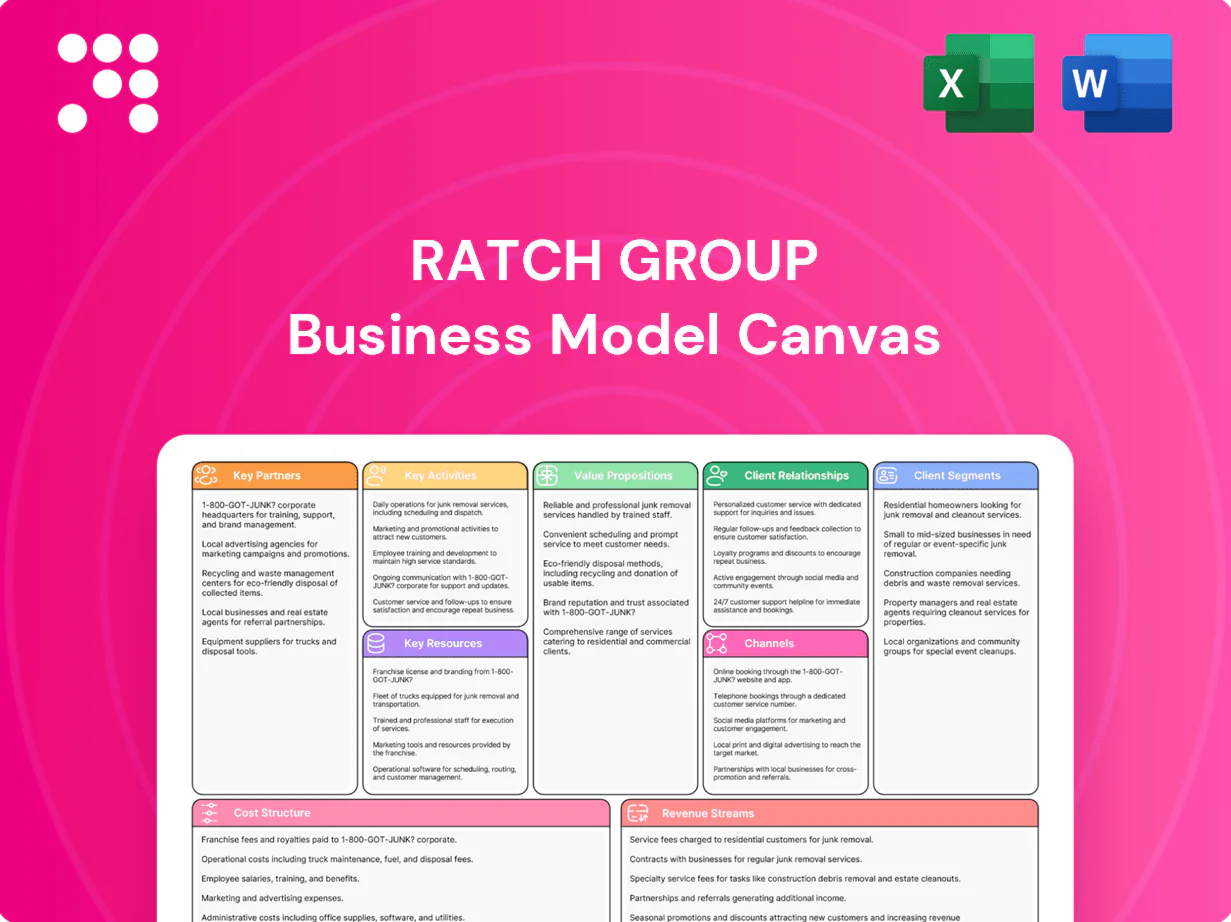
The document you're previewing is the actual RATCH Group Business Model Canvas, not a mockup. It contains the same structured content and strategic segments you'll receive after purchase. Upon payment you’ll download the complete, editable file formatted exactly as shown for immediate use.
Owned and JV power plants constitute RATCHs earnings base, with consolidated installed capacity of 6,443 MW as of 2024 and primary cashflow from thermal and hydro assets.
A pipeline of greenfield and brownfield projects — about 1,500 MW under development in 2024 — supports medium‑term growth and EBITDA expansion.
Diversified technologies span gas, hydro, wind, solar and storage, and a geographic footprint across Thailand, Vietnam, Australia and Laos reduces regulatory concentration risk.
Bankable long-term PPAs underpin revenue visibility for RATCH by providing contract certainty that supports project finance and credit metrics. Capacity and energy payments lock in cash flows over typical 15–25 year tenors, while indexed tariffs (commonly CPI or fuel-price pass-through clauses) mitigate inflation and fuel volatility. Concessions and secured grid access rights guarantee physical delivery and offtake obligations.
Development rights and environmental approvals enable execution, underpinning RATCH Group's portfolio of over 5 GW of generation capacity (2024). Secure land tenure for project sites prevents disputes and costly delays. Water, grid and fuel-access permits are critical enablers for plant operations and expansions. Strong compliance records support competitive positioning for future awards.
Experienced engineers, developers and financiers — over 1,000 personnel in 2024 — drive project delivery and asset optimization across RATCH Group.
Local and international partners expand technical reach and financing options, enabling cross-border renewables and IPP projects.
Dedicated safety and ESG teams protect operations and reputation while governance frameworks ensure disciplined decision-making.
RATCH leverages a strong balance sheet and long-standing banking relationships to lower financing costs, supporting project bids and M&A; installed capacity ~7,000 MW in 2024 underpins revenue visibility. Access to green capital and sustainability-linked facilities in 2024 widened investor pools and reduced cost of capital. Robust hedging lines and liquidity buffers protect against commodity and FX shocks, while a proven project track record sustains competitive bidding.
Owned and JV plants (6,443 MW consolidated; 2024) and ~1,500 MW pipeline (2024) form RATCHs cash‑generating base and growth engine. Diverse tech (gas, hydro, wind, solar, storage) and cross‑border footprint reduce concentration risk. Strong balance sheet, green capital access and >1,000 staff (2024) support bidding, financing and delivery.
| Key resource | 2024 metric |
|---|---|
| Installed capacity | 6,443 MW |
| Pipeline | ~1,500 MW |
| Staff | >1,000 |
| Green capital | Available |
RATCH delivers dependable baseload and mid-merit capacity from a portfolio exceeding 5 GW (2024), supporting reliable supply. Competitive LCOE from efficient operations helps lower system costs and wholesale prices. Plant availability above 92% in 2024 bolsters grid stability. Customers secure predictable, long-term supply through long-term contracts and diverse dispatch capability.
RATCH Group maintains a balanced conventional-renewable mix—over 4 GW of installed capacity as of 2024—reducing intermittency and fuel risk through diversification. Gas-fired plants complement renewables to meet peak and fast-ramping needs while hybrid projects and battery storage deployments underway in 2024 enhance system flexibility. This blend supports Thailand’s energy transition targets by enabling reliable renewable integration and lower emissions intensity.
Bankable long-term PPAs with clear tariffs and indexation (commonly 25-year terms) provide revenue certainty and in 2024 underpinned project cashflows for Thai IPPs. Performance guarantees and equipment warranties backstop delivery and reduce availability risk. Robust compliance, reporting and credit support lower counterparty risk, enabling more efficient financing with longer tenors and lower spreads.
RATCH Group leverages cross-border and infrastructure expertise to accelerate international project delivery, drawing on operational experience in Thailand, Australia, Laos and Myanmar and its listing on the Stock Exchange of Thailand. Familiarity with regional regulatory regimes reduces entry friction and time-to-market for new plants and PPAs. Related infrastructure investments create operational and commercial synergies that let customers access integrated generation, transmission and trading solutions.
RATCH delivers dependable baseload and flexible capacity from a >5 GW portfolio (2024), with plant availability >92% and competitive LCOE supporting lower wholesale costs. Renewables 1,300 MW (2024) plus gas and storage hybrids enhance flexibility and lower emissions intensity. Bankable 25-year PPAs and ESG-aligned green finance provide revenue certainty and cheaper financing.
| Metric | 2024 |
|---|---|
| Installed capacity | >5 GW |
| Renewables | 1,300 MW |
| Availability | >92% |
| PPA tenor | 25 yrs |
RATCH sustains multi-decade PPA partnerships (typically 20–25 years) with utilities and large buyers, anchoring revenue stability; SLAs and performance clauses set clear service levels and penalties. Regular contractual and operational reviews align capacity and dispatch with system needs, and consistent on‑time delivery has reinforced trust across counterparties.
Dedicated key-account teams manage RATCHs top 20 counterparties in 2024, prioritizing rapid issue resolution—median response time targeted at 48 hours—and tailored commercial and technical support. Joint planning sessions coordinate capacity expansions above 500 MW with partners and financiers. Proactive communications, including monthly performance reports, reduce operational surprises and contract disputes.
Routine operational and ESG reporting, aligned with ISSB standards since 2024, builds credibility with lenders and stakeholders. Metering, settlements and independent audits are handled rigorously to ensure accuracy and traceability. Compliance portals centralize documentation and speed due diligence. This level of data transparency underpins project bankability and lowers financing friction.
Structured JV governance at RATCH standardizes decision-making across partners, with defined board rules and approval thresholds to speed project delivery; as of 2024 RATCH remains listed on the Stock Exchange of Thailand (ticker RATCH). Shared investment frameworks align incentives through pro rata funding and KPI-linked returns, while technical committees continuously monitor plant availability and efficiency. Contractual dispute mechanisms and escalation ladders reduce downtime and keep multi‑party projects on track.
Local outreach programs sustain RATCHs social license by funding community projects and health initiatives, reinforcing local acceptance and reducing opposition.
Structured grievance mechanisms ensure concerns are addressed promptly, while employment and targeted training programs boost local economies and skill transfer.
Ongoing dialogue with stakeholders lowers project risk and facilitates smoother permitting and operations.
RATCH secures multi-decade PPAs (20–25 years) with utilities, enforcing SLAs and penalties to protect revenue. Key-account teams cover the top 20 counterparties (2024) with a median 48-hour response target; joint planning for >500 MW expansions is routine. ESG and reporting aligned with ISSB since 2024, and RATCH remains listed on SET (ticker RATCH).
| Metric | 2024 |
|---|---|
| PPA length | 20–25 years |
| Top counterparties | 20 |
| Response target | 48 hours |
| Expansion planning | >500 MW |
| ESG standard | ISSB (since 2024) |
| Listing | SET, ticker RATCH |
RATCH (SET: RATCH) participates in state-led procurement for capacity and renewables, actively bidding in Thailand’s 2024 auction rounds to secure long-term PPAs and concessions. Competitive bidding processes are used to obtain PPAs and concessions that lock in revenue streams and capacity additions. Rigorous prequalification emphasizes RATCH’s operational track record and regulatory compliance, while bid strategy is tailored to portfolio needs and risk-return targets.
Bilaterals with utilities and large industrial users set tailored terms—common C&I PPA sizes run 5–50 MW with tenors of 5–15 years to balance risk and finance. Behind-the-meter and wheeling options expand access across sites and can cut peak costs 10–25%, boosting utilization. Structured tariffs match load profiles hour-by-hour, and deep utility relationships accelerate contract execution and grid connection timelines.
Consortia and alliances unlock scale and expertise, enabling RATCH to bid for larger IPP and cross-border projects that support its c.4.5 GW equity capacity (2024). Conference participation surfaces opportunities and deal flow—regional events in 2024 generated multiple project leads for Southeast Asian PPA and battery storage tenders. OEM and developer networks feed robust pipelines, while ASEAN forums accelerate cross-border deals and regulatory alignment.
Financial markets and investor relations fund RATCH Group growth and signal credibility through equity and debt access on the Stock Exchange of Thailand (SET) in 2024; clear ESG disclosures attract sustainability-focused investors, regular investor updates preserve market confidence, and proactive co-investor outreach enables syndication for larger projects.
Digital platforms and virtual data rooms support due diligence and M&A, with virtual data rooms used in roughly 90% of transactions by 2024, accelerating document review and reducing deal time. Online portals streamline compliance submissions; SCADA portals enable real-time performance sharing across RATCH’s ~3 GW portfolio. Digital tools shorten cross-border collaboration and approvals.
RATCH wins state procurement and bilateral C&I PPAs (5–50 MW, 5–15y) to secure long-term cashflows, leveraging consortia for IPP and cross-border scale. Financial channels (SET listing 2024) and ESG disclosures unlock equity/debt and syndication for c.4.5 GW equity capacity (2024). Digital channels (VDR 90% use; SCADA ~3 GW visibility) accelerate deals and operations.
| Channel | Key metric (2024) |
|---|---|
| PPA sizes/tenors | 5–50 MW / 5–15 yrs |
| Equity capacity | c.4.5 GW |
| SCADA visibility | ~3 GW |
| VDR usage | 90% |
| Market access | SET listing 2024 |
Primary offtakers, notably state utilities such as EGAT, procure capacity and energy under long-term PPAs and prioritize reliability, affordability and regulatory compliance. In 2024 PPAs typically span 10–25 years, aligning with system planning and asset life. Creditworthy single buyers anchor project financing, reducing sponsor risk and lowering effective WACC for RATCH projects.
Grid companies and system operators procure ancillary services and flexible capacity to secure grid balance, demanding high availability and typical primary response within sub-second to 30-second windows. Real-time data transparency via SCADA/PMU with 1–4s telemetry is essential for dispatch decisions. Stability services (inertia, synthetic inertia, voltage support) are increasingly valued as inverter-based resources rise on grids.
Large industrial and commercial users seek price stability and green power, driving demand for direct PPAs and wheeling as tailored solutions; RATCH Group operated over 1 GW of renewables by 2024 to meet this. On-site or near-site projects reduce transmission losses and curtailment, improving delivered energy value. Corporate sustainability targets have sharply increased PPA uptake among C&I clients.
Joint-venture partners and co-investors — developers, funds, and strategic investors — share project risk and returns, prioritizing access to RATCHs project pipeline and high governance standards; co-development with RATCH accelerates scale-up and permits structured exits that recycle capital for new projects in 2024.
Local governments demand resilient, low-emission power and prioritize small-scale grids and distributed infrastructure to support local development. Transparent procurement and competitive tendering are critical for selection; community impact and social license heavily influence decisions. RATCH reported about 5,500 MW consolidated capacity in 2024, positioning it to serve municipalities.
Primary offtakers (EGAT) buy under 10–25 yr PPAs prioritizing reliability and creditworthiness; RATCH had ~5,500 MW consolidated capacity in 2024. Grid operators demand fast ancillary services with 1–4s telemetry and high availability. C&I buyers drove >1 GW renewables PPA uptake in 2024 for price stability and green targets. JVs and funds co-invest to access RATCH pipeline and recycle capital via structured exits.
| Segment | Key Need | 2024 Metric |
|---|---|---|
| State utilities | Long-term PPAs | 10–25 yr |
| Grid operators | Ancillary services | 1–4s telemetry |
| C&I | Green PPAs | >1 GW renewables |
| Investors | Pipeline access | 5,500 MW capacity |
Plant construction, interconnection and storage typically account for the bulk of RATCH Group capex, often exceeding 60% of project spend; utility-scale PV capex in 2024 ran roughly $350–500/kW while incremental storage weight rose as battery pack prices hovered near $132/kWh (BNEF 2023–24). Land acquisition and permitting add significant upfront costs and delays. Technology choices (PV, gas, battery chemistry) drive LCOE and lifecycle O&M, while scale and standardization compress unit costs via learning curves and procurement leverage.
Gas/LNG supply and transport fees remain a dominant cost for RATCH’s thermal units, driving fuel-driven margin sensitivity in 2024. Higher renewable penetration increases intra-day variability and balancing costs as system reserve needs rise. Hedging and long-term fuel contracts continue to manage price volatility, while plant efficiency upgrades lower fuel consumption and operating expense.
Operations & maintenance for RATCH carry recurring costs for staffing, spare parts and scheduled outages; staffing and parts form the bulk of annual O&M outflows. LTSA payments to OEMs are budgeted to secure uptime and capacity availability. Digital monitoring and predictive maintenance cut maintenance spend by about 20% in 2024 industry studies, while safety programs and recurrent training remain core cost drivers.
Interest, fees and covenant compliance materially affect RATCH returns, with Thailand policy rate around 2.75% in 2024 influencing borrowing costs; rigorous covenant tracking reduces refinancing risk. Currency and rate hedges protect USD-linked project cash flows and stabilize EBITDA volatility. Proactive refinancing seeks lower weighted average cost of capital. Construction and operational risks are mitigated through project insurance.
Permitting, audits and reporting consume dedicated staff time and external consultants to meet Thailand and host-country 2024 regulatory schedules; environmental mitigation and continuous monitoring are recurring operational costs tied to plant performance and emissions controls. CSR programs maintain local social license through targeted community investment, while legal and advisory fees secure compliance and transaction readiness.
RATCH capex is concentrated in plant construction/interconnection/storage (>60% project spend); utility PV capex 2024 ~$350–500/kW and battery pack ~$132/kWh (BNEF 2023–24). Fuel (gas/LNG) drives thermal OPEX and margin sensitivity; digital predictive maintenance cut maintenance ~20% in 2024 studies. BoT policy rate ~2.75% shapes financing costs and refinancing/hedges reduce WACC and FX risk.
| Cost Item | 2024 Metric / Note |
|---|---|
| Utility PV capex | $350–500/kW |
| Battery pack | $132/kWh |
| Capex share (construction/storage) | >60% project spend |
| Maintenance savings (digital) | ~20% reduction |
| Policy rate (BoT) | ~2.75% |
Availability-based capacity payments under PPAs deliver stable cash flows for RATCH by linking revenue to contracted capacity and measured performance, reducing merchant exposure. Payments tied to guaranteed capacity and availability metrics align incentives and support predictable EBITDA. Contract indexation to inflation or fuel-price indices preserves real value over multi-year tenors. Such predictable, indexed cash flows enhance bankability and typically lower financing costs for project debt.
Revenues derive from dispatched MWh sold at contracted tariffs or spot market rates, with merchant sales providing upside during high-price periods. Superior heat-rate efficiency in thermal assets improves margins by lowering fuel cost per MWh. Active merchant exposure is managed with hedges and limits to capture upside while containing volatility. Curtailment management and availability optimization protect realized yields.
RATCH leverages its ~6.7 GW generation portfolio to earn ancillary revenues from frequency regulation, spinning reserve and ramping fees, with fast-response storage/hybrid assets cutting response times to sub-second levels and increasing grid-value; in 2024 ancillary and flexibility contracts can contribute double-digit percentages to merchant income, diversifying revenue beyond energy sales and stabilizing cash flows.
RECs, I-RECs and carbon credits monetize RATCHs green output, with certificated sales and offtakes driving higher realized prices; corporate buyers accounted for about 65% of global REC demand in 2024, boosting long‑term contracts. Tax incentives and FITs in Thailand raised project IRRs by several percentage points in 2024, while third‑party verification secured premiums for certified volumes.
Equity stakes in joint ventures and infrastructure projects provide RATCH with steady dividend inflows, while developer fees and operations & maintenance contracts create recurring service revenues; asset recycling through IPP divestments delivers one‑off capital gains and portfolio synergies enhance consolidated returns.
RATCH secures stable availability‑based capacity payments across its ~6.7 GW portfolio, reducing merchant exposure and improving bankability. Energy sales plus merchant volumes and hedges capture upside while ancillary/flexibility revenues reached double‑digit percent contribution in 2024. REC/I‑REC demand from corporates was ~65% of market in 2024; FITs/tax incentives boosted project IRRs by ~3 percentage points in 2024.
| Metric | 2024 |
|---|---|
| Fleet capacity | ~6.7 GW |
| Ancillary revenue | Double‑digit % |
| Corporate REC demand | ~65% |
| FIT/Tax IRR uplift | ~+3 ppt |


