
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
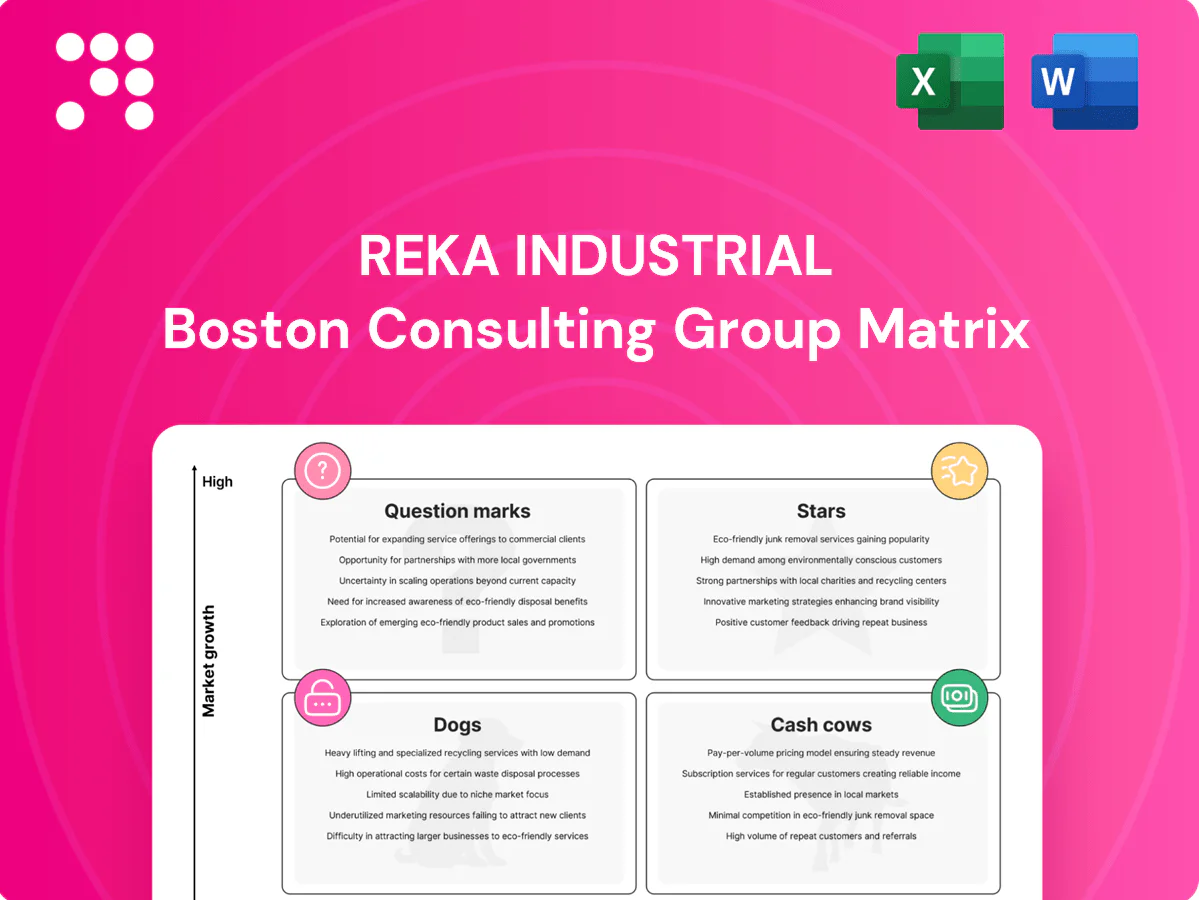
Reka Industrial’s preview shows where a few products fall, but the full BCG Matrix maps every offering into Stars, Cash Cows, Dogs, and Question Marks so you can act with confidence. Get the complete report for quadrant-by-quadrant analysis, clear strategic moves, and data-backed recommendations tailored to Reka’s market realities. Delivered in ready-to-use Word and Excel formats, it’s the shortcut to smarter investment and product decisions. Buy now for instant access and skip the guesswork.
High market growth and Reka’s strong share in Nordic wind/solar interconnect cabling position it as a Star, with the Nordic wind pipeline exceeding 40 GW by 2024 and grid reinforcement spend accelerating. Order books benefit from the 2024 energy transition wave, offering multi-year visibility. The segment demands heavy capex and execution muscle but delivers predictable returns. Continue reinvesting to graduate into future cash cows as growth normalizes.
Stable leader in the expanding Nordic MV cable market as 2024 grid investments reached ~€4.5bn; aging infrastructure replacements sustain demand. Sticky utility relationships and strict qualification barriers protect Reka’s share and support framework agreements. Working capital swings are material—maintain cash buffers for timing and milestone payments. Continue investing in capacity and reliability to lock in long-term frameworks.
Certification-heavy niche serving rail and e-mobility demands compliance with EN 45545, EN 50155 and NFPA 130, creating high entry barriers and strong pricing power. High-spec compounds have low substitution risk and support premium margins, but application engineering for vibration, fire and longevity testing consumes significant R&D and CAPEX. Prioritize partnerships with tier-1 OEMs and scale the compounds portfolio to capture brisk market adoption in rolling stock and electrified infrastructure.
Hyperscale builds in the Nordics accelerated in 2024 with continued expansions from Microsoft, Google and AWS, driving demand for high-quality, reliable power cabling; Reka’s local footprint and proven delivery record win fast-track projects. Projects remain lumpy and capital-intensive, yet the sales pipeline stayed hot in 2024. Priority: double down on delivery speed and project management to convert backlog into cash flow.
Custom cable assemblies tied to multi-year OEM contracts are Stars for Reka Industrial in 2024, with defensible share from design-in and long qualification cycles that raise switching costs and support premium pricing. Growth accelerates as key OEM platforms scale globally, while engineering support and capital-intensive tooling tie up resources and extend payback periods. Continued investment in application engineering and lifecycle support is required to cement lifetime value and renew contract wins.
High-growth Stars: Nordic wind/solar cabling (>40 GW pipeline in 2024) and MV grid spend (~€4.5bn in 2024) give Reka multi-year order visibility; hyperscaler and OEM platform demand accelerates revenue while certification barriers (EN 45545, EN 50155, NFPA 130) protect pricing. Heavy capex and working-cap swings require reinvestment to convert backlog into future cash cows.
| Segment | 2024 metric | Barrier | Action |
|---|---|---|---|
| Wind/solar cabling | >40 GW pipeline | Qualification | Reinvest |
| MV grid | €4.5bn spend | Long contracts | Capacity |
| Hyperscalers/OEM | Large projects | Capex | Delivery speed |
 Detailed Word Document
BCG Matrix review of Reka Industrial units, with clear guidance to invest, hold or divest by quadrant.

 Customizable Excel Spreadsheet
One-page Reka Industrial BCG Matrix placing each business unit in a quadrant to cut decision noise and speed strategy.
Domestic low-voltage building wires are a mature category for Reka with ~40% domestic market share and SEK 1.1bn revenue in 2024, driven by predictable reorder cycles and an ~85% repeat-purchase rate. Efficient plants and established distribution channels delivered a 22% EBITDA margin in 2024, generating strong free cash flow. With market growth ~1.5% in 2024, minimal promotion is required; maintain quality, push automation, and milk the margin.
Repeat formulations for long-standing customers account for >70% of volumes, delivering steady throughput and predictable cash flow. Scale benefits and stable recipes support healthy EBITDA margins around 12–18% in 2024. Innovation needs are low, focused on cost, service and process tweaks; scrap targets of 1–2% and optimized runs can boost free cash flow. Bank the cash and reinvest selectively into efficiency.
Framework contracts and recurring MRO demand keep Reka Industrial’s utility maintenance and replacement cabling lines busy, providing predictable order flow and revenue stability. With logistics tightening eased versus 2021–22 peaks—container freight rates fell roughly 60–70% by 2024—margins settle at a decent, low‑volatility level. Growth is muted but dependable; maintaining service levels and on‑time delivery is critical to preserve share.
Legacy PVC-based cable families remain widely specified in existing buildings and public tenders, delivering steady volume demand and low churn. Tooling investments are fully amortized, producing strong cash conversion and high gross margins while compliance costs are known and manageable. Strategy: keep products compliant, avoid major capex, and harvest profits.
Owned installer relationships and high service reliability create moat-like repeat business across the Nordic market (population ~27.7 million in 2024), underpinning predictable cash flows. Volume discounts plus efficient drop-ship logistics compress unit costs and boost margins. Market growth is slow while churn remains low; sustaining service KPIs and incremental route-to-market tweaks preserve cash-cow status.
Reka Industrial’s cash cows (domestic LV wires, repeat formulations, MRO cabling, legacy PVC cables) generated stable SEK 1.1bn+ in 2024 with ~40% share in LV wires and EBITDA margins 12–22%, driving strong free cash flow and low reinvestment need. Growth ~1–1.5% in 2024; focus on automation, service KPIs and selective efficiency reinvestment to sustain margins.
| Product | 2024 Rev (SEK) | Market share | EBITDA% | Growth 2024 |
|---|---|---|---|---|
| LV wires | 1.1bn | ~40% | 22% | 1.5% |
| Formulations/MRO | — | — | 12–18% | ~1% |
The file you’re previewing is the exact Reka Industrial BCG Matrix you’ll receive after purchase — no watermarks, no demo content, just the finished, professionally formatted report. It’s crafted for clarity and strategic use, ready to edit, print, or present. Buy once and download immediately; the full document will land in your inbox with no surprises and no extra work needed.
Commodity export cables into price-war regions face low growth and brutal pricing with no brand advantage, squeezing margins and leaving cash tied up in receivables for thin returns. Turnaround rarely pays given commoditization and global overcapacity, so salvage often costs more than exit. Shrink exposure or exit these markets to preserve capital and redeploy into higher-margin segments.
Obsolete PVC formulations face declining demand and mounting compliance drag as 2024 regulatory tightening (REACH updates and growing state-level bans) raises certification costs. Re-tooling CAPEX for low-VOC or phthalate-free grades would likely exceed marginal returns. Products show little differentiation and shrinking margins, so sunset SKUs and redirect capacity to specialty thermoplastics with clearer regulatory trajectories.
Legacy rubber hose SKUs see shrinking industrial use as customers in 2024 shift to newer materials and designs with better lifecycle and regulatory profiles. Small, erratic batch orders clog production and planning, raising unit costs and volatility. Many SKUs barely reach break-even; prune the tail and retain only profitable runners to stabilize margins and capacity.
Far-flung APAC micro-accounts deliver low share and near-zero growth without heavy local investment; 2024 contribution was under 1% of group revenue with a 2020–24 CAGR around 0–1%. Logistics inflate costs, eroding gross margins by roughly 15–20% and degrading service quality. These pockets act as cash traps, tying up working capital and warrant consolidation to a few partners or withdrawal.
One-off, engineering-heavy custom jobs tie up lines and typically increase shop-cycle time by ~30%, destroy throughput and leave Reka with weak pricing power once costs are sunk; learning-curve benefits are minimal, so projects erode margin and capacity.
Commodity cables, obsolete PVC grades and legacy hose SKUs are low-share, low-growth with heavy margin pressure from commoditization and regulatory drag; prune or exit. Far-flung APAC micro-accounts contributed under 1% of group revenue in 2024 with 2020–24 CAGR ~0–1% and logistics cost hit ~15–20%; consolidate or withdraw. One-off custom jobs raise shop-cycle time ~30%—accept only at premium with ≥50% prepayment.
| Segment | 2024 metric | 2020–24 CAGR | Impact | Action |
|---|---|---|---|---|
| APAC micro-accounts | Under 1% rev (2024) | ~0–1% | Logistics +15–20% cost | Consolidate/exit |
| Custom jobs | — | — | Shop time +30% | Premium pricing, ≥50% prepay |
EV charging cables and assemblies sit in a rapidly growing but fragmented market—global electric car stock hit about 14.2 million in 2023 and public chargers exceeded ~1.8 million (IEA 2024), creating strong demand. High-spec compliance (IEC 62196, ISO 15118) and certification drive customer stickiness and margin premiums. Significant investment in testing labs, OEM partnerships and scale is required. With a few key OEM or utility wins this can flip to Star quickly; without them, divest.
Offshore wind array and export cable entry sits in a booming market with a global pipeline >300 GW in 2024, but incumbents dominate and upfront capex is heavy—roughly $3–5 million per MW for array plus export cable in 2024. Early bids may secure pilot contracts rather than scale; winning volume requires demonstrated project credibility and disciplined risk management. Strategy: go big with a strong partner or pause to avoid drifting toward Dog territory.
Customers increasingly demand greener footprints—66% of buyers in 2024 prioritized sustainability—yet B2B adoption of recycled/low-carbon rubber is uneven, driven by sector-specific risk tolerance. Technical performance proof remains the primary barrier; independent trials and certifications are essential. Development cash burn is material, commonly USD 5–15m for scale-up and testing. Focus on 2–3 anchor applications to validate economics and secure offtake.
Smart cable with embedded sensing is promising for utilities and data centers — global data center infrastructure spend reached about $230B in 2024, driving demand for real-time monitoring — but the tech is early-stage and industry standards remain fluid.
Hardware-software integration increases complexity and total cost of ownership; sales cycles typically span 12–24 months for utilities/data centers, so pilot aggressively with marquee clients to build reference value.
International OEM co-development programs are Question Marks for Reka Industrial: they offer high upside via platform lock-ins but Reka currently holds a low share and faces high upfront engineering costs and slow ramp. Returns depend on full platform lifecycle volumes and price erosion over time. Selective investment is required where BOM position is defensible and long-lived (2024 focus).
Question Marks: EV cables, offshore/export cable, low‑carbon rubber and smart sensing show high growth potential (EV stock ~14.2M; public chargers ~1.8M; offshore pipeline >300GW; data center spend ~$230B in 2024) but require heavy capex, certifications and OEM wins; selective, partner-led investment to convert to Stars, otherwise divest.
| Opportunity | 2024 signal | Action |
|---|---|---|
| EV/Offshore/Green/Smart | High demand, high capex | Partner, pilot, defend BOM |


