
Digital download
Access the files immediately after checkout.
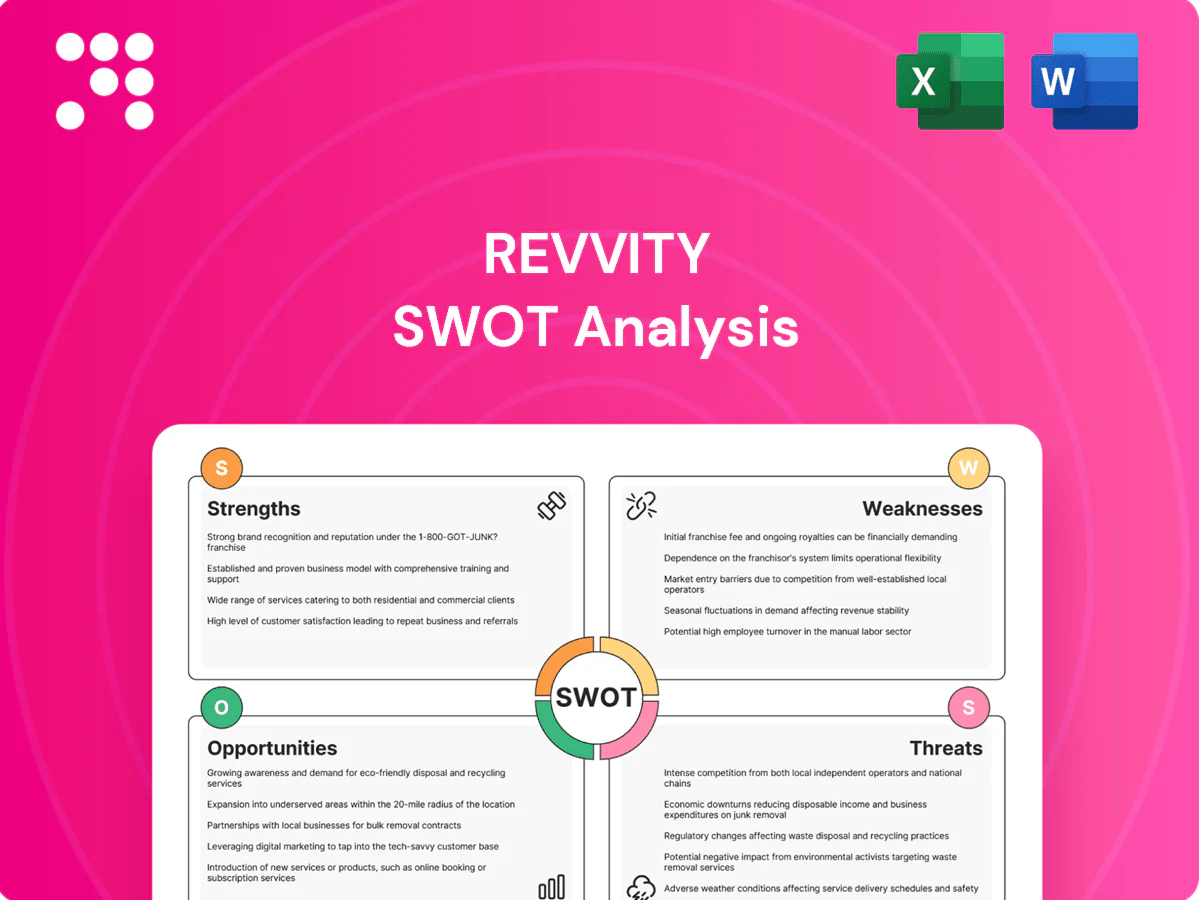
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Revvity SWOT Analysis highlights core strengths in diagnostics and life-science tools, alongside market risks and growth opportunities in precision medicine. Want the full picture with actionable insights and financial context? Purchase the complete SWOT for an editable, investor-ready report to plan, pitch, or invest with confidence.
Revvity offers reagents, instruments, software and services across discovery-to-diagnostics, creating one-stop coverage that supported cross-selling into pharma, diagnostics, academic and government accounts and helped drive FY2024 revenue of about $4.1B; this breadth deepens account penetration, raises switching costs, and enables bundled workflow solutions rather than isolated point products.
Revvity’s capabilities across NGS, assay reagents, protein analysis and high‑content imaging align with a multi‑omics market growing ~15% CAGR to 2030; Revvity reported roughly $4.2B revenue in FY2024, with consumables/services driving majority recurring sales, supporting premium pricing, sticky workflows and platform standardization across labs.
Revvity's large installed base drives repeat reagent and kit purchases, with consumables and services representing over 50% of reported FY2024 revenue of about $3.6 billion, underpinning steady aftermarket demand. Services and software subscriptions deliver higher-margin, predictable cashflows, cushioning macro volatility versus pure capital-equipment peers. This recurring mix boosts customer lifetime value and retention, improving revenue visibility.
Revvity's exposure across pharma, diagnostics labs, academia and government lowers customer concentration risk and smooths demand cycles while geographic diversity spreads regulatory and funding risk across regions; its global distribution and service networks enable cross-market leverage and local teams accelerate adoption and technical support.
Combining instruments with analytics and informatics creates differentiated workflows that streamline lab processes, while integrated data improves outcomes and speeds decision-making across research and diagnostic use cases. Services augment customer capacity and regulatory compliance, embedding Revvity into critical workflows and raising barriers to entry through recurring revenue and platform stickiness.
Revvity generated about $4.1B revenue in FY2024, with consumables and services accounting for over 50% of sales, driving recurring, higher‑margin cashflows. Its integrated instruments, reagents, software and services create sticky workflows and strong cross‑selling across pharma, diagnostics, academia and government. Exposure to a multi‑omics market growing ~15% CAGR to 2030 supports platform demand and pricing power.
| Metric | Value |
|---|---|
| FY2024 revenue | $4.1B |
| Consumables & services | >50% |
| Multi‑omics CAGR (to 2030) | ~15% |
 Detailed Word Document
Provides a concise strategic assessment of Revvity’s internal strengths and weaknesses and external opportunities and threats to inform competitive positioning and growth strategy.

 Customizable Excel Spreadsheet
Provides a concise Revvity SWOT matrix for fast alignment across R&D-driven units; visual, editable formatting streamlines strategic updates and creates stakeholder-ready summaries for quick decision-making.
Revvity is exposed to cyclical academic grants and biopharma budgets—U.S. federal R&D via NIH hovers near $49 billion, creating boom‑and‑bust funding windows. Capital equipment orders are lumpy and tied to grant/fiscal timing, so slowdowns elongate sales cycles and defer upgrades. That variability pressures revenue visibility and reduces factory utilization, increasing working capital strain.
Clinical diagnostics face rigorous validation and approvals—FDA 510(k) review is targeted at 90 days while complex pathways and PMAs can extend well beyond a year—raising time-to-market and development costs. Evolving IVDR requirements (full transition by May 2027) and stricter post-market surveillance and quality systems increase ongoing burden and can delay launches, ceding share to faster competitors.
Managing a wide catalog risks operational complexity, increasing costs and slow time-to-market as platforms and SKUs multiply. Ensuring interoperability across instruments and software demands sustained investment in R&D and engineering. Product overlap can dilute R&D focus and marketing clarity, and integration missteps have the potential to erode customer experience and retention.
Revvity depends on limited sources for critical components and reagents, creating single‑point vulnerabilities where supply disruptions can halt production or delay shipments. Rapid technology shifts risk making current platforms obsolete, and vendor concentration increases bargaining leverage against Revvity.
Revvity faces boom‑and‑bust grant cycles (U.S. NIH ≈ $49B in 2024) and lumpy capital orders that elongate 6–12‑month sales cycles, pressuring revenue visibility and utilization. Regulatory complexity (IVDR full effect by May 2027; FDA pathways often >90 days) raises time‑to‑market and costs. Supplier concentration and single‑source reagents amplify production and delivery risk.
| Metric | Value |
|---|---|
| NIH funding (2024) | $49B |
| Demo/pilot cycle | 6–12 months |
| IVDR deadline | May 2027 |
This is the actual SWOT analysis document you'll receive upon purchase—no surprises, just professional quality.
The preview below is taken directly from the full SWOT report you'll get; purchase unlocks the complete, editable version.
You're viewing a live preview of the real file—buy to download the full, structured report immediately.
Rising demand for NGS, proteomics and single-cell workflows is expanding consumables and platform spend as the global NGS market targets roughly $22B by 2030 (CAGR ~13%). Integrated end-to-end workflows position Revvity to capture enterprise-wide standards and recurring consumables revenue. Growth in companion diagnostics and translational research (companion diagnostics ~ $8.9B in 2023) enlarges TAM, while tailored panels and assays support higher ASPs.
Revvity can capture expanding analytics, QC assays and release testing as the cell and gene therapy pipeline tops 3,000 programs, driving demand for specialized instruments and assays. Closed, automated workflows improve reproducibility and throughput, reducing lot-to-lot variance. GMP-grade reagents and services carry premium pricing, and strategic partnerships with biopharma can secure multi-year supply contracts.
Informatics that interpret omics and imaging data reduce customer bottlenecks and accelerated adoption in 2024 across pharmaceutical and clinical labs. Cloud delivery enables scale and recurring revenue, shifting customers toward subscription models and predictable ARR. AI tools can differentiate performance and outcomes, and integrated data platforms create stickiness and clear upsell paths.
Labor shortages and cost pressures are accelerating demand for Revvity lab automation, driving adoption of standardized, end-to-end workflows that boost throughput and regulatory compliance.
Retrofitting kits for installed instruments create recurring revenue opportunities while service, qualification and validation offerings expand wallet share and margin stability.
Rising healthcare and research investment in Asia-Pacific (estimated $2.5 trillion market in 2024) and accelerating MEA spending (6–8% CAGR) expands Revvitys addressable market and demand for diagnostics and lab solutions.
Localized manufacturing and distribution reduce costs and improve access, while collaborations with pharma, CROs (global CRO market ~ $58B in 2024), and health systems speed commercial adoption.
Public-private initiatives and regional funding programs (multi-year grants and PPPs totaling billions annually) create funded pathways for deployments and scale.
Rising NGS/proteomics and single-cell demand (NGS ~$22B by 2030, CAGR ~13%) plus companion diagnostics (~$8.9B in 2023) expands consumables and platform spend, favoring Revvity’s end-to-end workflows. Cell and gene therapy growth (3,000+ programs) and GMP reagents drive premium services and multi-year contracts. Informatics, automation and retrofit kits create recurring ARR and higher wallet share across APAC (~$2.5T 2024) and CROs (~$58B 2024).
| Metric | Value |
|---|---|
| NGS market | $22B by 2030 (CAGR ~13%) |
| Companion diagnostics | $8.9B (2023) |
| Cell & gene programs | 3,000+ |
| APAC market | $2.5T (2024) |
| CRO market | $58B (2024) |
In 2024 scaled peers with revenues in the tens of billions compete on breadth and price, enabling aggressive cross-subsidization and bundling that undercuts specialist vendors. Rapid M&A in 2023–24 has consolidated customer options and expanded incumbent footprints. Resulting share capture pressures Revvity’s margins and win rates, forcing pricier sales or higher investment to defend contracts.
Cost containment in healthcare is squeezing diagnostic pricing as global health expenditure tops roughly $10 trillion annually, forcing providers to seek lower-cost assays and instruments. Tender dynamics in public procurement have compressed vendor margins—reports show price reductions often reaching double digits—intensifying competitive pressure. Shifts in reimbursement policies and delayed coverage decisions routinely slow clinical adoption of new tests while customers increasingly demand lower total cost of ownership across workflows.
Shortages in chips, plastics or reagents can stall Revvity production lines, extending lead times and increasing per-unit costs. Volatile freight and logistics markets raise transportation expenses and delivery risk, compressing margins. Reliance on single-source parts amplifies supply exposure, while supplier quality failures can force recalls and inflict reputational and financial damage.
Rapid shifts in sequencing, imaging and assay modalities can outpace Revvity’s product roadmap, risking customers delaying purchases until next‑gen platforms arrive; Revvity reported approximately $3.1B revenue in FY2024, heightening exposure if new offerings miss market windows.
High R&D intensity creates risk of misallocated spend and slower returns, and failure to keep pace erodes the relevance of an installed base and recurring consumables revenue.
Cloud-connected instruments widen Revvity's attack surface, and breaches can cause operational downtime, regulatory fines and erosion of customer trust; IBM Security's 2024 Cost of a Data Breach Report put the global average breach cost at $4.45 million.
Revvity faces margin pressure from scale competitors and 2023–24 M&A enabling aggressive bundling and price cuts. Global health spending ~$10T (2024) and double‑digit tender reductions compress diagnostic pricing and delay adoption via reimbursement shifts. Supply shortages (chips/plastics/reagents) and logistics volatility raise costs and lead times. Cloud‑connected instruments increase breach risk; IBM 2024 avg breach cost $4.45M; >130 privacy laws.
| Metric | Figure |
|---|---|
| FY2024 revenue | $3.1B |
| Global health expenditure (2024) | ~$10T |
| Avg data breach cost (IBM 2024) | $4.45M |
| National data/privacy laws | >130 |
| Public procurement cuts | Double‑digit |


