
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
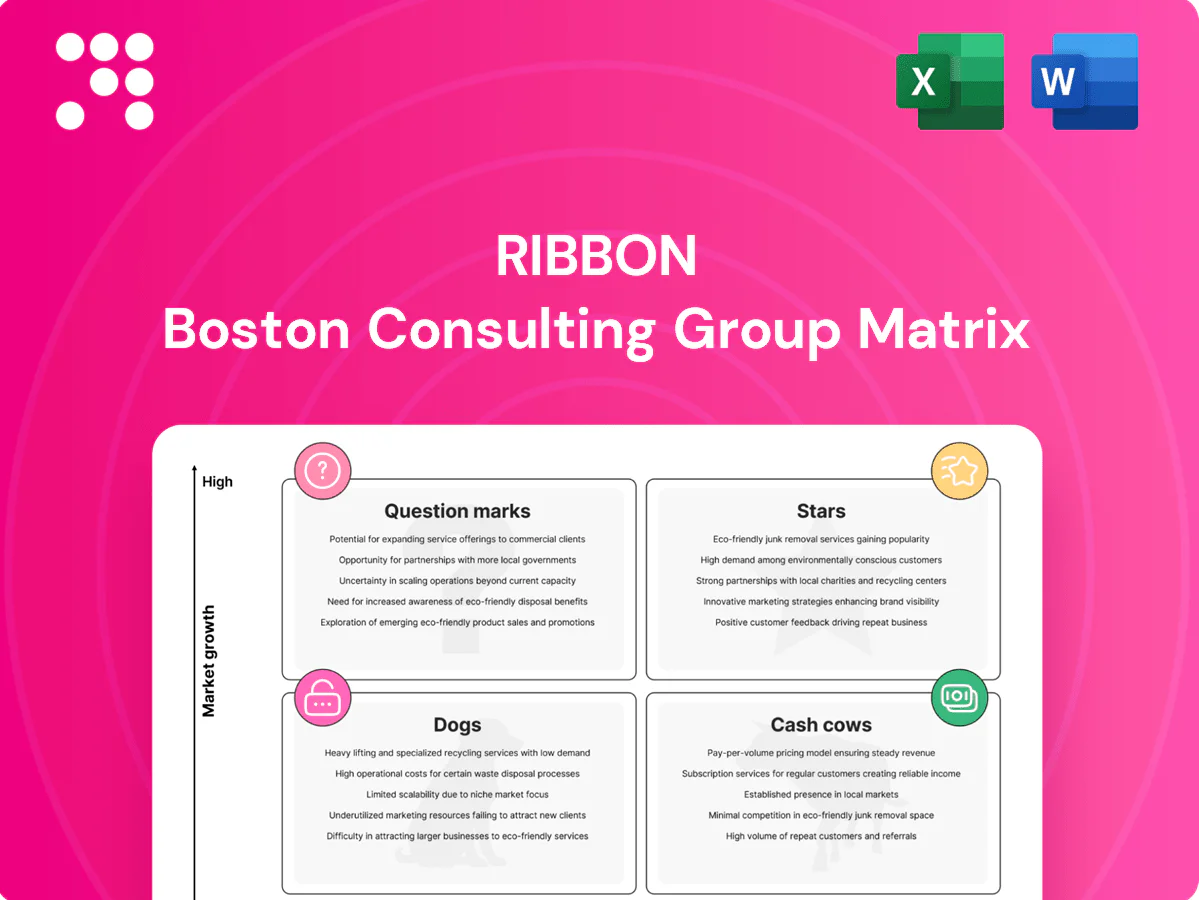
Peek at Ribbon’s BCG Matrix and you’ll spot early signals—who’s winning market share and who’s bleeding cash. This snapshot hints at Stars, Cash Cows, Dogs and Question Marks, but the full report maps every product to a quadrant with data-backed moves. Buy the complete BCG Matrix for quadrant-level strategy, clear investment priorities, and presentation-ready Word and Excel files. Get it now and cut straight to smart, actionable decisions.
Session Border Controllers are core to secure voice/video at carrier and enterprise scale with a strong installed base; Ribbon’s SBCs anchor service provider and large-enterprise deployments. The market keeps growing as UCaaS—estimated at about $40 billion in 2024—and SIP trunking expand alongside 5G voice, with global 5G subscriptions topping roughly 1.5 billion in 2024. Continue investing in features, cloud-native performance, and global certifications to hold share now and mature into tomorrow’s cash cows.
High-capacity IP+optical platforms ride the backbone wave—5G rollout, fiber upgrades and hyperscaler peering—as the optical transport market reached roughly $12B in 2024 (Dell'Oro), driving brisk demand. Ribbon is well-entrenched with service providers and critical infrastructure, translating into steady bookings and deployment wins. Growth and capex are strong but competitor budgets have surged; prioritize performance, automation and open interoperability to maintain leadership.
Voice firewalls, fraud prevention and DDoS protection are red-hot in 2024 as threats to RTC spike, driving demand for integrated SIP/session defenses. Ribbon’s footprint and carrier-grade presence position it to win large multi-domain, often seven-figure, deals by bundling voice, SBC and analytics. Adoption is accelerating but it’s an arms race on features and AI-driven analytics. Keep feeding the roadmap and partner ecosystem to lock leadership.
Operators and enterprises are shifting to containers and cloud ops; CNCF 2024 found 92% of respondents run containers in production, and Ribbon’s cloud-native SBC and automation toolset align directly with that curve. Demand is expanding rapidly while competition from cloud-native rivals is intense. Double down on performance at scale and seamless migration to convert trials into standardization.
VoNR/IMS interconnect and policy-driven routing are scaling with 5G rollouts; global 5G subscriptions grew >30% in 2024 to ~1.8 billion, driving Tier‑1 and national carrier RFPs where Ribbon is already in active conversations. Growth is high and contracts are sticky (typical 3–5 year terms), though integration lift is heavy—continue investing in standards leadership and turnkey delivery teams.
Ribbon’s SBCs, IP+optical platforms and security stack are Stars: market growth drivers with UCaaS ~$40B (2024), optical ~$12B (2024) and global 5G subs ~1.8B (2024). Strong carrier entrenchment and cloud-native traction (CNCF 92% containers prod) underpin high growth and sticky contracts; invest in cloud performance, automation and standards to convert share into scale.
| Metric | 2024 |
|---|---|
| UCaaS | $40B |
| Optical | $12B |
| 5G subs | ~1.8B |
| CNCF containers | 92% |
 Detailed Word Document
Ribbon BCG Matrix: quadrant-by-quadrant strategic insights to invest, hold or divest, with competitive and trend context.

 Customizable Excel Spreadsheet
One-page BCG matrix that maps business units fast—ready for presentations and decision-making, no clutter.
Maintenance & Support Contracts: large installed base delivers dependable, high‑margin annuity streams—industry gross margins for support often 60–70% and renewal rates typically 85–95% in 2024. Growth is modest but predictable; focus on SLAs, proactive monitoring and automated remediation to drive upsell to premium tiers and reduce churn. Stable cash funds R&D and strategic bets.
Enterprise Voice Gateways remain a cash cow: 2024 market growth is low single digits (~2–3% CAGR) but enterprise demand for SIP/TDM interop and branch survivability keeps share solid and vendor gross margins healthy (typical 30–50%). Focus on supply-chain efficiency, regular software updates, and a tight portfolio (under 10 core SKUs) to maximize margins while guiding customers to cloud-friendly upgrades over a 3–5 year migration window.
Design, migration and deployment around core products generate steady, predictable revenue—professional services utilization typically runs 70–80% in 2024, supporting stable cash flows rather than hypergrowth. Standardized playbooks and reusable accelerators cut delivery time and protect healthy services margins (often mid‑teens to low‑20s). Use delivery engagements to seed and validate future product expansions.
Policy & Routing Software remains a cash cow: session routing, numbering and interconnect control are must-haves in mature networks; growth is limited while adoption is broad—enterprise SIP/UC penetration exceeded 70% in 2024—so focus on reliability, compliance and light feature additions; low push, high yield economics with steady license and support revenue.
Installed perpetual licenses deliver steady cash via upgrades and limited add-ons; as of 2024 maintenance typically yields ~18% of original license value annually, keeping legacy revenue stable despite a largely saturated market. The installed base is sticky, so prioritize maintenance and security patches over heavy new-feature work. Convert customers when market timing and cloud economics align; collect cash until then.
Cash cows: support contracts yield 60–70% gross margins and 85–95% renewals (2024); enterprise voice gateways grow ~2–3% CAGR with 30–50% margins; services utilization ~70–80% supporting mid‑teens margins; policy/routing steady with >70% SIP/UC adoption. Preserve reliability, optimize costs, extract annuities while funding strategic cloud moves.
| Category | 2024 metric | Margin | Strategy |
|---|---|---|---|
| Support | 85–95% renewals | 60–70% | Upsell, automate |
| Voice GW | 2–3% CAGR | 30–50% | SKU focus |
| Services | 70–80% util. | 15–25% | Standardize |
The Ribbon BCG Matrix you’re previewing is the exact file you’ll receive after purchase. No watermarks, no placeholders—just the full, professionally formatted strategic matrix ready to use. Purchase delivers the same document instantly to your inbox for editing, printing, or presenting to stakeholders. Simple, transparent, and ready for action.
Pure TDM gateways sit in a shrinking market as PSTN shutdowns accelerate (UK PSTN withdrawal planned by Dec 2025) and enterprise budgets shift to IP and cloud services, with cloud communications markets exceeding $20 billion in 2024. Ribbon’s TDM share and growth lag IP product lines; avoid chasing large rebuilds—prioritize managed support and careful sunset planning. Free up inventory and engineering bandwidth to accelerate cloud/SIP transitions.
Single‑tenant, hardware‑locked On‑prem Only Bundles are losing to cloud‑ready offers as 92% of enterprises used cloud in 2024 (Flexera), while on‑prem server revenue fell ~5% YoY in 2024 (IDC). Low demand, severe price pressure and little differentiation compress margins and limit TAM. Retain only for contractual niche commitments; otherwise plan a measured phase‑down.
Custom SKUs for tiny segments sap operations and add little revenue; SKU rationalization programs in 2019–2024 benchmarks cut SKU counts by about 25% and lowered operational costs roughly 8–12%, while freeing engineering capacity. These low‑margin hardware variants neither grow nor differentiate; retire long‑tail builds and prioritize scalable, common platforms to improve gross margins and simplify supply chain.
Third‑party gear resale traps working capital and compresses margins in a low‑growth segment; it lacks leverage to improve pricing or scale, so Ribbon should steadily wind down resale SKUs and redirect buyers to Ribbon‑led solutions, keeping resale only when it unblocks a strategic deal.
Dogs:
Dogs: legacy regional contracts and TDM resale consume resources for low return—18% of contracts yield <5% margins and occupy 22% of field hours in 2024; TDM market shrank as PSTN exits accelerate (UK PSTN withdrawal planned by Dec 2025) while cloud comms topped $20B in 2024. Wind down noncore SKUs, convert to standardized offers, and reallocate field time to cloud/SIP growth.
| Metric | 2024 |
|---|---|
| Regional low‑margin contracts | 18% |
| Average margin | <5% |
| Field hours tied | 22% |
| Cloud comms market | $20B+ |
AI-driven voice fraud analytics sits in an exploding problem space—FTC reported consumer losses from imposter scams exceeded $1.3B in 2023—yet the field is crowded with startups and point tools. Ribbon's proprietary call data and domain context provide a defensible advantage if it invests in models, telemetry, and closed-loop remediation. If adoption or ROI lags, partner with platform players or pivot to bundled services.
Cloud comms platforms scaled rapidly in 2024, with CPaaS vendors like Twilio reporting $3.86B revenue in 2023 and industry forecasts showing ~25% CAGR through the decade, making interop critical. Ribbon can position as the trusted backbone for quality, security and routing, winning land deals, then templating and replicating deployments. If attach rates remain low, pivot to carrier-first channels to protect margin and churn.
Private 5G backhaul & edge demands deterministic transport and secure interconnect as enterprises test low-latency, SLA-driven fabrics; market value reached roughly $8 billion in 2024 with ~30% projected CAGR through 2029. Potential is large but share formation continues, so Ribbon should pilot aggressively with lighthouse logos and systems integrators to shorten cycles. Use KPIs and stage-gates; kill quickly if sales cycles stall beyond defined thresholds (eg 12–18 months).
Zero‑trust frameworks are migrating from IT to real‑time comms (RTC); 2024 surveys show ~55% of enterprises piloting RTC zero‑trust controls while the market remains early and definitions fuzzy. Ribbon should codify reference architectures with partners and standards bodies, invest now to shape protocols, and monitor for clear vertical traction and measurable ROI.
NetOps teams want cloud dashboards, intent policies, and self‑healing for RTC/IP networks; Observability & Automation SaaS sits as a Question Mark in Ribbon’s BCG matrix with strong demand but incumbent positions not entrenched. 2024 surveys show pilot adoption rising rapidly; build usage‑based modules tied to existing deployments and scale aggressively if adoption curves exceed 30% quarter‑over‑quarter; otherwise bundle lightly.
Ribbon's Question Marks show strong demand but unclear share: voice fraud (consumer losses $1.3B in 2023) and CPaaS tails (Twilio $3.86B 2023, ~25% CAGR) need heavy investment in models/interop; private 5G (~$8B 2024, ~30% CAGR) and RTC zero‑trust (55% enterprises piloting 2024) require pilots with lighthouse customers; scale only if adoption/ROI thresholds met (eg QoQ >30% or sales cycles <18 months).
| Market | 2024 signal | Action | KPI |
|---|---|---|---|
| Voice fraud | $1.3B loss (2023) | Invest models/telemetry | ROI, attach rate |
| CPaaS | Twilio $3.86B | Platform partnerships | Attach % |


