
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Rich Products Corp. combines private ownership, broad frozen-food portfolios, and global distribution as key strengths, while facing intense competition, commodity cost exposure, and innovation pressures. Opportunities include premiumization, foodservice recovery, and emerging markets, but supply-chain risks and shifting health trends pose threats. Want the full story and actionable steps? Purchase the complete SWOT analysis for a professionally formatted, editable report and Excel matrix.
Rich Products, founded in 1945, offers toppings, icings, bakery and seafood across frozen and refrigerated categories, serving customers in more than 100 countries. This breadth lowers dependency on any single segment or season and enables cross-selling into foodservice, retail and in-store bakery channels. The diversified portfolio enhances resilience against category-specific downturns and demand shocks.
Rich Products serves customers in over 100 countries with established cold-chain logistics, enabling consistent frozen and chilled delivery across regions. Global reach spreads demand and currency risk across markets while allowing rapid rollout of product innovations into multiple territories. Broad international access strengthens bargaining power with suppliers and large retail and foodservice customers.
Rich Products leverages deep, longstanding foodservice and in-store bakery relationships—company founded 1945 and present in 100+ countries—to shape product design and formats that match operator workflows. Operational know-how yields ready-to-use, labor-saving solutions that reduce prep time and labor cost for customers. Menu integration and training support create stickiness, while consistency and reliability remain decisive B2B differentiators.
Rich Products' solution-oriented innovations since its 1945 founding support premium positioning; its R&D emphasizes texture, stability and convenience tailored to frozen/refrigerated formats and serves customers in 100+ countries. Customer co-creation shortens time-to-market and the active pipeline helps defend margins against commoditization.
Rich Products leverages deep cold-chain proficiency to manage frozen and refrigerated SKUs, ensuring strict temperature-controlled logistics and QA across its global supply network. These capabilities create high barriers to entry for smaller rivals, while consistent shelf-life performance and quality build strong buyer trust and reduce spoilage. Efficient cold-chain operations lower waste and improve service levels for retail and foodservice customers.
Rich Products (founded 1945) operates in 100+ countries with a diversified frozen/refrigerated portfolio across bakery, toppings, icings and seafood, reducing single-segment risk. Deep cold-chain and QA create high entry barriers and reliable shelf-life performance. Customer co-creation and focused R&D on texture, stability and convenience accelerate product-market fit and defend margins.
| Metric | Fact |
|---|---|
| Founded | 1945 |
| Geographic reach | 100+ countries |
| Core strengths | Cold-chain, R&D, customer co-creation |
 Detailed Word Document
Provides a concise SWOT analysis outlining Rich Products Corp.'s internal strengths and weaknesses and external opportunities and threats to assess its strategic positioning, growth drivers, and future risks.

 Customizable Excel Spreadsheet
Provides a concise SWOT matrix for Rich Products Corp., enabling fast visualization of strengths, weaknesses, opportunities, and threats to streamline strategic alignment and relieve decision-making bottlenecks.
Cold-chain refrigeration, storage, and specialized transport materially elevate operating costs for Rich Products, which reports roughly $4 billion in annual revenues, squeezing margins when logistics spend rises. U.S. industrial electricity averaged about 11–12 cents/kWh in 2023, and energy price volatility further pressures operating margins. Complexity raises spoilage/write-off risk—industry estimates place refrigerated-losses in the single-digit to low-double-digit percentages—limiting price competitiveness in value tiers.
Toppings, icings and bakery inputs face acute price-based competition as private-label penetration in bakery and refrigerated categories nears 20% in the US (IRI, 2024), squeezing brand premiums. Regional players and store brands pressure margins, forcing frequent SKU refreshes to avoid consumer trading down. Procurement teams increasingly prioritize cost—68% of CPOs cited cost reduction as top priority in 2024 (Deloitte)—reducing leverage for brand-driven pricing.
Heavy exposure to restaurants and in-store bakeries ties Rich Products’ performance to traffic trends; food-away-from-home accounted for over 50% of U.S. food spending in 2023 (USDA ERS), so downturns hit volumes. Macroeconomic slowdowns and shifts to at-home consumption can quickly damp demand. Persistent kitchen labor shortages raise demand for simpler SKUs, and menu simplification cycles often displace specialty items.
Ingredient volatility—sugar, dairy, wheat and seafood—remains a material weakness for Rich Products as 2023–24 El Niño and ongoing supply disruptions tightened markets, raising purchase costs and availability risk; hedging reduces exposure but cannot remove price swings, and pass-through of cost increases often lags, eroding margins.
Operating across more than 100 countries exposes Rich Products to diverse food safety, labeling and import rules, driving higher compliance costs and frequent audits that burden operations.
Reformulations to meet local standards and ingredient restrictions increase R&D and production complexity across 70+ manufacturing sites, while recalls or non‑compliance incidents can materially damage brand trust and customer contracts.
High cold-chain and energy costs squeeze margins at roughly $4B revenue; U.S. industrial electricity ~11–12¢/kWh (2023). Private‑label penetration near 20% and >50% food-away-from-home exposure raise volume and pricing risk. Ingredient volatility (sugar/dairy/wheat) from 2023–24 El Niño and 100+ country compliance add complexity and recall risk.
| Metric | Value |
|---|---|
| Revenue | $4B |
| Countries | 100+ |
| Facilities | 70+ |
| Private-label | ~20% |
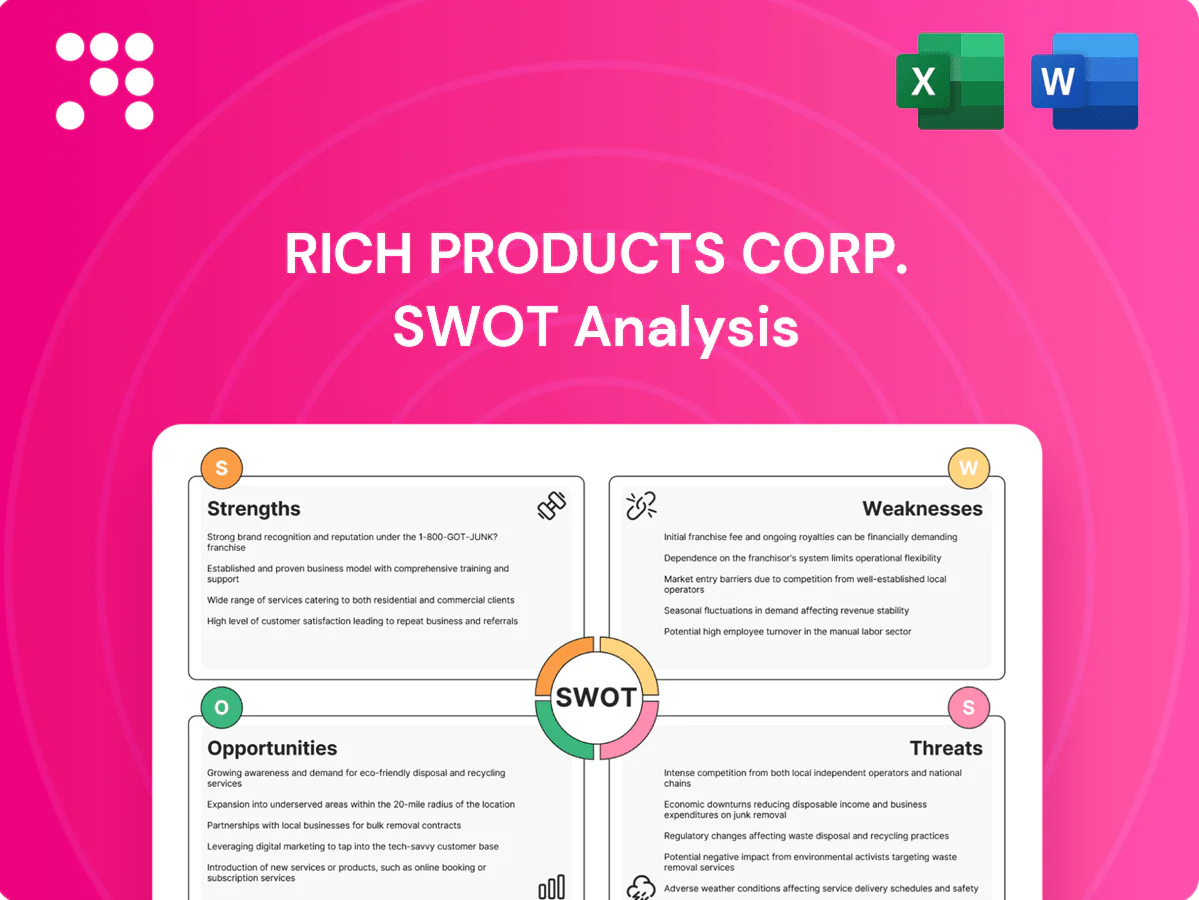
This is the actual SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. It outlines Rich Products Corp.'s strengths, weaknesses, opportunities and threats with concise, actionable insights. Purchase unlocks the full, editable report.
Demand for labor-saving, ready-to-finish and thaw-and-serve items is rising as operators seek consistent results with fewer skilled staff; the global frozen bakery market was valued at about 43.7 billion USD in 2023, signaling strong category momentum. Portion-controlled, waste-reducing formats can cut kitchen waste and boost adoption while premium convenience products support higher margins and better AUVs for operators.
Developing better-for-you, reduced-sugar and allergen-friendly lines can capture wellness-oriented buyers and leverage Rich Products’ scale (about $4.5B revenue in 2022) to drive incremental sales. Clean-label reformulations and transparent sourcing strengthen brand equity; Label Insight found 94% of consumers more likely to be loyal to brands that disclose ingredient details. Nutrition-forward SKUs can expand retail presence and private-label wins.
Rising cold-chain capacity supports frozen bakery and dessert growth, with the global cold chain market reaching about $267 billion in 2023 and forecasted mid-single-digit CAGR to 2030. Urbanization (UN DESA: ~57% urban in 2023) fuels modern retail and QSR expansion, increasing outlet density and frozen SKU demand. Localized flavors can boost adoption by matching regional tastes, while strategic joint ventures and distributors accelerate market entry and scale.
Digital ordering for foodservice and in-store bakeries is scaling, supported by global e-commerce reaching about $6.4 trillion in 2024, and Rich Products can capture rising online procurement. Enhanced portals with data-driven recommendations can increase wallet share through personalized upsells; integration with distributor platforms improves SKU visibility and ordering efficiency. Analytics enable tailored promotions and more accurate demand forecasting, reducing waste and improving fill rates.
Sustainability edge—lower-carbon logistics, recyclable packaging and food-waste reduction—aligns with buyer priorities amid 2019 UNEP 931 million tonne global food‑loss estimate and US EPA 63 million ton food-waste figure (2018).
Rising demand for labor-saving frozen bakery and thaw‑and‑serve items (global frozen bakery ~$43.7B in 2023) and better‑for‑you lines can drive premium growth and margins. Expanding cold‑chain capacity ($267B global market 2023) and digital ordering (global e‑commerce $6.4T 2024) boost distribution and forecasting. Sustainability and certifications support tender wins and premium pricing.
| Metric | Value |
|---|---|
| Frozen bakery market (2023) | $43.7B |
| Cold‑chain market (2023) | $267B |
| Global e‑commerce (2024) | $6.4T |
| Rich Products revenue (2022) | $4.5B |
Intense competition from global CPGs, regional bakeries and growing private labels—which now often reach double-digit penetration in many grocery categories—squeezes Rich Products’ shelf space and pricing power. Price wars and promotional intensity compress margins, while distributor consolidation (favoring large-scale players) raises negotiating leverage against midsized suppliers. Low switching costs on commodity SKUs increase churn and pressure volume-based margins.
Geopolitics, pandemics and extreme weather have repeatedly disrupted inputs and logistics, with ocean schedule reliability still near 50% in 2024, lengthening transit and lead-time variability that complicates production planning. Reefers face tight capacity as cold-chain demand rose about 7% in 2024, delaying deliveries and increasing spot rates. Cold-chain failures can drive losses—vaccine and perishable waste up to 25% reported in some studies—and inflict reputational and financial damage.
Sugar taxes now exist in over 50 countries and several US municipalities, cutting sugary product volumes 10–20% in many markets, while EU and WHO-backed trans-fat rules (eg EU 2g/100g limit) and stricter labeling reduce demand for legacy items. New seafood traceability and sourcing rules raise supply-chain costs an estimated 2–5%, allergen incidents can trigger multi‑million‑dollar recalls and litigation, and rapid compliance shifts strain R&D and operations.
Refrigeration-dependent operations make Rich Products highly sensitive to electricity cost volatility; energy spikes directly raise COGS, while EU carbon pricing near €90/tonne in 2025 can lift operating expenses and shift margin dynamics; infrastructure outages risk rapid inventory spoilage and sunk costs.
Trends toward fresh, artisanal, and scratch-made offerings can displace frozen options, while demand shifts to novel dessert formats and alternative toppings force Rich Products to defend shelf relevance; social media can rapidly amplify negative or viral preferences. Keeping pace requires continuous R&D and marketing investment to avoid market share erosion.
Intense competition (private label penetration often >10%) and distributor consolidation compress pricing and margin. Logistics shocks persist—ocean reliability ~50% (2024) and cold‑chain demand +7% (2024)—raising lead times and spot costs. Regulation and taxes (sugar levies in 50+ countries; EU carbon ~€90/t mid‑2025) and shifts to fresh/artisanal products erode frozen demand.
| Threat | Key metric |
|---|---|
| Private labels | >10% penetration |
| Logistics | Ocean reliability ~50% (2024) |
| Cold‑chain strain | Demand +7% (2024) |
| Regulation | EU carbon ~€90/t (mid‑2025) |


