
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Riskified's Porter's Five Forces snapshot highlights competitive intensity, buyer power, supplier dynamics and substitute threats shaping its fraud-prevention moat. It surfaces key market pressures and strategic risks for merchants and partners. This brief hints at strategic levers and vulnerabilities. Unlock the full Porter's Five Forces Analysis to get force-by-force ratings, visuals and actionable recommendations.
Hosting, compute and storage come largely from hyperscalers—AWS, Azure and GCP held about 65% global cloud market share in 2024—concentrating supplier leverage. Pricing shifts or reserved-instance commitments (discounts up to ~72%) can swing unit economics and slow model-training cadence. Multi-cloud reduces lock-in but raises operational complexity and costs. Hyperscaler outages (minutes–hours) directly impair transaction-decisioning SLAs.
Riskified depends on device, IP, identity and consortium feeds to enrich models; key KYC/AML, telco and email-risk feeds are often proprietary, giving suppliers pricing power and concentration risk. Loss of a high-coverage feed can materially shift the precision/recall balance and raise false-decline rates. Negotiating volume-based, multi-year contracts and diversification of feeds helps contain COGS volatility and supplier leverage in 2024.
PSPs, gateways and card networks control routing and data access, with Visa and Mastercard together accounting for roughly 80% of global card transaction volume as of 2024. Preferred-partner status is often conditional and revocable, creating material dependency risk for vendors like Riskified. Integration priority from PSPs shapes enterprise RFP win rates, and interchange or network-rule changes demand rapid supplier-aligned adjustments.
Specialized MLOps, annotation, and feature‑tooling vendors slow model delivery velocity; switching stacks is costly because pipelines, SKUs, and governance tie into engineering workflows, and 2024 estimates place the enterprise MLOps market near $5B, increasing vendor leverage. Proprietary SDKs and schemas raise stickiness and bargaining power; open-source alternatives cut vendor leverage but shift costs to internal maintenance and compliance.
Security, compliance, and telemetry vendors (PCI assessors, SOC providers, SIEM vendors) supply essential certifications and continuous monitoring, creating timing leverage through annual audit and renewal cycles that can delay remediation or drive dependency.
Contractual price hikes or scope expansions directly press on gross margins, while multi-vendor redundancy and vendor-neutral telemetry reduce individual suppliers' negotiating power.
Supplier leverage is high: hyperscalers (AWS/Azure/GCP ~65% cloud share in 2024) and card networks (Visa+Mastercard ~80% volume) create concentration risk; MLOps market ~$5B (2024) and proprietary feeds/SDKs raise switching costs and margin exposure.
| Supplier | 2024 metric |
|---|---|
| Hyperscalers | 65% cloud share |
| Card networks | ~80% volume |
| MLOps | $5B market |
 Detailed Word Document
Concise Porter's Five Forces analysis tailored for Riskified, revealing competitive intensity, buyer and supplier influence, barriers to entry, substitutes, and emerging threats to its fraud-prevention market position.

 Customizable Excel Spreadsheet
Relieves analysis bottlenecks with a concise Riskified Porter's Five Forces one-sheet that maps fraud risk, competitor pressure, supplier/buyer leverage and regulatory threats—ready to drop into decks for faster, board-ready strategic decisions.
Large enterprise retailers run competitive RFPs across leading fraud platforms, leveraging their scale to demand volume discounts and outcome-based pricing; in 2024 e-commerce accounted for roughly 22% of global retail sales, concentrating negotiating power. Referenceability in verticals like fashion, electronics and travel strengthens buyer leverage, and contract length plus SLAs are often drafted buyer-favorable.
Integrations remain non-trivial, but merchants reported a 2–6% uplift in approval rates from fraud-platform deployments in 2024, making ROI measurable; side-by-side A/B tests with carve-outs let retailers migrate incrementally and materially lower perceived switching risk; improving data portability and API normalization cut integration friction year-over-year by roughly 15% in 2024, tempering vendor lock-in and increasing buyer leverage.
Buyers increasingly demand pricing tied to approvals, chargeback rates, or GMV, shifting performance risk onto Riskified and amplifying buyer bargaining power. Industry chargeback rates typically run about 0.5–1%, making performance guarantees material for merchants. Guarantee constructs force Riskified to post capital and reserves, which buyers negotiate aggressively. Transparent dashboards enable continuous benchmarking and contract re‑pricing against peers as GMV exceeds $5 trillion globally.
Merchants can choose PSP-native stacks (Stripe processed over $1 trillion TPV in 2020; Adyen reported ~€303 billion TPV in 2022), build in-house teams, or use hybrid models, and the presence of credible alternatives in 2024 strengthens buyers’ leverage. Dual-sourcing becomes common to sustain pressure on pricing and innovation, while vertical-specific platforms (marketplaces, travel) further expand viable options and negotiating power.
Large retailers leverage scale to force outcome-based pricing and discounts; e‑commerce was ~22% of global retail in 2024, concentrating buyer power. Measurable ROI (2–6% approval lift) and demand for approval/chargeback‑tied fees (chargebacks ~0.5–1%) amplify bargaining strength. PSP alternatives and ~15% lower integration friction in 2024 reduce vendor lock‑in and enable dual‑sourcing.
| Metric | Value |
|---|---|
| Approval lift | 2–6% (2024) |
| False-decline rate | 1–2% (2024) |
| Chargeback rate | 0.5–1% |
| e‑commerce share | ~22% (2024) |
| Integration friction | -15% YoY (2024) |
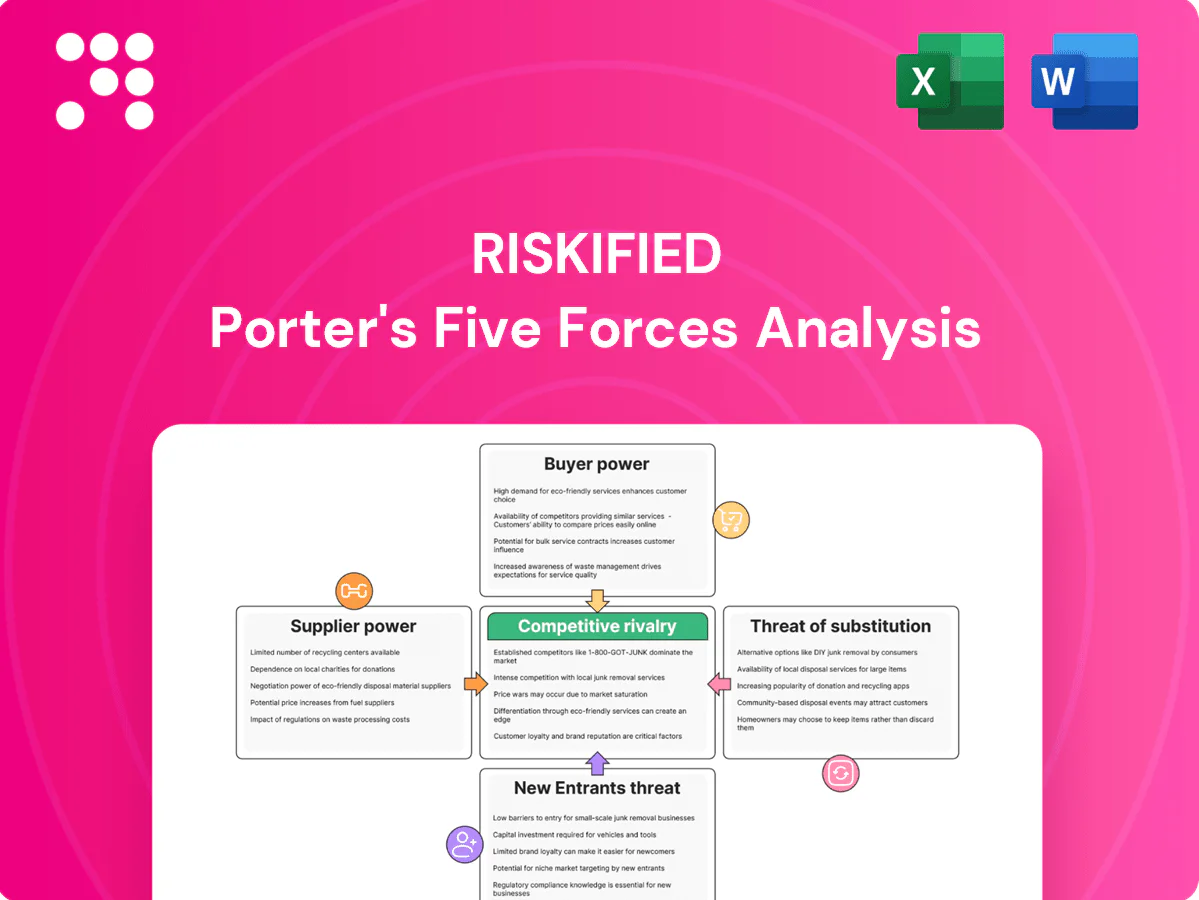
This preview shows the exact Riskified Porter’s Five Forces analysis you'll receive after purchase—fully formatted, professional, and ready to use. It contains the full competitive assessment, supplier and buyer power evaluation, threat of substitutes and new entrants, and rivalry insights. No samples or placeholders; instant download on payment.
Forter, Signifyd, Sift and others contest enterprise deals head-to-head, with multiple vendors routinely shortlisted for accounts processing >$1B annual GMV in 2024. Feature parity in identity graphs, chargeback guarantees and SLAs compresses differentiation, making case studies and rival win stories decisive for vertical credibility and procurement bias. Resulting pricing wars intensify in the largest high-GMV accounts.
Adyen RevenueProtect, Stripe Radar and Shopify-native risk tools bundle fraud control with payments, and Shopify serves ~2M merchants in 2024; bundling has been linked to 10–30% lower attach rates for standalone vendors. Deep PSP-layer data improves native model accuracy, while integrated billing and simpler ops drive merchant adoption.
By 2024, leading merchants such as Amazon and Walmart have scaled in-house risk teams with sophisticated rule engines and analyst pools, enabling selective use of external tools and lowering full-platform spend.
Proprietary transaction data and tight feedback loops let internal models approach or match vendor accuracy, and 2024 industry surveys show many enterprises favor hybrid and in-house-first architectures.
Strong internal ROI narratives and sunk-cost justifications slow displacement of existing vendors despite competitive pressure from platforms like Riskified.
Adjacent bot mitigation and identity verification vendors increasingly target fraud use cases, as credential theft and ATO remain central—Verizon 2024 DBIR highlights credential compromise as a leading breach vector—driving overlap with payments fraud and policy abuse. Suite vendors tout lower TCO versus point solutions, intensifying cross-selling and multi-front rivalry for Riskified.
Competitors iterate features and models on weekly cadences, turning speed-to-signal and data-network effects into primary battlegrounds. Public benchmarks remain scarce in 2024, so vendor claims are validated via POCs and A/B tests. Frequent bake-offs and short release cycles sharply increase rivalry intensity.
Fierce head-to-head contests among Forter, Signifyd, Sift and others compress differentiation for >$1B-GMV enterprise deals in 2024, driving pricing pressure and reliance on vertical case studies. PSP bundling (Adyen, Stripe, Shopify) cuts standalone attach rates 10–30% and Shopify serves ~2M merchants in 2024. In-house/hybrid builds rise; vendors iterate weekly, making data-network effects decisive.
| Metric | 2024 Value |
|---|---|
| Shopify merchants | ~2,000,000 |
| Bundling impact on attach | -10–30% |
| Enterprise shortlist size | Multiple for >$1B GMV |
| Release cadence | Weekly |
Merchants can revert to WAFs, rule engines and manual review as substitutes for AI fraud platforms, trading lower accuracy for direct control and reduced vendor dependency; global e-commerce sales in 2024 were about $5.7 trillion, making cost-control a priority. For stable portfolios, incremental loss from rules-based systems can be acceptable, and during cost-cutting cycles companies often replace AI vendors with these cheaper legacy options.
Strong Customer Authentication (3-D Secure) shifts chargeback liability to issuers under PSD2 and card-scheme rules, and by 2024 3DS adoption in Europe surpassed 80% of e-commerce transactions. Merchants may favor step-up auth to avoid third-party decisioning fees, though added friction can cut conversion roughly 5–15%. As regulation tightens, reliance on 3DS increasingly substitutes for some third-party fraud tooling.
By 2024 many PSPs (Stripe, Adyen, PayPal) increasingly bundle embedded risk services and chargeback guarantees under unified SLAs, creating a single accountable vendor and reducing vendor sprawl for merchants. Blended pricing and consolidated fees make these bundles economically attractive compared with standalone fraud platforms. The payment-layer data footprint—transactional, device and behavioral signals—can rival specialized fraud vendors in depth and real-time coverage.
Shift to BNPL and wallets lets merchants shift chargeback/fraud liability to providers; global BNPL volume hit about 166 billion USD in 2023, reducing merchant exposure on high-risk card BINs as checkout flows bypass card-on-file. This functional substitute weakens demand for standalone fraud tools but raises provider fees and concentration risk.
Chargeback guarantees and recovery services can cap downside by covering up to 100% of disputed amounts, creating a direct substitute for screening systems; they do not stop fraud but transfer financial risk. Simpler procurement and flat-fee pricing often attract smaller merchants. In low-margin categories, net economics frequently favor insurance over costly AI screening.
Merchants often replace AI fraud tools with WAFs, rule engines or manual review to cut costs as global e-commerce reached about 5.7T USD in 2024, accepting lower accuracy for control. 3DS adoption in Europe exceeded 80% by 2024, shifting liability and reducing third-party decisioning. PSP bundles, BNPL (166B USD 2023) and chargeback guarantees transfer risk and compress demand for standalone fraud platforms.
| Substitute | Key stat | Impact |
|---|---|---|
| 3DS | >80% EU (2024) | Liability shift |
| BNPL | 166B USD (2023) | Reduced merchant exposure |
| PSP bundles | Rising adoption (2024) | Vendor consolidation |
Effective fraud models require vast, fresh, cross-merchant data and typically millions of labeled transactions to reach high precision; cold-start entrants without that scale see materially worse accuracy and higher false positives. Feedback loops on disputes and approvals commonly take 12–24 months to mature, slowing learning velocity. These dynamics create a structural entry barrier for new competitors.
PCI, SOC 2, GDPR and regional privacy regimes create high fixed costs—GDPR fines reach €20m or 4% global turnover and IBM’s 2024 average data breach cost was about $4.45m—while global data residency and secure PII handling add operational complexity. Annual SOC audits and certification cadences deter small entrants, and breach penalties can be existential for startups.
Merchants prioritize vendors that underwrite chargeback guarantees, creating a capital-intensive barrier to entry; new entrants typically lack the underwriting reserves and actuarial sophistication required to assume large merchant liabilities. Building statutory reserves and reinsurance relationships takes years and regulatory navigation, so newcomers face extended sales cycles and slower adoption without guarantee capability.
Dozens of PSPs, platforms and order-management systems require connectors, and building and maintaining adapters is resource-intensive; integrating reliably at scale is a major barrier to entry. Entrants struggle to match established breadth and the 99.99% uptime enterprise SLA expectations that customers demand. This integration moat materially lowers the threat of new entrants for firms like Riskified.
Brand trust and referenceability are critical because fraud prevention directly impacts revenue and customer experience, so enterprises demand vendor references and proven KPIs before buying.
New vendors face prolonged POCs and restricted access to high-GMV merchants, slowing market entry and expansion despite technical parity.
Network-scale labeled data (10M+), 12-24m feedback, costly breaches ($4.45M) and 99.99% SLA
Network-scale labeled data (10M+ txns), 12–24 month feedback loops and proven underwriting reserves create structural entry barriers; newcomers suffer higher false positives and slower learning. Compliance and breach costs are material (IBM 2024 avg breach cost $4.45m; GDPR fines up to €20m or 4% turnover). Integration breadth and 99.99% SLAs plus reference-driven sales further limit new entrants.
| Barrier | Metric | 2024 figure |
|---|---|---|
| Data scale | Labeled transactions | 10M+ |
| Learning velocity | Feedback loop | 12–24 months |
| Compliance cost | Avg breach cost | $4.45M |
| Regulatory fine | GDPR max | €20M / 4% turnover |
| Operational SLA | Uptime | 99.99% |


