
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
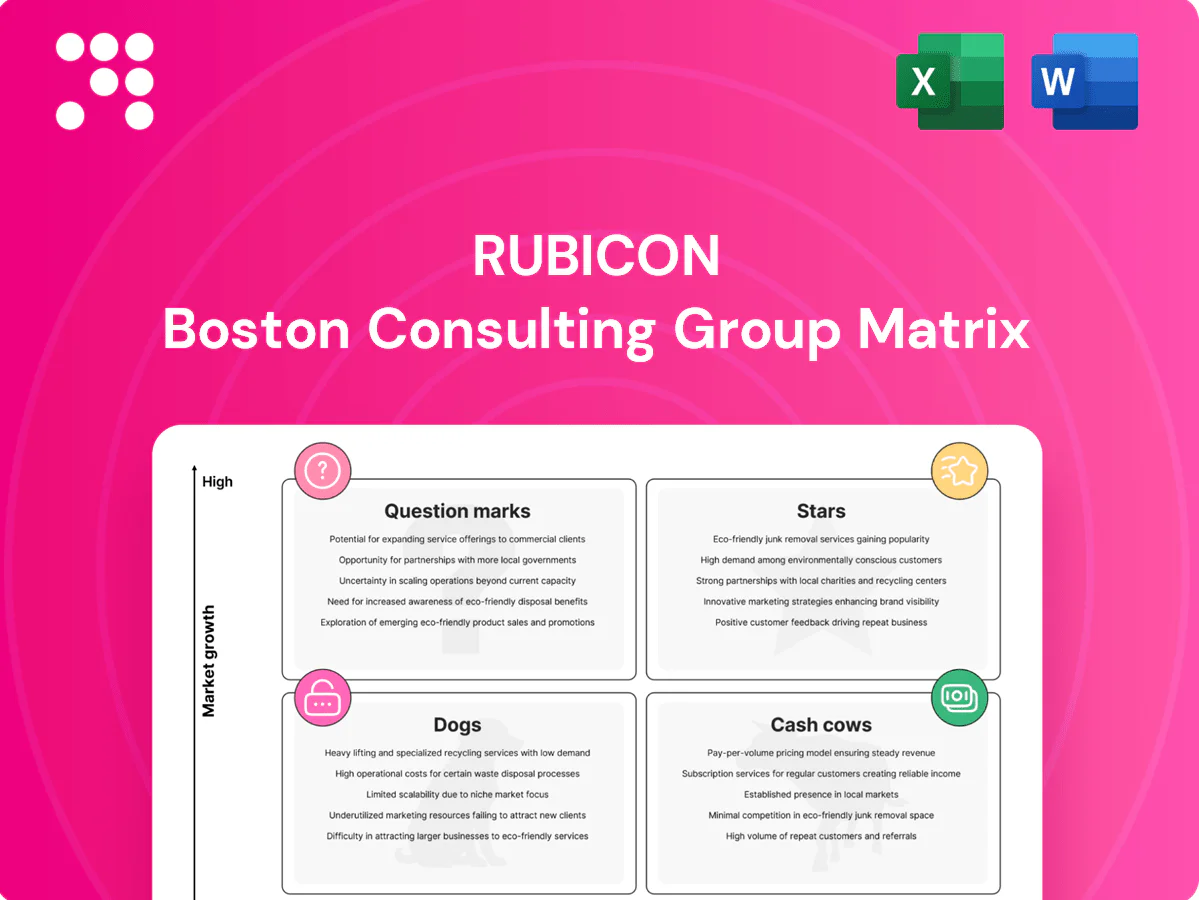
Quick snapshot: the Rubicon BCG Matrix shows which offerings are roaring, which are milking cash, and which are weighing you down—and it’s your roadmap to smarter bets. This preview teases the quadrant placements; the full BCG Matrix gives you the hard data, clear recommendations, and a visual layout you can act on today. Skip the guesswork—purchase the complete report for Word and Excel deliverables, commentary by experts, and a ready-to-use strategy to reallocate capital and accelerate growth.
Enterprise marketplace: core platform matching businesses with vetted haulers at scale; in 2024 Rubicon reported accelerating enterprise traction with double-digit year-over-year adoption as sustainability mandates and cost pressure rise. Leader-like network effects mean each new buyer and hauler increases route density and yield, reinforcing pricing power. Continue investing in growth, hauler onboarding, and brand to hold share and outrun copycats.
National accounts are Stars as multi‑location retailers and QSRs consolidate waste under one digital roof, driving high retention, big‑ticket, sticky integrations and recurring ARR. In 2024, 86% of executives report ESG and cost certainty as strategic priorities, accelerating chain adoption. Market expansion is visible as chains scale platform contracts. Double down on service quality and analytics to cement leadership.
Recycling optimization software lifts diversion rates and cuts landfill fees, with customers reporting 20–40% higher diversion and typical payback under 12 months; corporate demand climbed in 2024 as >70% of large firms set zero‑waste or net‑zero waste targets. Clear ROI and growing enterprise procurement make this a Stars candidate in Rubicon’s BCG matrix. Fund deeper product modules and field enablement to sustain leadership.
Automated metrics for emissions, diversion and immutable audit trails turn operational waste data into investable ESG signals; with EU CSRD phased in 2024 expanding reporting to roughly 50,000 firms, regulatory and investor scrutiny are clear tailwinds. Rubicon’s data moat compounds as pickup-level scans increase coverage; continued integrations and accuracy improvements are required to remain the default vendor for validated ESG metrics.
Independent haulers onboarded nationwide cover niche routes, creating a dense Rubicon hauler network that yields faster, cheaper matches and tighter SLAs. This density is costly and time-consuming for newcomers to replicate quickly, reinforcing incumbent advantage. Prioritize investment in hauler tools, performance analytics and financial incentives to lock in loyalty and convert density into durable margin.
Enterprise marketplace, national accounts, recycling software and ESG metrics are Stars: double‑digit enterprise YoY adoption in 2024, 86% of executives prioritize ESG, recycling drives 20–40% higher diversion with <12‑month payback, and CSRD 2024 puts ~50,000 firms in scope—invest in hauler onboarding, analytics, integrations and service to defend growth.
| Metric | 2024 |
|---|---|
| Enterprise YoY adoption | Double‑digit |
| Execs citing ESG | 86% |
| Recycling diversion uplift | 20–40% |
| CSRD firms in scope | ~50,000 |
 Detailed Word Document
Quadrant-by-quadrant review of Stars, Cash Cows, Question Marks, and Dogs with clear invest, hold, or divest guidance.

 Customizable Excel Spreadsheet
One-page Rubicon BCG Matrix easing portfolio decisions with clear quadrants and export-ready charts
Managed service fees deliver stable monthly revenue streams for Rubicon, with a mature book showing ~90% renewal rates in 2024 and predictable cash flow. Low incremental cost to serve post-implementation supports gross margins typically above 50–60%. Automation and standardized playbooks have cut cost-to-serve by up to 40% in 2024, freeing cash to fund growth.
Annual and quarterly waste compliance packages are a contractual required spend for many clients, driving stable recurring revenue; 2024 benchmarks show B2B compliance SaaS churn often below 5% in mature verticals. The feature set is mature with light upsell potential, so prioritize maintain-and-streamline engineering, reduce cost-to-serve, and implement value-based pricing to protect margins.
SMB subscriptions are a Cash Cow: fixed-tier plans for smaller businesses yield steady ARPU (~$50/month in 2024) with annual churn ≈12% and acquisition mostly inbound/partner. Growth is slower but unit economics are solid, with LTV:CAC >5 and CAC ≈$150 in 2024. Keep CAC low and service delivery templated to protect margins.
Hauler SaaS tools (route, billing, ticketing) act as cash cows: adoption is steady where embedded in partner operations, with high retention even if new feature cadence slows. Prioritize uptime, reconciliations, and modest upsells (price tiers, add-on analytics) to extract margin. Low churn from mission-critical ops keeps steady ARR and cash generation.
Managed services: stable monthly revenue, ~90% renewal (2024), gross margins 50–60% and automation cut cost-to-serve up to 40%, freeing cash for growth.
Recurring brokerage: 3–7 year contracts, renewals 80–90% (2024); focus on routing/procurement to widen spread.
SMB subs: ARPU ~$50/mo, annual churn ~12%, CAC ~$150, LTV:CAC >5 (2024).
| Metric | 2024 |
|---|---|
| Managed renewal | ~90% |
| Cost-to-serve cut | up to 40% |
| SMB ARPU | $50/mo |
The file you're previewing is the exact Rubicon BCG Matrix you'll receive after purchase. No watermarks, no demo content—just a fully formatted, analyst-ready report built for clarity and action. After buying, the same document is immediately downloadable and editable for presentations, strategy sessions, or investor decks. Designed by strategy pros, it arrives ready to plug into your planning with no surprises or extra steps.
Paper recycling brokerage is highly commodity‑exposed and performs poorly in weak price cycles, with single‑digit operating margins and frequent margin compression. Volatility is high—spot recovered paper prices swung by double digits in 2023–24—while the business ties up working capital in receivables and inventory. Little strategic differentiation exists; consider pruning the line or hedging exposure to stabilize cash flow.
One‑off pilots are poorly scoped trials that rarely scale beyond a site or two: 2024 industry surveys estimate about 70% of pilots never progress, with median duration ~9 months and costs often exceeding $100k per site. They are high touch, low return, distract teams, and erode goodwill with haulers and clients; sunset fast unless a clear rollout path and KPI-backed business case exist.
Overcrowded regions: hauling brokerage faces price wars with race-to-the-bottom bids and thin or negative spreads; DAT Freight & Analytics reported 2024 national van spot rates fell about 20% year-over-year, compressing broker margins and lowering loyalty as switching costs stay low. Exit or bundle only with profitable lanes; focus on retaining lanes with positive contribution per load to avoid churn.
Dogs:
Legacy point apps are Dogs: under 5% of ARR (2024) yet drive ~30% of support tickets, high maintenance tax, and no upsell path. They confuse GTM, dilute brand, and reduce engineering focus; retire, migrate, or bundle with clear migration KPIs to cut costs and reclaim capacity.
| Metric | 2024 |
|---|---|
| ARR contribution | <5% |
| Support tickets | ~30% |
| Action | Retire/migrate/consolidate |
Organics marketplace addresses diversion of part of the FAO-estimated 1.3 billion tonnes of food lost or wasted globally by routing food waste to composters and anaerobic digesters. Demand from grocers and campuses surged in 2024 with multiple large chains piloting offsite organics programs, yet supply chains remain patchy and fragmented. Unit economics hinge on contamination rates and proximity to local outlets; viable returns are concentrated in select metros where processing capacity and collection density align.
Rubicon C&D vertical targets routing and recovery of roughly 600 million tons of US construction and demolition debris annually (EPA 2018), a high-volume stream facing tightening state and municipal diversion rules. The market remains fragmented with many local haulers and processors, requiring tailored workflows and certified recovery partners to meet compliance and yield recovery. Pilot integrations with top general contractors before scaling to de-risk logistics and validate revenue per-ton models.
AI contamination detection using computer vision on conveyor streams can cut fines and boost recovery—vendor pilots (AMP, TOMRA) report recovery uplifts up to 30% and contamination drops of 15–25% in 2024 trials—yet ROI at full-scale networks remains unproven. Heavy camera, lighting and compute hardware drives CAPEX (~$500k–$2M/system) and edge compute OPEX. Start with anchor-client pilots to validate payback (typically 2–6 years in pilots) and form vendor alliances to share integration risk.
International expansion (Question Mark): a UK/EU/AUS platform lift‑and‑shift benefits from sustainability tailwinds driven by the EU Waste Framework Directive, the UK Environment Act 2021 and Australia’s National Waste Policy, but regulatory regimes and hauler network fragmentation differ materially.
Go‑to‑market spend could outpace returns initially; land a beachhead via a few multinationals to unlock scale and reference contracts.
Blockchain-style chain-of-custody for recycled content can give brands the credible proofs they demand; CSRD coming into force in 2024 is increasing corporate disclosure pressure, but standards for claims are still evolving, so pilots and third-party audits are essential; if audits validate claims, traceability can be sold as a premium add-on, built with partners, validated, then priced up.
Question Marks: high-growth but capital‑hungry bets—organics (ties to 1.3B t food waste), C&D (≈600M t US stream), AI contamination (pilots +30% recovery), and international lift‑and‑shift/traceability (CSRD 2024). Pilot with anchor clients, validate unit economics, scale only where processing density and regulatory fit converge.
| Market | Size | 2024 signal | Key risk |
|---|---|---|---|
| Organics | 1.3B t global | grocer pilots | contamination, capex |
| C&D | 600M t US | policy tightening | fragmented haulers |
| AI/Trace | — | +30% recovery pilots | high CAPEX, standards |


