
Digital download
Access the files immediately after checkout.
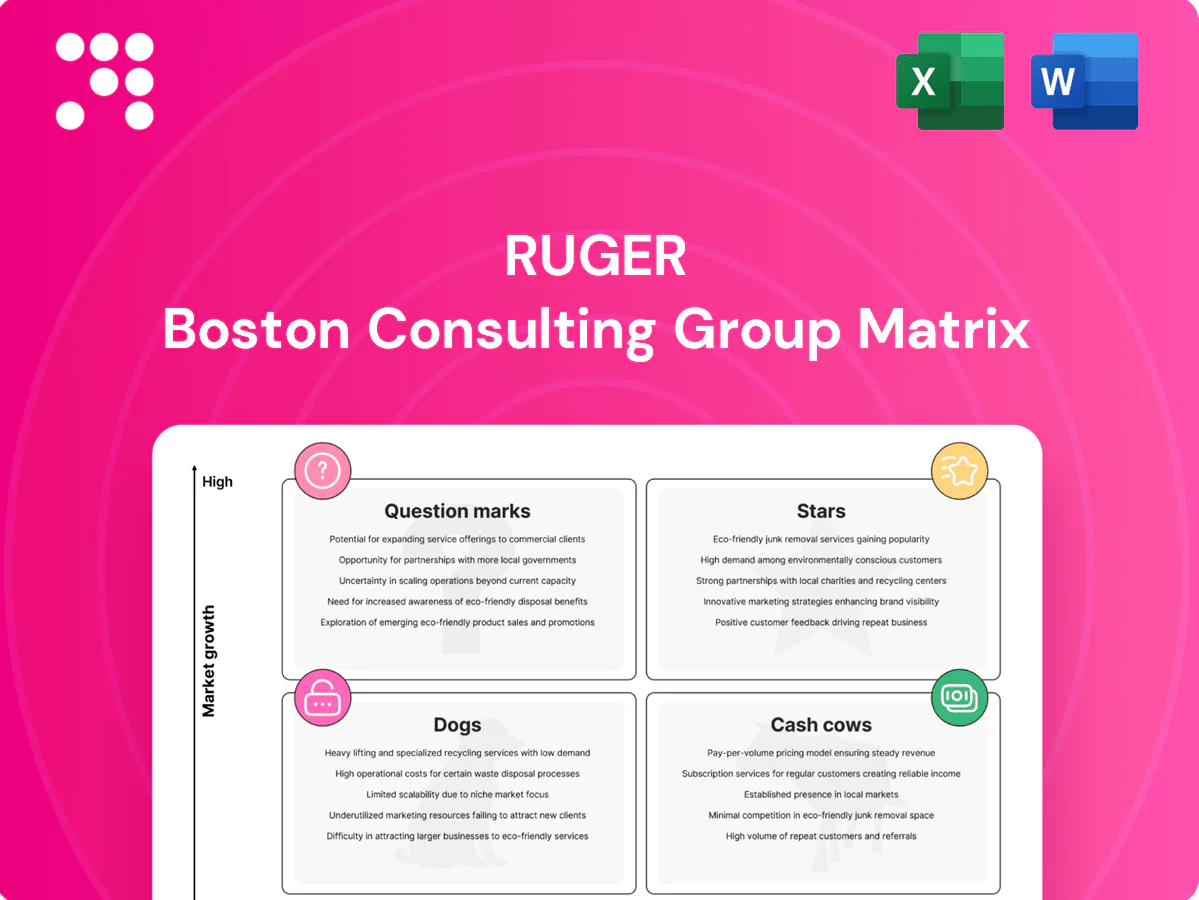
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Ruger’s products land—Stars, Cash Cows, Dogs or Question Marks? This snapshot teases the story; the full Ruger BCG Matrix gives quadrant-by-quadrant placement, data-backed recommendations, and a clear playbook for capital allocation and product focus. Buy the complete report for a ready-to-present Word file plus an Excel summary and start making smarter, faster decisions today.
High-growth concealed-carry demand and Ruger’s strong shelf presence put micro-compact carry pistols squarely in Stars; with US concealed-carry holders near 21 million in 2024 and Ruger reporting FY2024 net sales around $1.28B, these SKUs soak up promo dollars and frequent SKU refreshes but sell-through rates justify the spend. Keep share and they mature into dependable profit machines; invest while the market’s still running hot.
PC Carbine platform is highly modular, takedown-capable and magazine-compatible, checking boxes for sport, home defense and range days while the expanding compact carbine category drives consumer demand.
Ruger showed clear momentum in 2024—FY2024 net sales reported at $1.03 billion with firearm unit volumes up versus prior year—validating investment in the line despite higher variant and accessory spend.
Margins justify continued spend: focus on bundled packages and competitive comps to lock leadership and convert trial into repeat revenue.
Ruger Precision Rifle (incl. Rimfire) sits squarely in Stars as precision shooting participation continues rising and Ruger remains the accessible entry point for newcomers; Sturm, Ruger & Co. reported fiscal 2024 net sales of about $1.53 billion, underpinning distribution reach. Visibility from matches fuels organic demand and social-content momentum, while high growth requires ongoing engineering and content investment. This line anchors Ruger credibility and future upsell potential.
Red-dot carry moved from niche toward mainstream in 2024, and Ruger’s broad optics-ready lineup wins counter space and consideration; fiscal 2024 net sales ~1.9B support the scale to invest. Ongoing co-marketing and SKU complexity add working-capital drag and margin pressure, but owning the transition captures higher-margin future cash flows.
Suppressor-ready SKUs are Stars: adoption is rising as regulations ease and owner education improves; as of 2024 suppressors are legal in 42 states, expanding addressable demand. Threaded barrels and tuned gas systems gain share faster in specialty and direct-to-consumer channels than standard trims. The current base is small but growing quickly; maintain presence to capture and convert early adopters into long-term share.
High-growth segments—micro-compact carry, PC Carbine, Precision Rifle, red-dot carry and suppressor-ready SKUs—are Stars for Ruger in 2024; strong shelf presence and match/optics trends drive share gains while FY2024 consolidated net sales near 1.9B validate scale. Invest in SKUs, bundles and co-markets to convert trial into durable profits while managing SKU complexity and working-capital drag.
| Segment | 2024 signal | Implication |
|---|---|---|
| Micro-compact carry | 21M CC holders US | Invest |
| PC Carbine | Modular demand | Invest |
| Precision Rifle | Match visibility | Invest |
| Red-dot/suppressors | Red-dot mainstream; 42 states legal | Invest |
 Detailed Word Document
Ruger BCG Matrix assesses Ruger’s product lines across Stars, Cash Cows, Question Marks, and Dogs with clear invest/hold/divest guidance.

 Customizable Excel Spreadsheet
One-page Ruger BCG Matrix mapping units to quadrants, simplifying strategy and easing C-suite decisions.
Iconic 10/22, introduced 1964, has produced over 7 million units worldwide, creating a massive installed base and a robust aftermarket with hundreds of suppliers that delivers steady cash flow for Ruger.
Rimfire category growth is low, but steady replacement and gifting demand keep unit volumes stable, so minimal promotion is required while availability drives sales.
Protect margins by keeping SKUs tight, prioritize distribution to never stock out, and focus inventory on core variants.
Mark IV .22 pistols are Ruger’s dependable weekend earner for training, plinking, and tradition, with the Mark line dating to 1949 and the Mark IV introduced in 2016; typical retail pricing in 2024 sits around $499–$599, supporting steady volume sales in a mature .22 LR segment. High share and predictable turns mean light marketing and strong dealer pull‑through; focus on milking efficiency, expanding accessories, and enforcing MAP to protect margins.
Ruger American Rifle (centerfire) is Ruger’s go‑to budget bolt gun with broad caliber coverage from .223 Rem to .300 Win Mag, offering repeatable accuracy that hunters expect. Ruger positions it competitively in the value segment with retail pricing commonly found in the low- to mid‑hundreds, supporting clean distribution through dealers and mass channels. Seasonal promos and steady production help maintain reliable margins when manufacturing runs are smooth, and the model remains a meaningful share driver in the mature hunting rifle market as of 2024.
GP100 and Ruger’s classic revolvers sit as cash cows: a stable, loyal buyer base with repeat purchases and after‑market sales that help fund R&D; Ruger reported roughly $1.57B net sales in FY2024, and legacy handguns remain consistent contributors. Not a growth rocket, but solid cash generation; minimal innovation beyond trims, finishes and limited variants keeps costs low. Run lean, keep quality immaculate, let reputation sell.
Factory mags and core accessories are high-margin, low-complexity cash cows that leverage Ruger’s large installed base; steady demand persisted through 2022–2024 firearm cycle wobble, providing predictable unit sales with minimal promotional spend. Availability and fair pricing sustain volume while margins fund R&D and experimental product launches quietly.
Iconic 10/22 (>7M units) and factory mags deliver steady, high-margin cash flow with minimal promo needs.
Mark IV (.22) at ~$499–599 (2024) and Ruger American (value centerfire) drive predictable volume and dealer pull.
GP100/legacy revolvers and accessories fund R&D while requiring low capex and SKU churn.
Maintain tight SKUs, enforce MAP, prioritize availability to protect margins.
| Product | 2024 Metric | Role |
|---|---|---|
| 10/22 | >7M units installed | Core cash cow |
| Mark IV | $499–599 retail | Steady .22 seller |
| Ruger American | Low–mid $100s | Volume value rifle |
| GP100 & accessories | Supportive margins | Funds R&D |
The file you're previewing is the exact BCG Matrix document you'll receive after purchase. No watermarks, no demo content—just the fully formatted, analysis-ready report designed for clear strategic decisions. It arrives immediately and is editable, printable, and presentation-ready. Buy once and use it across planning, decks, or client work without surprises.
Legacy P‑Series metal‑frame lines in 2024 generate immaterial parts and service revenue, tying up working capital with minimal returns; treat them as cash traps rather than growth drivers. Keep existing service obligations and warranty support but avoid additional capex or inventory replenishment. Wind down SKU count and sunset the line gracefully to free cash for core growth segments.
Beautiful, yes—scalable, no: Ruger ultra‑niche single‑shot runs generate sharp collector buzz but typically account for under 1% of unit sales and contribute marginally to annual revenue. Low velocity and limited channel pull make them cash traps, with secondary‑market premiums often evaporating within 12 months. Collector interest does not translate to repeatable profit; divest or keep strictly as limited, pre‑sold specials.
Dogs:
LE duty pistol pursuits are a crowded sandbox dominated by entrenched incumbents such as Glock, SIG Sauer, and Smith & Wesson; with roughly 800,000 sworn US officers, procurement cycles favor proven platforms, driving high bid costs and low win rates for challengers.
Service load is heavy and even awarded contracts often yield thin margins unless Ruger secures a clear asymmetric edge in cost, warranty, or modularity.
Apparel and tchotchkes tie up SKU slots with soft demand; low turns and limited customer repeat make them Dogs in Ruger’s BCG view. Margins look appealing up front but industry clearance markdowns often exceed 50%, eroding gross margin and inventory ROI. Not core, not compounding — trim hard; prefer licensing to capital deployment.
Dogs consume working capital with low returns: legacy metal‑frame lines and ultra‑niche single‑shots generated immaterial parts/service revenue in 2024 and account for under 1% of unit sales. House suppressors face NFA friction (Form 4, $200 stamp) and $400–1,500 retail, yielding slow turns. Apparel/tchotchkes see >50% clearance markdowns—trim SKUs or license.
| Item | 2024 metric | Action |
|---|---|---|
| Legacy P‑Series | Immaterial revenue | Sunset/limit capex |
| Suppressors | $400–1,500; Form 4, $200 | Partner/divest |
| Apparel | >50% clearance | Cut SKUs/license |
Great thesis: sell the full solution, not just the gun—red‑dot bundles and training tie‑ins can raise attachment rates and spike AOV (industry cases show attachment lifts of ~25%) and boost loyalty; if adoption reaches critical mass it can flip to a Star quickly, but poor uptake drives Dog costs. Firearms accessory market grew ~5% in 2024 to roughly $2.1B, underscoring upside if execution succeeds.
PC Carbine expansions into new calibers, chassis, and comp packages could open fresh lanes but risk fragmenting demand and clogging ops; Ruger reported FY2024 net sales of $786.7M, underscoring the need for disciplined SKU management. Test‑and‑learn with tight runs (pilot batches of 500–1,000) to measure real pull and margin before scaling. Scale only on proven demand signals to protect gross margin and inventory turns.
Direct‑to‑consumer parts and customization meet the base’s demand for easy upgrades, fast shipping and fit‑guarantees; 2024 e‑commerce conversion averages about 2.5% and hobby/gear D2C repeat purchase rates cluster near 28%, so this can be a margin engine or a service headache. Build closed‑loop telemetry and CRM data, manage SKUs ruthlessly (Pareto 20/80), and double down if repeat rates exceed 30% with CLV economics aligned.
International civilian growth is a Question Mark: legal shifts in 2024 can open doors overnight or shut markets; high compliance costs and uncertain demand velocity make ROI unclear; if a reputable local partner materially de‑risks market entry, pursue; if not, conserve capital and wait for regulatory clarity.
Digital safety and training content sits as a Question Mark: it can serve as trust builder, brand moat and top-of-funnel engagement if users show up, but monetization remained unproven in 2024; industry benchmarks showed average e-learning trial-to-paid conversion around 3% and 30-day retention near 18%, so start with community value and measure conversion lift before scaling.
Question Marks: prioritize pilots and measurable signals—test red‑dot bundles, PC Carbine SKUs and D2C parts with 500–1,000 unit runs; pursue international or training only after conversion/retention thresholds hit to avoid margin drag.
| Metric | 2024 Value |
|---|---|
| Accessory market | $2.1B (+5%) |
| Ruger FY2024 sales | $786.7M |
| e‑commerce conv. | 2.5% |
| D2C repeat | 28% |
| e‑learning conv./30d | 3% / 18% |


