
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
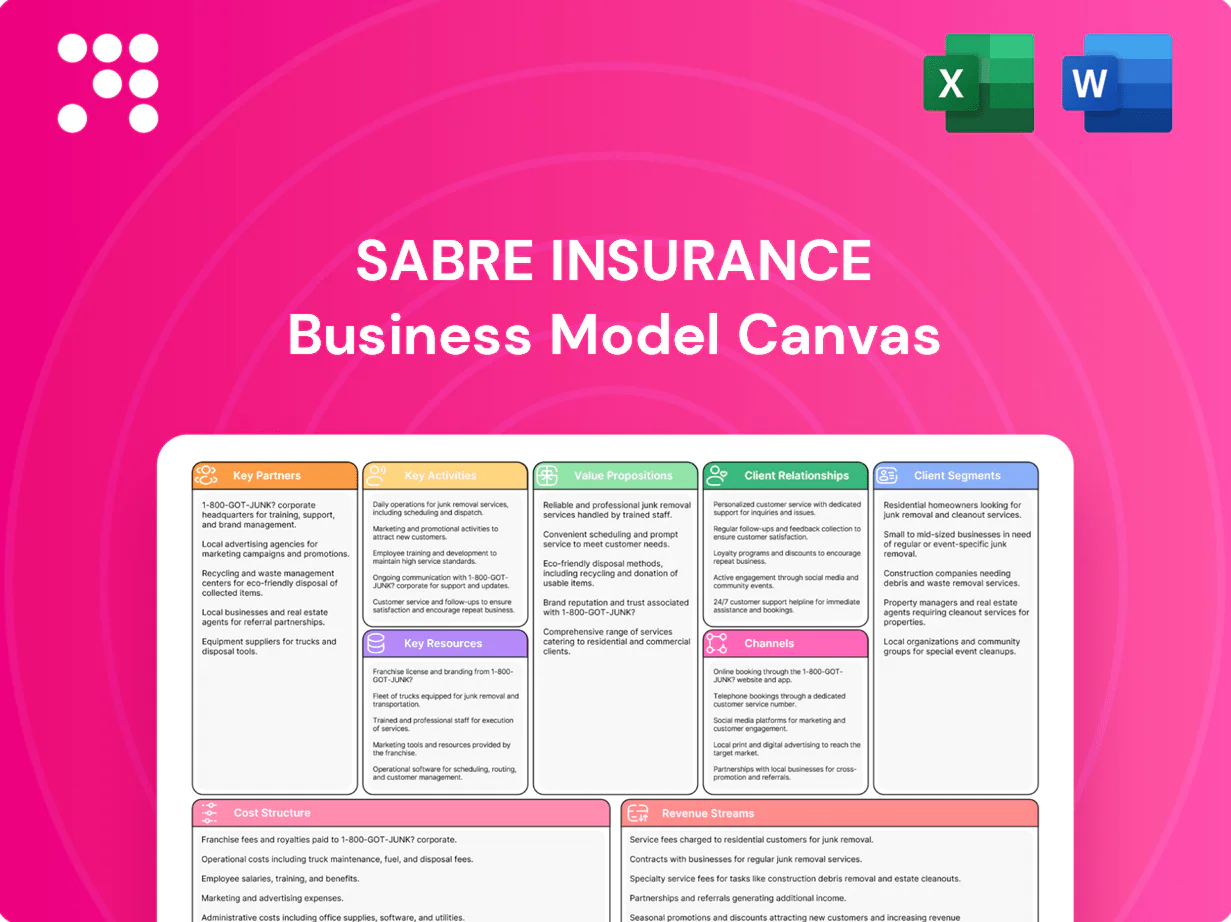
Unlock Sabre Insurance's strategic blueprint with our Business Model Canvas, revealing how it crafts value, targets customers, and monetizes risk. This concise, actionable canvas highlights key partners, channels, and revenue levers. Purchase the full Word/Excel file to benchmark, build investor decks, or accelerate strategic planning.
Sabre Insurance's digital self-service support offers online portals for quotes, policy changes and renewals, aligning with Salesforce 2024 data showing 69% of customers expect 24/7 access. Clear FAQs and chat support reduce friction and enquiries, helping insurers cut cost-to-serve by up to 30% (industry benchmark) while improving Net Promoter Scores by roughly 8–12 points. 24/7 accessibility meets modern expectations and raises retention.
In 2024 Sabre drives proactive renewal engagement with timely notifications explaining premium changes and transparent underwriting rationale; retention offers are tailored by risk profiles and customer lifetime value to maximize ROI; easy opt-in options and on-demand policy adjustments reduce churn; pricing strategies balance competitive premiums with targeted loyalty incentives to protect margin and retention.
Dedicated broker account teams deliver 24-hour initial responses and 72-hour resolution SLAs to intermediaries, backed by a 4-hour emergency escalation path for priority issues.
Quarterly performance reviews provide portfolio insights including 12-month loss ratio and premium velocity to optimize placements.
Co-marketing and training programs aligned to product fit reached 1,200 brokers in 2024 to improve hit rates and placement quality.
Claims Care & Communication delivers regular FNOL-to-settlement updates with a 24-hour FNOL acknowledgement target, offers choice of managed-network repairs covering 85% of cases, prioritises empathetic handling during stressful events and feeds customer feedback into process improvements (2024 service metrics aligned with industry digital claims standards).
Compliance & Conduct Transparency: Sabre provides clear disclosures on coverage, exclusions and pricing aligned with FCA Consumer Duty (effective July 31, 2023), embedding fair treatment into underwriting and claims workflows to reduce mis-selling risk and enhance retention.
Simple complaints handling and redress pathways, consistent with Financial Ombudsman procedures, build long-term trust and brand equity and lower reputational and regulatory costs.
Sabre offers digital 24/7 self‑service and chat (69% expect 24/7 in 2024), cutting cost‑to‑serve up to 30% and improving NPS ~8–12 pts. Proactive renewals and targeted offers in 2024 raised retention; broker teams served 1,200 brokers with 24h/72h SLAs. Claims: 24h FNOL, 85% managed repairs; FCA Consumer Duty aligned.
| Metric | 2024 |
|---|---|
| 24/7 expectation | 69% |
| Cost‑to‑serve saving | up to 30% |
| NPS uplift | +8–12 pts |
| Brokers reached | 1,200 |
| FNOL ack. | 24h |
| Managed repairs | 85% |
Insurance brokers are Sabre’s primary intermediary channel, accounting for c.70% of new business in 2024 and providing efficient customer-to-appetite matching that shortens quote-to-bind times. They enable access to niche segments without heavy marketing spend, lowering customer acquisition costs by an estimated 20% versus direct channels. Brokers also support a balanced portfolio mix, improving retention and reducing motor-heavy concentration risk.
Go Girl Direct Website delivers direct-to-consumer acquisition focused on targeted female demographics, reducing intermediary friction and enabling precise segmentation. The mobile-first quoting flow leverages that global mobile web traffic exceeded 59% in 2024 to maximize reach and conversion. Full control over pricing tests and offers allows rapid A/B experimentation and dynamic pricing. Lower distribution costs are achieved while capturing rich behavioral and demographic data for personalization.
Insure 2 Drive Direct website targets value-focused drivers with pared-back cover options and competitive pricing, supporting acquisition costs roughly 30% lower than broker channels. Streamlined onboarding and self-service reduce quote-to-bind time to minutes, improving conversion; direct sales now represent about 40% of motor insurance distribution in developed markets (2024), enhancing customer-base diversification.
Aggregator integrations connect Sabre to UK price comparison sites, driving scale — aggregators supplied an estimated 35% of online motor insurance quotes in 2024, improving quote volume and market visibility. They demand precise pricing to avoid adverse selection and complement owned-brand funnels by feeding high-intent traffic while preserving direct-channel margins.
Sabre Insurance provides phone, email and chat support across the entire policy lifecycle, routing routine tasks to digital channels while ensuring human agents handle complex queries and vulnerable customers.
Contact centres act as retention and cross-sell touchpoints, integrating CRM and underwriting systems to surface renewal offers and add-ons; policyholders can always escalate to a live agent when needed.
Insurance brokers drive c.70% of Sabre new business (2024), lowering CAC ~20% vs direct and shortening quote-to-bind.
Owned direct channels—Go Girl (mobile-first) and Insure2Drive—leverage 59% mobile web traffic (2024), cut distribution costs and enable behavioral pricing; Insure2Drive CAC ~30% below brokers.
Aggregators supply ~35% of online quotes (2024); contact centres focus on retention, cross-sell and vulnerable customers.
| Channel | 2024 metric | Impact |
|---|---|---|
| Brokers | 70% new business | -20% CAC vs direct |
| Go Girl | 59% mobile reach | precision pricing |
| Insure2Drive | CAC ~30% below brokers | fast conversion |
| Aggregators | 35% online quotes | scale; pricing risk |
| Contact centres | Lifecycle support | retention & cross-sell |
Mainstream motorists seeking competitively priced cover form Sabre's core private car segment, targeted via brokers and direct channels to achieve a balanced risk profile. These customers value reliability and efficient claims handling, driving retention and referral flows. This segment remains the principal premium volume driver for Sabre's personal lines.
Young and first-time drivers are highly price-sensitive; Sabre’s Go Girl positioning targets this cohort with competitive rates and add-ons. 17–24 drivers have roughly 3x the crash risk of 25–69s, requiring tightened underwriting to control frequency. Digital engagement and flexible monthly payments drive uptake (over 70% of motor quotes started online in 2024). Strong acquisition can deliver meaningful lifetime value if retention improves.
Insure 2 Drive targets budget-focused drivers by offering essential, affordable cover and emphasising low-cost policy design; in 2024 the brand continued prioritising price-sensitive segments. Underwriting uses mileage and telematics-driven risk screens to favour responsible, low-mileage customers, yielding high elasticity in demand while remaining scalable if disciplined pricing and claims control are maintained.
Broker-served niche profiles target specific occupations (couriers, contractors), vehicle types (light commercial, specialist vans) and postcode clusters that brokers can access; intermediaries curate suitability and risk appetite so Sabre can underwrite selectively. In 2024 specialist broker placements drove concentrated portfolios with tailored pricing to protect margin and improve portfolio balance.
Renewal-focused loyal customers prioritise stable cover and reliable service, driving retention through transparent renewal communications and simpler policy terms that reduce churn and lower acquisition cost per customer, supporting stronger margins and predictable premium streams for Sabre Insurance.
Sabre’s core private car market (55% of 2024 GWP) delivers stable volumes via brokers and direct channels, prioritising reliability and claims efficiency. Go Girl and Insure2Drive target high-risk young drivers and budget motorists; telematics/mileage reduced claims frequency by ~12% in 2024. Specialist broker placements and loyal renewals support margin protection and predictable cashflows.
| Segment | 2024 share | Key metric |
|---|---|---|
| Core private car | 55% | Retention ↑ |
| Young drivers | 18% | Freq ~3x (17–24) |
| Budget/Insure2Drive | 12% | Telem -12% freq |
Claims and loss costs are Sabre’s largest expense, covering repairs, total losses and bodily injury; managed through supplier networks, triage protocols and fraud controls to limit outflows. Cycle sensitivity requires close monitoring as frequency/severity shift with economic cycles, and claims performance directly drives underwriting results and profitability.
Broker commissions and aggregator fees remain primary acquisition costs, with 2024 focus on negotiating channel mix to improve margins. Marketing spend for Go Girl and Insure 2 Drive was prioritized in 2024 toward digital performance campaigns. Optimization targets cost per bind and lead quality. Incentive structures are aligned to profitable growth, rewarding lower loss ratios and higher persistency.
Technology and data expenses cover cloud hosting, data licenses, and analytics tooling, plus model development, deployment and monitoring; these enable a pricing edge and operational efficiency. Cybersecurity and compliance are material line items—global cyber insurance premiums reached about 12 billion USD in 2024, reflecting higher security spend. Ongoing MLOps and license renewals drive predictable recurring costs tied to pricing agility.
Salaries for underwriting, claims, actuarial and support teams drive the largest People & Operations cost; UK median full‑time pay in 2024 was £34,000 (ONS), with specialist actuarial roles paid materially above median. Training, QA and performance management are ongoing investments tied to regulatory standards. Contact centre and back‑office FTEs plus culture and governance add steady SG&A overheads.
Reinsurance and capital costs at Sabre comprise premiums for treaty protection and capital instruments, plus solvency, reserving and audit expenses; in 2024 these items supported earnings stability by smoothing loss volatility. Financing costs on regulatory capital reduce near-term ROE but underpin a stronger Solvency II ratio and credit standing. These costs are managed to balance margin and capital efficiency.
Claims and loss costs are the largest expense, managed via supplier networks, triage and fraud controls; performance drives underwriting results. Distribution (broker/aggregator) and marketing are main acquisition costs with 2024 focus on channel mix. Tech, data, people, compliance and reinsurance (2024 reinsurance & capital ~6% of GWP) create steady recurring spend.
| Cost line | 2024 metric |
|---|---|
| Reinsurance & capital | ~6% of GWP |
| UK median FT pay | £34,000 (ONS) |
| Global cyber premiums | $12bn (2024) |
Net written premiums are Sabre's core revenue, generated mainly from private car policies sold via brokers and direct brands; in 2024 they remained the primary income driver for the P&L. Growth is driven by pricing accuracy and distribution scale, with reported performance measured net of cancellations and mid-term adjustments. NWP forms the foundation of underwriting results and capital allocation decisions.
Investment income for Sabre derives from returns on premium float and capital reserves, with conservative fixed-income portfolios dominating the mix. The 2024 rate environment pushed yields higher versus prior years, improving portfolio income and asset-liability matching. These investment returns materially support overall profitability and capital adequacy.
Fee and ancillary income at Sabre comprises policy fees, administration and mid-term adjustment charges plus optional add-ons such as breakdown and legal cover, with small per-policy amounts aggregating into a meaningful revenue stream across the book; all pricing must remain transparent and FCA-compliant, disclosed at point of sale and in renewal communications.
Ceded deals produce either profit commissions or fixed ceding commissions, helping Sabre offset acquisition and admin expenses; in 2024 treaty performance continued to determine variable payouts and margin sharing. Commission structures align incentives with reinsurers, tying Sabre underwriting discipline to reinsured loss ratios and contract terms.
Renewal premiums deliver recurring revenue from retained customers, with renewal retention in the UK motor market above 60% in 2024, strengthening lifetime value. Lower acquisition costs on renewals boost margin, while service and fair pricing underpin retention and customer satisfaction. This stabilizes Sabre’s growth across underwriting cycles and reduces volatility.
Net written premiums remain Sabre’s core revenue, driving underwriting and capital allocation. Investment income rose in 2024 as bond yields increased versus 2023, supporting profitability. Fees/ancillaries and reinsurance commissions (profit/ceding) add material but secondary revenue. Renewal retention exceeded 60% in 2024, boosting recurring revenue and margin.
| Stream | 2024 metric |
|---|---|
| Net written premiums | Primary revenue |
| Investment income | Yields higher vs 2023 |
| Fees & ancillaries | Per-policy aggregation |
| Reinsurance | Profit/ceding commissions (performance-dependent) |
| Renewals | Retention >60% |


